The paradox of household loan caps
Tighter limits push borrowers into multiple debts, higher rates
Self-employed caught in 'recession-driven debt' cycle
Experts call for safety nets alongside loan volume controls
A salaried worker in his 30s who bought a home in Seongbuk-gu, Seoul, found himself last summer suddenly needing to cover 70 million won ($52,100) within a month. Having already spent most of his savings on the purchase and renovation, he had no way to manage without additional borrowing.
He ran straight into the wall of banks' household loan volume caps. The most he could borrow from any commercial bank was around 15 million won — far short of what he needed. After looking into capital companies and card loans, he and his wife split the borrowing across two internet banks, barely scraping together the funds. The new loans carried an annual interest rate of 7.5 percent, and his combined monthly repayment on housing-related debt exceeded 3 million won.
"This was originally the kind of loan I could have handled entirely through a first-tier bank," he said. "But with the volume cap cutting off my limit, I was effectively pushed out of the mainstream banking system. In the end, borrowing from multiple places at once turned me into a multiple-debt holder overnight, and the interest burden grew far heavier."
A paradox is emerging from regulations designed to shrink total household debt: some borrowers are being driven into higher interest rates and multiple loans. As individual banks exhaust their lending quotas, borrowers who would ordinarily have secured all the funds they needed from a single bank are now splitting loans across several institutions or turning to non-bank lenders. Critics say that while the policy lowers systemic debt risk at the macro level, it can raise financial costs for individuals and swell the ranks of vulnerable borrowers.
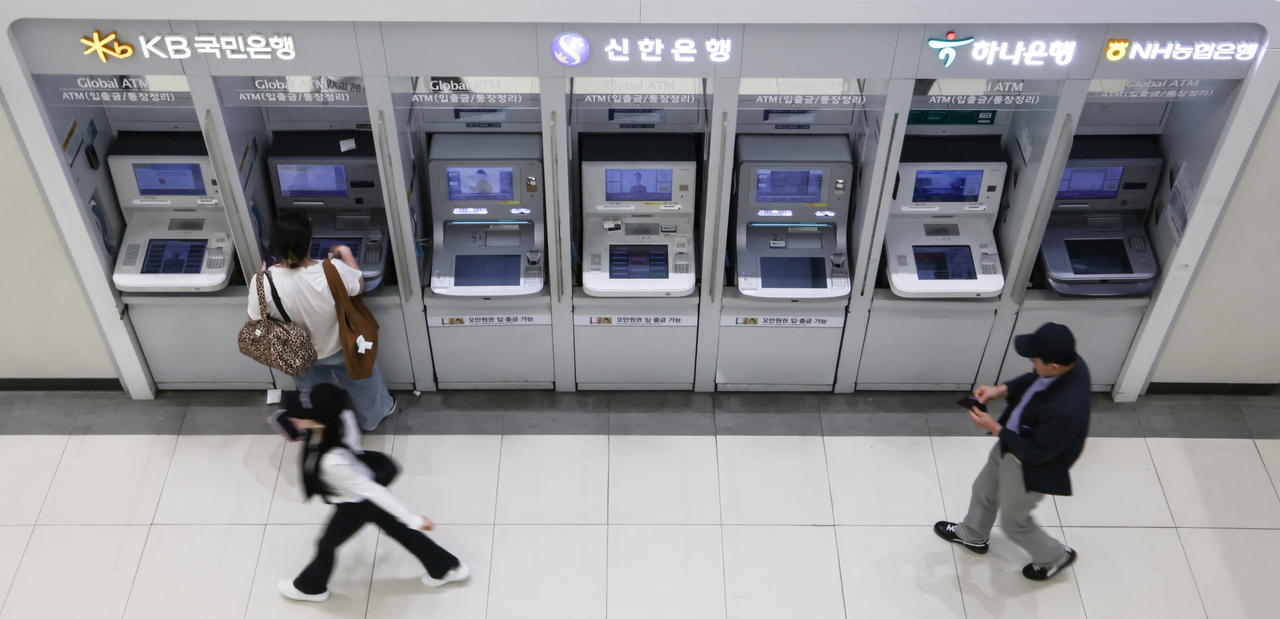
According to financial industry sources Wednesday, the Financial Services Commission set a target of holding household loan growth to 1.5 percent this year and has laid out a plan to bring the household debt-to-GDP ratio down to around 80 percent by 2030. The target is more stringent than last year's household loan growth rate of 1.7 percent. The rationale is to manage the pace of growth before excessive household debt expansion forces borrowers to shoulder heavier repayment burdens during periods of rising interest rates or economic slowdowns, and before it begins to affect the soundness of financial institutions.
The problem, critics say, is that capping total loan volumes at individual financial institutions can produce a "balloon effect," squeezing borrowers who cannot get what they need from banks into non-bank lenders charging higher rates. A former senior financial regulatory official said each institution has no choice but to cut lending limits to meet its volume target. "When borrowers cannot get all the money they need from their primary bank, they go to another bank, and if that does not work either, they end up moving to card companies or non-bank lenders," the official said, adding that the volume controls may be partly responsible for the recent rise in multiple-debt holders.
There are also concerns that the cost of maintaining macro-level financial stability is being passed on to individual borrowers. A senior financial industry official said volume controls can manage macro indicators such as the household debt-to-GDP ratio, but the risk borne by individuals in the process can actually increase. "Even if the system as a whole can absorb it, ordinary people can end up struggling in the meantime," the official said. The official added that safety nets must be in place for young borrowers and multiple-debt holders — unlike high-net-worth individuals — and pointed to the need for mechanisms such as the Korea Inclusive Finance Agency and the Credit Recovery Committee.
Some analysts warn that prolonged volume controls could also distort how borrowers take out and repay loans. Kang Kyung-hoon, a professor of business administration at Dongguk University, said the longer such controls remain in place, the more workarounds emerge, and existing borrowers develop an incentive not to repay out of fear they will be unable to borrow again later. Kang also said policymakers should consider shifting from direct volume caps toward price- and capital-based tools — such as raising the risk weighting on mortgage loans to increase the capital burden on banks.
Financial regulators, however, say the recent rise in multiple-debt holders cannot be explained by loan volume controls alone. For the self-employed in particular, a business downturn that cuts into sales and leaves them short of operating and living expenses can set off what officials call "recession-driven multiple debt" — a slide that typically begins with commercial bank business loans or policy funds, then moves down through savings banks, mutual finance cooperatives and capital companies, then to card loans, cash advances and revolving credit, and finally to loan sharks. As borrowers move further down the financial ladder, interest rates generally rise and credit limits shrink. A single missed payment triggers a drop in credit scores, worsening the conditions for further borrowing and pushing them toward even higher-rate funding in a vicious cycle.
A financial regulatory official said that when economic conditions deteriorate, demand for additional living expenses typically rises and multiple-debt cases increase alongside it. "Recently it appears that this recession-driven demand and the effects of loan volume management are showing up together," the official said, adding that housing transaction-related funding demand also needs to be factored in.
The government has acknowledged that volume controls can make it harder for genuine borrowers to secure financing and has moved to address the gap. Its Aug. 13 package maintained the existing stance on household loan demand management while strengthening financial support to accelerate housing supply and ease funding difficulties for real-demand borrowers, including young people.
Separate from those supplementary measures, rising interest rates are adding further pressure on multiple-debt holders and borrowers relying on non-bank lenders. Those already paying the higher rates typical of non-bank institutions, or carrying several loans at once, face a faster buildup of interest costs as rates climb. The Bank of Korea raised its benchmark interest rate from 2.50 percent to 2.75 percent in July, then lifted it again to 3.00 percent in August. Markets are increasingly pricing in the prospect that the high-rate environment will persist for some time.
rim@heraldcorp.com
hyuk@heraldcorp.com