Won-dollar rate drops nearly 200 won in three months, falling to 1,345
As rate falls, buying decisions grow harder, not easier
Even experts cannot reliably call the bottom
The right approach depends on why you need dollars
Build your own criteria — not a forecast
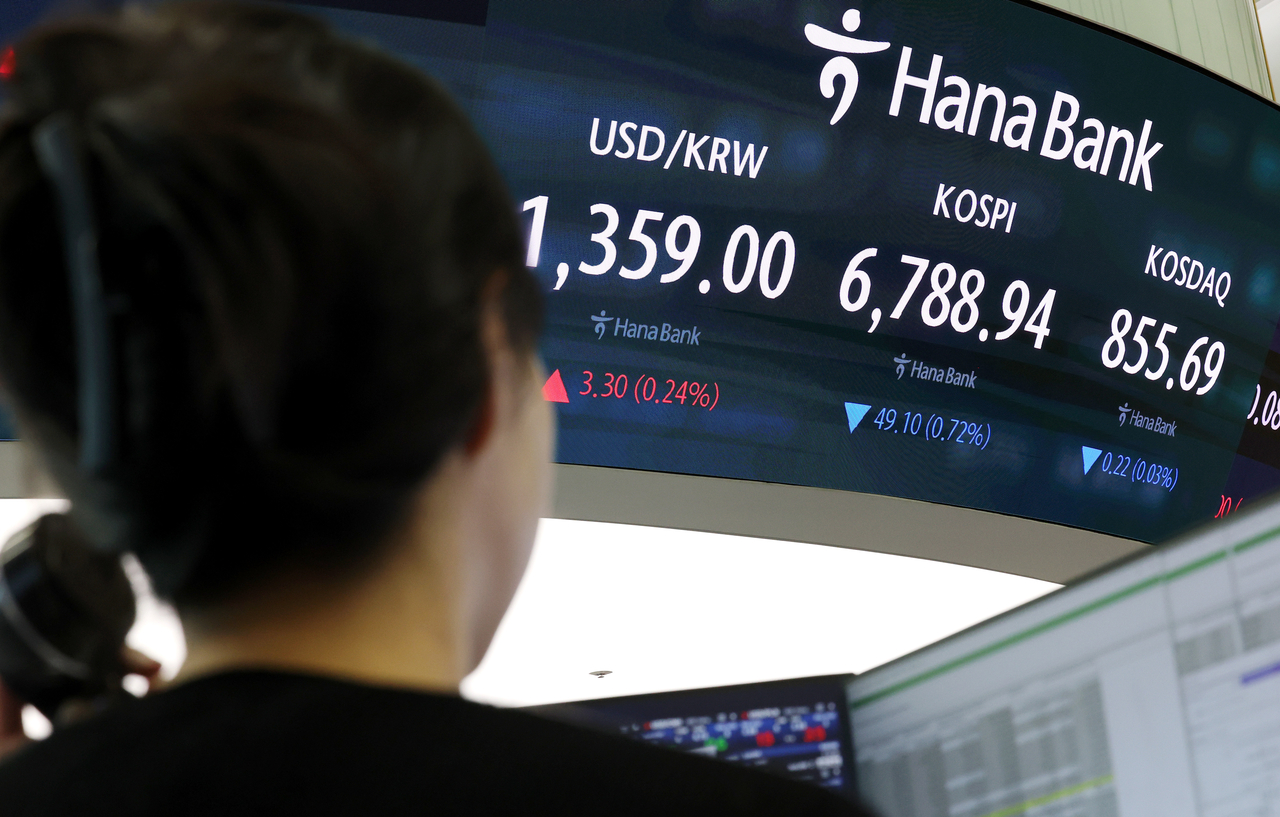
The won-dollar exchange rate has fallen nearly 200 won in three months. After climbing to around 1,550 won in late June, the rate dropped to 1,345 won in overnight trading in early September. A market that just months ago was agonizing over whether to buy dollars at 1,500 won is now asking whether it should wait a little longer for 1,300.
A 200-won difference is far from trivial. Converting 100 million won ($73,600) to dollars, a rate of 1,550 yields roughly $64,500, while a rate of 1,350 yields about $74,100 — around 15 percent more dollars for the same amount of won. For anyone planning to invest in overseas stocks or US bonds, or facing upcoming costs such as a child's tuition abroad or extended overseas living expenses, that gap is large enough to reshape an entire financial plan. The burden of buying dollars has clearly eased compared with a few months ago.
So should you buy now, or hold out for 1,300? It is probably the most common question after a sharp drop in the exchange rate — but it is also the wrong question to start with. Before asking whether the rate will fall to 1,300, you need to decide why you want dollars in the first place.
'God's domain': even experts can't call the bottom
A falling exchange rate might seem to make buying easier, but in practice the opposite is often true. When the rate was above 1,500, anxiety set in: "If it hits 1,600, I should buy before it gets even more expensive." Once it dropped to the 1,350 range, hope took over: "Maybe if I wait just a little longer, it will reach 1,300." The price got cheaper, yet the decision became harder.
The problem is that waiting without a clear benchmark leads nowhere. When 1,300 arrives, 1,250 comes into view. If the rate suddenly jumps while you are waiting, you either freeze — convinced you have already missed your chance — or end up buying at a higher price. When you set your timing based purely on the exchange rate number, your judgment moves with the price. The moment calling the bottom becomes the goal, the more important question — why do I actually need dollars? — gets pushed aside.
Trying to call the bottom is risky precisely because the exchange rate is a figure that even experts struggle to predict. In the foreign-exchange market, forecasting the rate is sometimes described as "god's domain."
Stocks have benchmarks such as corporate earnings and industry outlooks, but the exchange rate cannot be judged by any single country's economic conditions or interest rates alone. A counterpart country's rates and growth, the trade balance, capital flows, commodity prices, geopolitical risk and investor sentiment all move at once, and a single policy statement or shift in the international situation can reverse the direction in an instant.
The recent decline illustrates this well. Trade data released by the Ministry of Trade, Industry and Energy on Sept. 1 showed exports in August reached $98.25 billion, up 68.7 percent from a year earlier, while the trade balance posted a surplus of $34.75 billion. Semiconductor exports hit a record $46.65 billion. The Bank of Korea's preliminary balance-of-payments data for July also showed a current-account surplus of $42.08 billion. A sustained current-account surplus — which covers not only goods trade but also services and investment income — means a steady inflow of foreign currency, a factor that supports the won.
Even so, none of this can determine the direction going forward. If US interest rates stay higher for longer than expected, dollar strength could return. Rising global oil prices or geopolitical instability would also increase demand for dollars. Growing overseas investment by individuals and institutions adds yet another source of demand for converting won into dollars.
Dollars flow in through exports on one side, while investment and import payments push them out on the other. The exchange rate is the price that emerges from these opposing forces colliding.
Explaining why the rate has fallen is an entirely different matter from predicting how far it will go. Past moves can always be given a reason after the fact, but the order and intensity with which those variables will move next cannot be known in advance. A plan to "buy when it hits 1,300" is therefore a plan that can only be executed after correctly calling a number that even experts cannot reliably predict.
What you need is not a forecast — it's your own criteria
The question needs to change. Before asking "Will it fall to 1,300?", ask "Why do I want dollars?" The answer shapes everything: how much you need, how you should buy, and which product is right for you.
The clearest case is someone who has a dollar expense coming up soon. If you need dollars at a fixed point in time — for a child's tuition abroad, long-term overseas living costs, travel, or a deposit on overseas real estate — dollars are not an investment; they are money you must spend. What matters is not a currency gain but securing the dollars you need when you need them, reducing uncertainty around your costs.
Say you need to send $50,000 in a few months. If you wait at 1,350 hoping to buy a little cheaper and the rate rebounds to 1,450, the won you need rises by 5 million won. Conversely, if you convert the full amount now and the rate keeps falling, you will be left with regret.
In this situation, a practical approach is to buy some of the dollars early and convert the rest in stages over a set period, using the date you need the money as your anchor. The goal is not to buy at the lowest possible price but to ensure that the total cost does not hinge on a single day's exchange rate.
When you are buying dollars to invest in overseas stocks or US bonds, you are exposed to two prices at once: the asset price and the exchange rate. Even if a US stock rises 10 percent in dollar terms, a sharp fall in the dollar's value will reduce your won-denominated return. Conversely, if an overseas asset pulls back but the dollar strengthens, your won-based loss is partially cushioned.
That is why "dollars look cheap right now" should not be the only consideration — you need to look first at how much dollar exposure you already have. If you hold a substantial amount of US stocks, adding a large dollar deposit on top could push your overall dollar weighting higher than you realize.
If most of your assets are concentrated in domestic deposits, domestic stocks and real estate, the picture changes. That is where the third purpose — currency diversification — comes in.
For someone earning income and living in Korea, assets tend to be more concentrated in won than they might think. Salary, deposits, real estate, domestic stocks and bonds — nearly all of it is tied to the value of the won. Just as investors diversify between stocks and bonds, or between domestic and overseas markets, currency can also be a dimension of diversification.
In this context, the role of dollars is not short-term currency gains but adding a second currency axis to a portfolio concentrated in won. If that is your purpose, the more important question is not whether the rate is 1,350 or 1,300 but how large a share of your total assets should be held in foreign currency.
Once you have settled on your purpose, the next step is how to buy. If you accept that calling the bottom is difficult, buying in stages is generally better than converting everything at once. If you plan to move 50 million won into dollar assets, you could convert 10 million won at a time — at regular intervals or whenever the rate moves by a set amount. If the rate falls further, you can buy the rest more cheaply; if it suddenly rebounds, you have already secured a portion and can avoid the panic of feeling you must buy before it rises further.
Staged buying does not always produce a better return, of course. If the rate keeps rising, converting everything at the start would have been better; if it keeps falling, buying later is cheaper. The point of a staged approach is not to maximize returns but to reduce the cost of being wrong.
The right product also follows your purpose. If you will need the money soon, a high-liquidity instrument such as a dollar deposit — one you can withdraw and transfer immediately — makes sense. If you have no immediate plans to spend the dollars, short-term US Treasuries or dollar-denominated bonds offer the chance to earn interest income; when US rates are high, holding cash rather than an interest-bearing asset is hard to justify.
However, chasing yield alone is not enough. Even if you earn interest in dollars, a fall in the won-dollar rate will reduce your won-equivalent return. With bonds, you also take on price volatility from interest-rate changes and the credit risk of the issuer.
Ultimately, what matters in buying dollars is not the exchange-rate forecast but your own criteria. If you have already decided why you need dollars, how much, and when, you will not need to rethink your entire plan every time the rate moves. For overseas spending, the anchor is the amount and timing of your need; for overseas investment or currency diversification, it is the share of your total assets you want to hold in dollars. An exchange-rate outlook is useful only as a reference for deciding whether to buy slightly sooner or later, all at once or in stages.
We cannot determine the direction of the exchange rate — it is a price set by countless economic variables and capital flows moving simultaneously. A plan that can only be executed by correctly predicting a specific rate is far less practical than one that can adapt when the rate moves differently than expected. What you need is not to call the bottom. It is to prepare so that your financial plan holds steady even when your forecast turns out to be wrong.
th5@heraldcorp.com