"In an AI-driven market, prepare to endure — not predict"
"Build a 50 million won seed fund before investing any of it"
"Design retirement as a gradual slowdown, not a full stop"
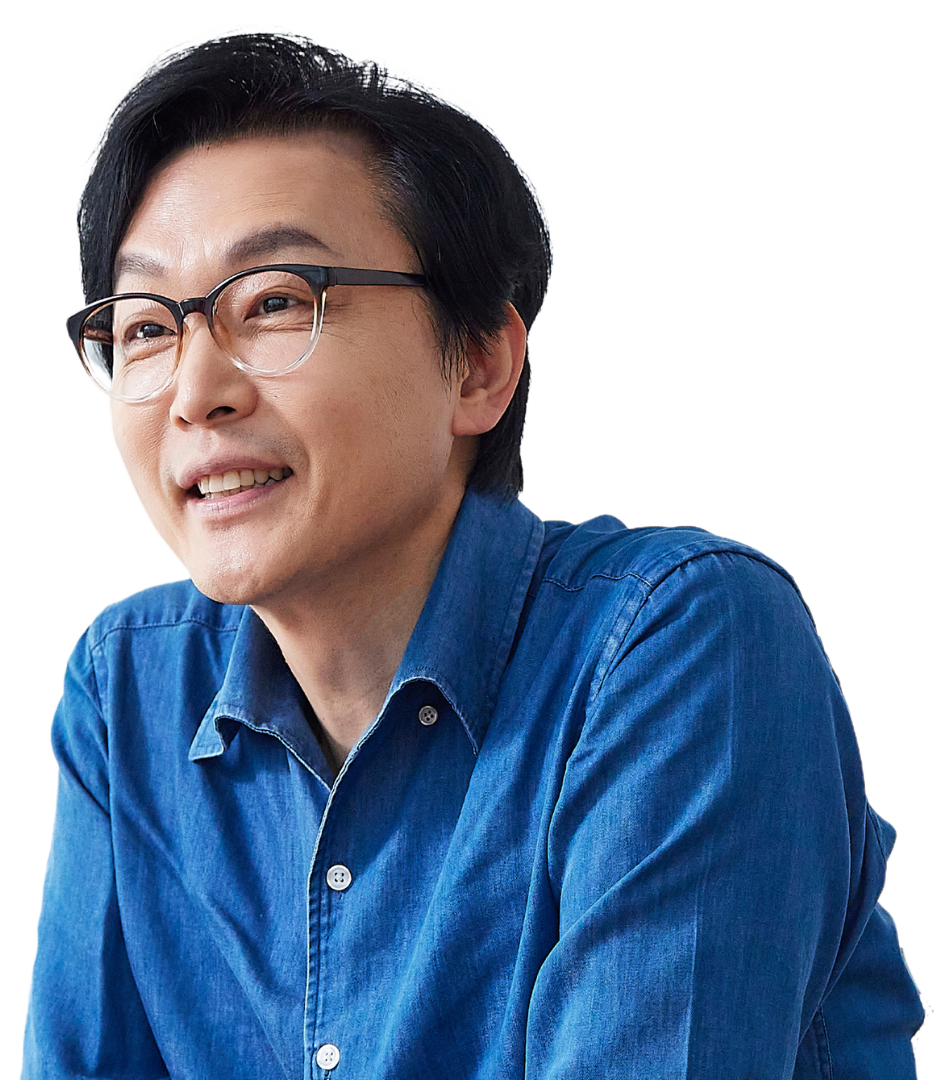
Kim Kyung-pil, chief executive of Money Training Lab and widely known by his online moniker "the money trainer," has a message for investors riding the AI rally: only put in money you can afford to sit with.
His view is that markets are not something to be predicted but something to be endured. Chasing stocks without a solid seed fund, he argues, leaves investors unable to weather a correction. He applies the same logic to retirement, urging people to design their later years not as a hard stop but as a gradual deceleration — what he calls "slow retirement."
In an interview with The Herald Business, Kim declined to forecast the market's direction over the next year. "Whether the AI mega-trend continues to drive the market higher or triggers a correction depends on a range of short-term variables — US inflation, interest rates, the war — and those are simply too hard to predict," he said.
Instead, he urged investors to shift their frame of reference. "If you step back from trading — reacting to every wave the market throws at you — and think in terms of genuine investing, the right move is to buy on dips in preparation for the AI services era that will take hold after 2030," he said.
He attached one condition to that advice. "US equities have kept climbing without any significant correction, so any money you will need within three years should be kept out of individual stocks entirely — this is a time for a strictly long-term perspective," Kim said.
On "money rebalancing," Kim drew a line against treating it as a mechanical exercise of matching real estate and financial assets to a fixed ratio.
"Housing should not be treated as just another variable to balance against financial assets," he said. "The priority — given rising residential costs — must be securing one home that fits your income. That comes first." In his view, a home is not an adjustable variable but a prerequisite.
Rebalancing, he said, applies to financial assets only after that box is checked. Two factors determine the right mix: how much risk an investor can tolerate and how long they can stay invested. His suggested allocations by age group are 70 percent risk assets and 30 percent safe assets for those in their 20s and 30s; 50-50 for those in their 40s and 50s; and 30 percent risk assets and 70 percent safe assets for those in their 60s and 70s.
Before any allocation, he said, investors need capital to allocate. The seed-fund threshold he recommends is 50 million won ($36,100). Only after accumulating at least that amount should investors put a portion of it to work.
"Investment success requires enduring the painful stretches of corrections and downturns," Kim added. "Money that is not truly spare cannot survive those periods."
His warning about FOMO — fear of missing out — has shifted from real estate to equities. He identified October 2021 as the peak of the domestic property market and said the lesson has already been forgotten. "Five years on, many young people this year have chased the market out of FOMO and found themselves stuck in semiconductor stocks," he said.
On slow retirement, Kim said the first thing to fix is how people calculate their target nest egg. He dismissed the conventional benchmark of 2.5 million to 3 million won a month for a two-person household. "That figure is based on averages, and averages no longer mean anything," he said flatly.
Instead, he proposed taking current monthly living expenses, subtracting education costs and loan interest to arrive at net living costs, and then doubling that figure. The logic: a working life structures weekends as leisure, but retirement makes every day a leisure day.
To cover the gap, he outlined four or five income streams: the national pension, a retirement pension, rental income or a reverse mortgage, a personal pension, and earnings from a second job. The national pension pays an average of just 656,494 won a month, he noted, so relying on any single source is not an option.
The case for slow retirement comes down to the limits of investment returns. A retiree who leaves work at 60 with 500 million won and withdraws 3.5 million won a month can sustain that pace until age 74 at a 3 percent return, or until 78 at 6 percent. Doubling the return buys only four more years.
Maintaining 1.5 million won in monthly income, however, cuts the effective withdrawal to 2 million won and extends the runway to age 86 — a gain of 12 years.
"People should aim to keep a second job going into their 60s and 70s — not necessarily for high income, but to stay socially active through slow retirement," Kim said. Even modest earnings, he added, increase activity levels and can address all three of the defining challenges of old age at once: money, health and loneliness.
th5@heraldcorp.com