Revolving balances up for 5 consecutive months, reaching nearly 7 trillion won at end of August
Sluggish real economy sustains demand among self-employed, low-credit borrowers
Card loan balances fall for 3rd straight month amid regulatory volume caps, mid-rate product rollout
Refinancing loans reach 1.7 trillion won, up 47.3 billion won in a single month
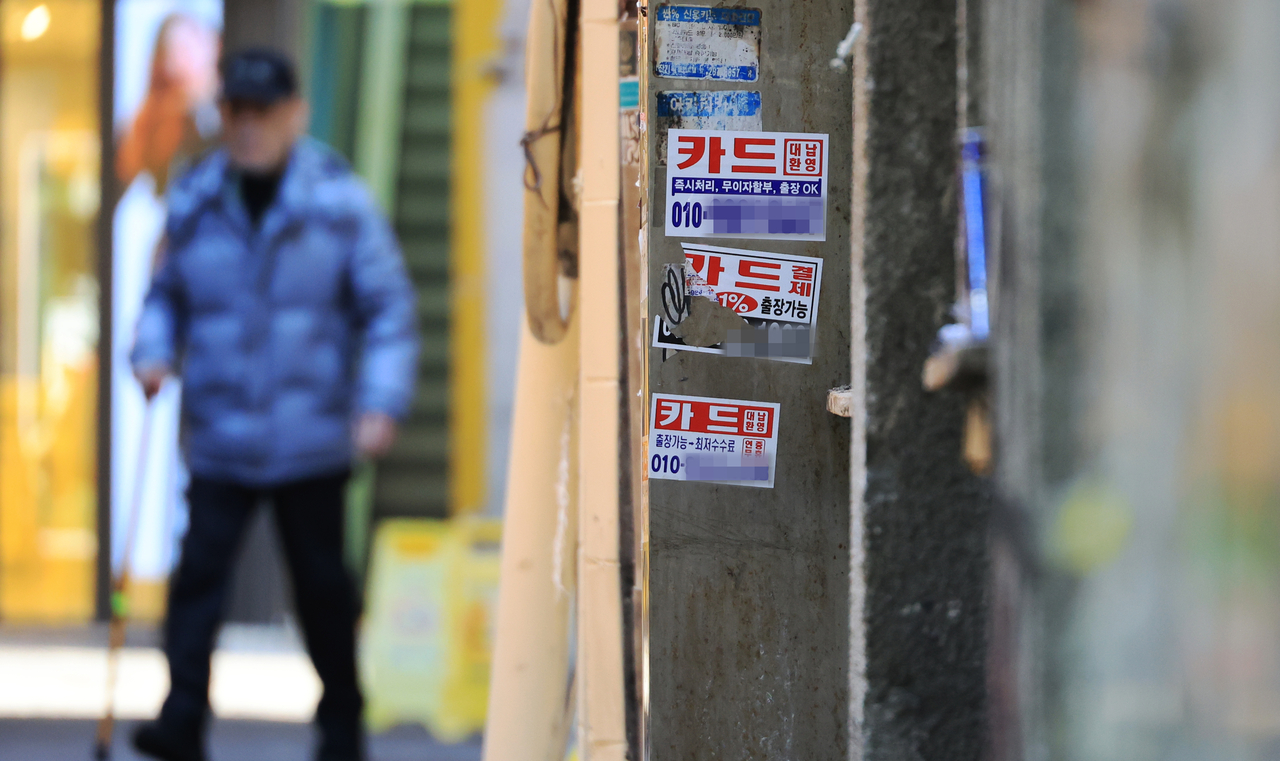
Even as key economic indicators improve on the back of a semiconductor boom, households are still struggling in the real economy. Revolving credit balances — where cardholders carry over part of their bill to the following month — have risen for five consecutive months, with analysts saying the burden of financing and repayment continues to weigh on the self-employed and low-credit borrowers. Card loan balances, by contrast, have fallen for three straight months, but industry insiders say the decline reflects tighter supply under financial regulators' volume management rather than any genuine drop in demand.
According to the Credit Finance Association, the outstanding revolving balance across nine card companies stood at 6.9994 trillion won ($5.06 billion) at the end of August, up 123.5 billion won from the previous month. Revolving balances have risen for five consecutive months since April. Card loan balances, meanwhile, fell 110.5 billion won from the prior month to 42.69 trillion won, marking three straight months of decline. The balance of refinancing loans — new card loans taken out to repay existing ones — rose 47.3 billion won in a single month to 1.70 trillion won.
The credit finance industry points to a slow recovery in the real economy as the main driver of the revolving balance increase. "Economic indicators look good thanks to the semiconductor boom, but the real economy is not doing that well," one industry official said. "Revolving demand tends to rise when the economy is weak. Recently, we have been seeing sustained demand from the self-employed and low-credit borrowers."
Tighter lending conditions across the banking sector have also pushed more borrowers toward card financing, analysts say. "There are reports that even high-credit borrowers are finding it harder to get loans these days," one card company official said. "As banks also face volume management, we are seeing people turn to card company loan products — which carry relatively higher interest rates — including card loans."
Card loan balances have been falling for three months after hitting a record high in May. The balance at the end of last month stood at 42.69 trillion won, down 110.5 billion won from the prior month. The decline continued from 43.25 trillion won in May to 42.91 trillion won in June and 42.80 trillion won in July.
Industry officials say the drop in card loan balances owes more to policy than to any improvement in the economy. Financial regulators have been requiring card companies to keep household lending growth within set volume targets. "It is less that card loan demand has fallen and more that card companies have scaled back their marketing and new loan volumes to meet their targets," one card company official said.
The push to expand mid-rate lending is also reshaping how card companies manage their loan portfolios. With regulators calling for greater supply of mid-rate loans targeting mid- and low-credit borrowers, card companies are preparing to launch related products before year-end. "We have to keep total loan volumes in check while also growing mid-rate lending, so we are reworking our product-by-product supply strategy within a fixed overall cap," one industry official said.
The rise in refinancing loans even as card loan supply tightens suggests that underlying demand has not actually diminished. "Household loan balances are falling, but that does not mean essential funding needs have disappeared," one credit finance industry official said. "It appears that demand not met through card loans is shifting to other card financing products."
snsd@heraldcorp.com