Rising delinquencies put 'seizure-proof' livelihood accounts in the spotlight
Up to 2.5 million won a month shielded from creditor seizure
Demand expected to grow further as interest rates climb
Financial regulators move to ease restrictions and refine the system
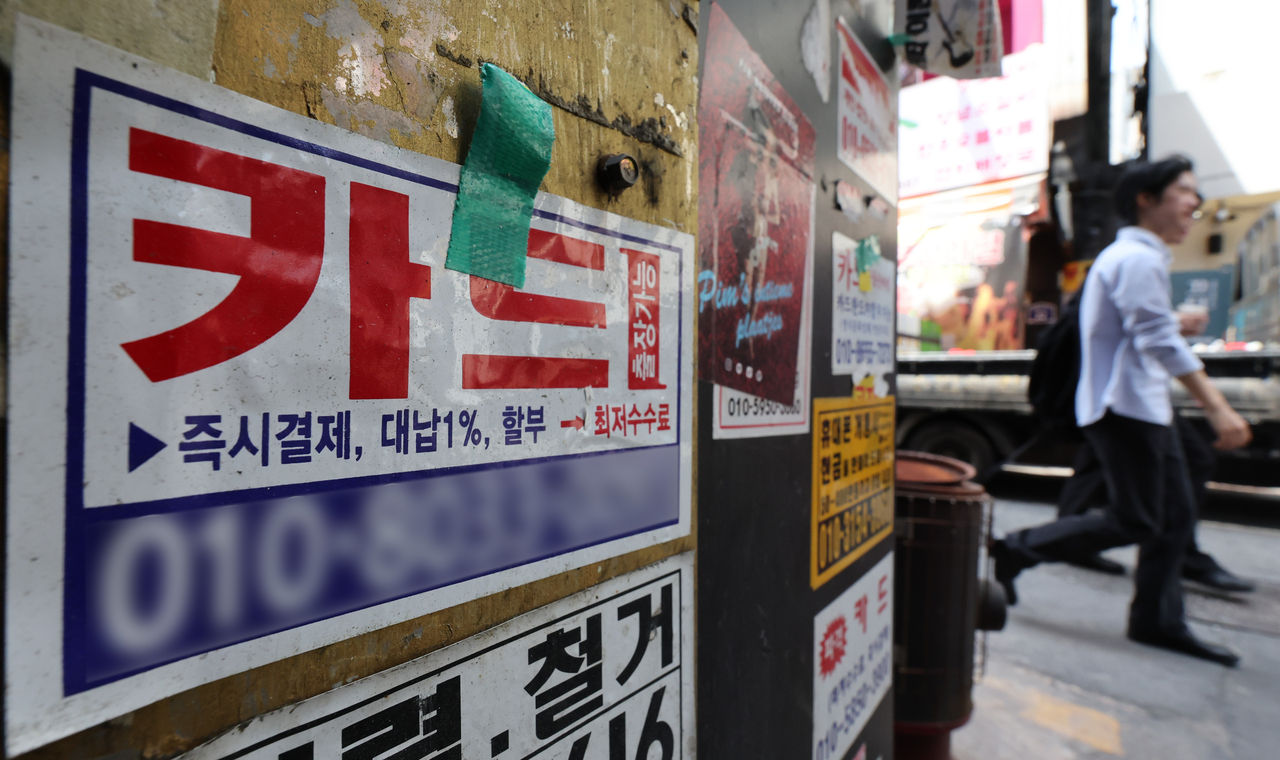
A man in his 40s — identified only by his surname Lee — runs a small restaurant of about 33 square meters in Gyeonggi Province. More than nine months into defaulting on card loans and business loans taken out during the prolonged hardship that followed the COVID-19 pandemic, he watched his primary bank account get seized. Even the modest income still trickling in was swept up by creditors, leaving him unable to pay rent or cover his elementary school-age child's field trip fees on several occasions. He blamed himself every day, wondering whether starting the business had only made life harder for his family.
It was while confiding in an acquaintance that he first heard about "livelihood accounts" — a type of bank account that, once opened, shields up to 2.5 million won ($1,810) a month from creditor seizure. With that protection in place, Lee secured enough for basic living expenses including rent and education costs. The financial breathing room also brought him psychological stability, allowing him to work through debt-restructuring procedures with a clearer head.
Demand for livelihood accounts is rising rapidly among ordinary people struggling with debt on business loans or household borrowing. About 700,000 accounts were opened within six months of the product's launch, driven by the appeal of having up to 2.5 million won a month protected from creditors. With rising market interest rates pushing more borrowers into delinquency, demand is expected to keep growing. Financial regulators and the banking industry are also preparing further improvements to the system under the banner of inclusive finance.
As of Monday, the cumulative number of livelihood accounts opened stood at 687,000. Since accounts became available on Feb. 1, the figure climbed quickly, surpassing 500,000 on June 23 when it reached 531,000.
A livelihood account allows holders to freely deposit and spend up to 2.5 million won per month without fear of seizure. Funds held in the account are classified as seizure-exempt claims under the Civil Execution Act and are therefore protected from creditor action.
The accounts are available at first-tier financial institutions — including commercial banks and internet-only banks — as well as savings banks, mutual finance cooperatives and post offices, with a limit of one account per person. As savings accounts, they also earn a small amount of interest. The system was formalized in January this year when the National Assembly passed an amendment to the Civil Execution Act raising the minimum seizure-exempt amount from 1.85 million won per month to 2.5 million won.
Beyond livelihood accounts, other seizure-proof account types exist — including pension protection accounts and welfare protection accounts. Those products, however, require applicants to meet specific eligibility criteria, such as being a pension or government-benefit recipient, and the funds that can be deposited are similarly restricted to pension payments or welfare benefits.
Livelihood accounts, by contrast, impose no restrictions on who may apply or where the deposited funds come from, meaning anyone — not just benefit recipients — can open one. That openness has drawn attention from people struggling financially due to loan delinquencies since the product first launched.
A man in his 30s, identified only by his surname Choi, is another person who found relief through a livelihood account. To repay 130 million won in debt left by his parents after a failed business, he worked simultaneously at a restaurant and as a day laborer at construction sites for a year — until deteriorating health forced him to stop working for about two months.
While unable to work, he fell behind on card loans and unsecured credit loans he had taken out to cover living expenses and keep up with debt payments. His accounts were seized and he could not even pay rent — until he learned about Kakao Bank's "national livelihood account." Choi said the account allowed him to get back to work and that he has been gradually paying down his debt.
Livelihood accounts also drew praise at a public forum on financial consumer protection held Thursday at the Financial Supervisory Service in Yeouido, Seoul. Kim, a financial consumer representative attending the event, said the accounts allow "people on the edge of life and death to safely use the money they have earned," adding that the system "guarantees the livelihoods of vulnerable people without any taxpayer funding."
As rising interest rates increase the risk of delinquency among vulnerable borrowers, demand for livelihood accounts is expected to grow further. According to the Bank of Korea, the delinquency rate on other loans — including unsecured credit loans — in the financial sector rose from 1.87 percent at the end of last year to 2.04 percent at the end of the first quarter of this year. Among consumer finance lenders such as credit card companies and savings banks, the rate climbed more sharply over the same period, from 2.77 percent to 3.08 percent.
The Financial Supervisory Service has also moved to refine the system to meet growing demand. Until now, banks allowed each customer to hold only one "limited-transaction account" — an account that can be opened without proving a specific purpose such as receiving a salary, but which carries restrictions on transfers and withdrawals. Customers who already held such an account at a given bank sometimes found it difficult to open an additional livelihood account there.
The Financial Supervisory Service has issued guidelines to banks allowing customers who already hold a limited-transaction account to open a livelihood account on top of it. The regulator is also pursuing a measure that would allow people whose accounts have been suspended due to unwitting involvement in crimes such as voice phishing to open a livelihood account, provided the need for livelihood protection — such as seizure of other accounts or bankruptcy — is clearly demonstrated.
Starting next year, a "split-transfer" system for livelihood accounts is also set to take effect. Currently, any incoming transfer that exceeds the monthly cap of 2.5 million won is blocked entirely. Under the new arrangement, up to 2.5 million won of any transfer will go into the livelihood account, while the amount above the cap will be automatically routed to a separate management account designated in advance by the account holder. The Ministry of Justice announced the proposed amendment to the Civil Execution Decree in July.
A Financial Supervisory Service official said the regulator would "continuously monitor how livelihood accounts are being opened and used, and work to address any inconveniences in the process," adding that it would "actively identify vulnerable people who need livelihood accounts through outreach and promotional activities."
hyuk@heraldcorp.com