Delinquency rate on 1 million won cap anti-illegal-lending loans
Climbs from 11.7% in 2023 to 43.7% in 2026
Borrowers under 30 hit 50% delinquency rate as of end of August
Rep. Park Jun-tae calls for debt restructuring and stronger welfare, employment support
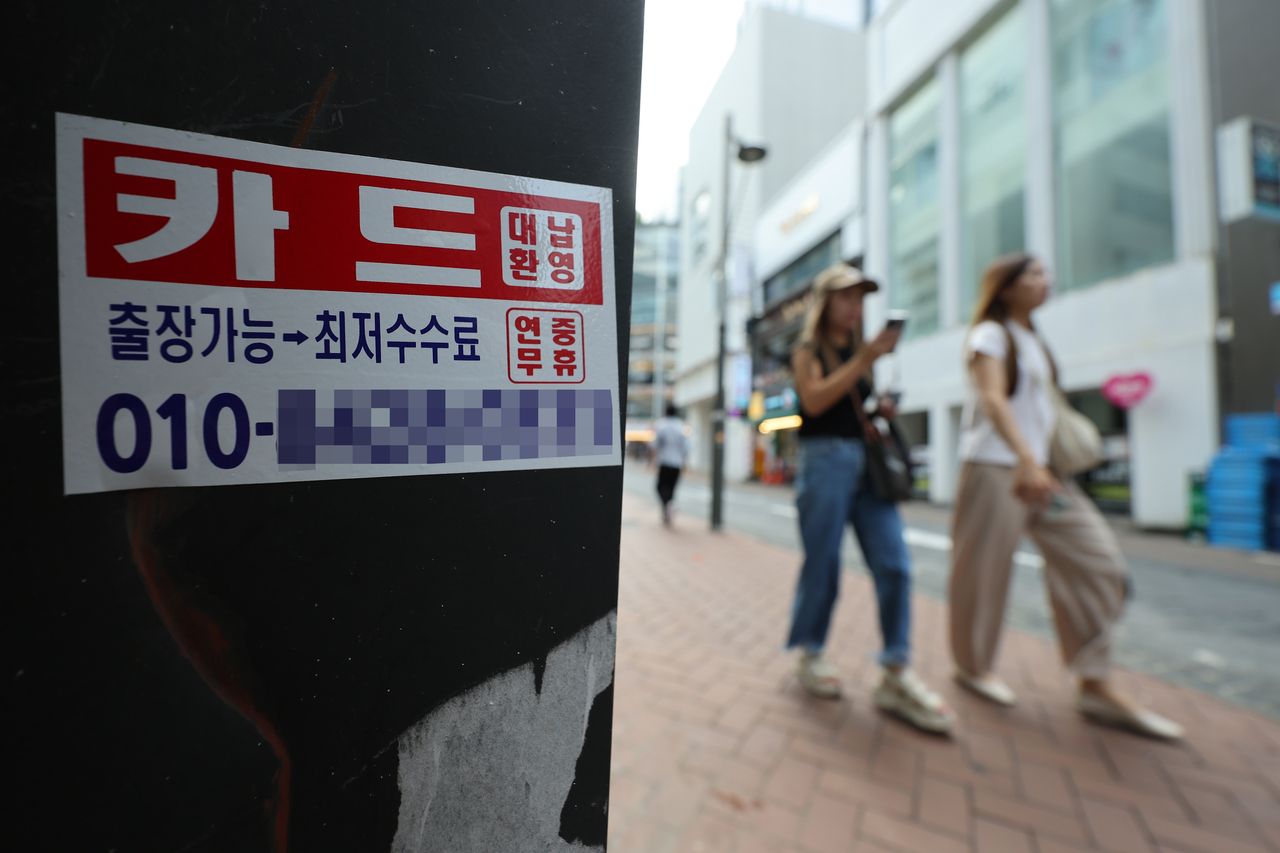
The delinquency rate on a loan product created to steer financially vulnerable borrowers away from illegal private lenders has surpassed 40% in roughly three and a half years since its launch, raising calls for a stronger financial safety net for low-income households.
Data submitted to People Power Party lawmaker Park Jun-tae of the National Assembly's Political Affairs Committee by the Financial Services Commission show that the over-one-month delinquency rate on the so-called anti-illegal-lending prevention loan stood at 43.7% as of the end of August. The total number of delinquent cases reached 222,244, with the overdue amount totaling 134.6 billion won ($101 million).
The delinquency rate on the product climbed steadily — from 11.7% at the end of 2023 to 32.2% at the end of 2024 and 37.8% at the end of 2025 — and has continued to rise this year.
By age group, borrowers in their 20s and younger posted the highest delinquency rate at 50% as of end of August, with 53,679 cases totaling 32.4 billion won in arrears. The rate for that group was 16.9% at the end of 2023, rising to 38.7% the following year and 43.7% by the end of 2025.
Borrowers in their 30s followed at 44.7%, with 50,757 delinquent cases worth 31.5 billion won. Those in their 40s stood at 42.6% (43,462 cases; 26.8 billion won), those in their 50s at 40.9% (36,960 cases; 22 billion won), and borrowers aged 60 and older at 39% (37,386 cases; 21.8 billion won).
The anti-illegal-lending prevention loan was designed to keep financially vulnerable people — those who lack even a small amount of living expenses — from turning to illegal lenders. It launched in early 2023 under the name "small living-expense loan" before being rebranded in 2025 with the explicit aim of blocking borrowers from entering the illegal private lending market.
Eligibility is limited to borrowers with an annual income of 35 million won or less, or those earning up to 45 million won who fall in the bottom 20 percent of credit scores. The maximum loan amount is 1 million won, offered at a base annual interest rate of 12.5 percent — or 9.9 percent for socially disadvantaged borrowers — repayable in equal monthly installments of principal and interest over two years. A borrower taking the full 1 million won would owe 47,307 won per month.
The volume of loans issued has eased somewhat this year. A total of 165,325 loans were extended in 2023, followed by 180,947 in 2024 and 174,974 in 2025. Through August this year, 93,840 loans had been issued. However, the average loan amount rose from 760,000 won the previous year to 890,000 won this year.
Financial regulators had projected from the outset that the delinquency rate would converge toward 50%, and the current trajectory is broadly in line with that forecast.
Even so, concern is growing over the rising number of borrowers who cannot repay even a loan with monthly installments of less than 50,000 won. Observers say this may signal that the repayment capacity of vulnerable households has reached its limit, and that the government needs to shore up its support framework for low-income borrowers and put in place meaningful pathways to financial recovery.
The delinquency rate among borrowers in their 20s and younger reaching 50 percent has drawn particular attention, with calls for a closer look at the precarious economic circumstances facing young people and their limited financial literacy.
"If the government anticipated a high delinquency rate, it should also have prepared measures to address the repayment crisis facing vulnerable borrowers," Park said. "Debt restructuring and stronger welfare and employment support are needed to ensure that delinquent borrowers are not pushed into the arms of illegal lenders."
hyuk@heraldcorp.com