Korea Exchange launches after-market, expanding evening trading to about 2,700 stocks
Low-liquidity stocks now included, raising price volatility concerns
VI and market-making systems in place but limited in addressing thin order books
ETF and ETN exclusions, low institutional participation cap practical gains
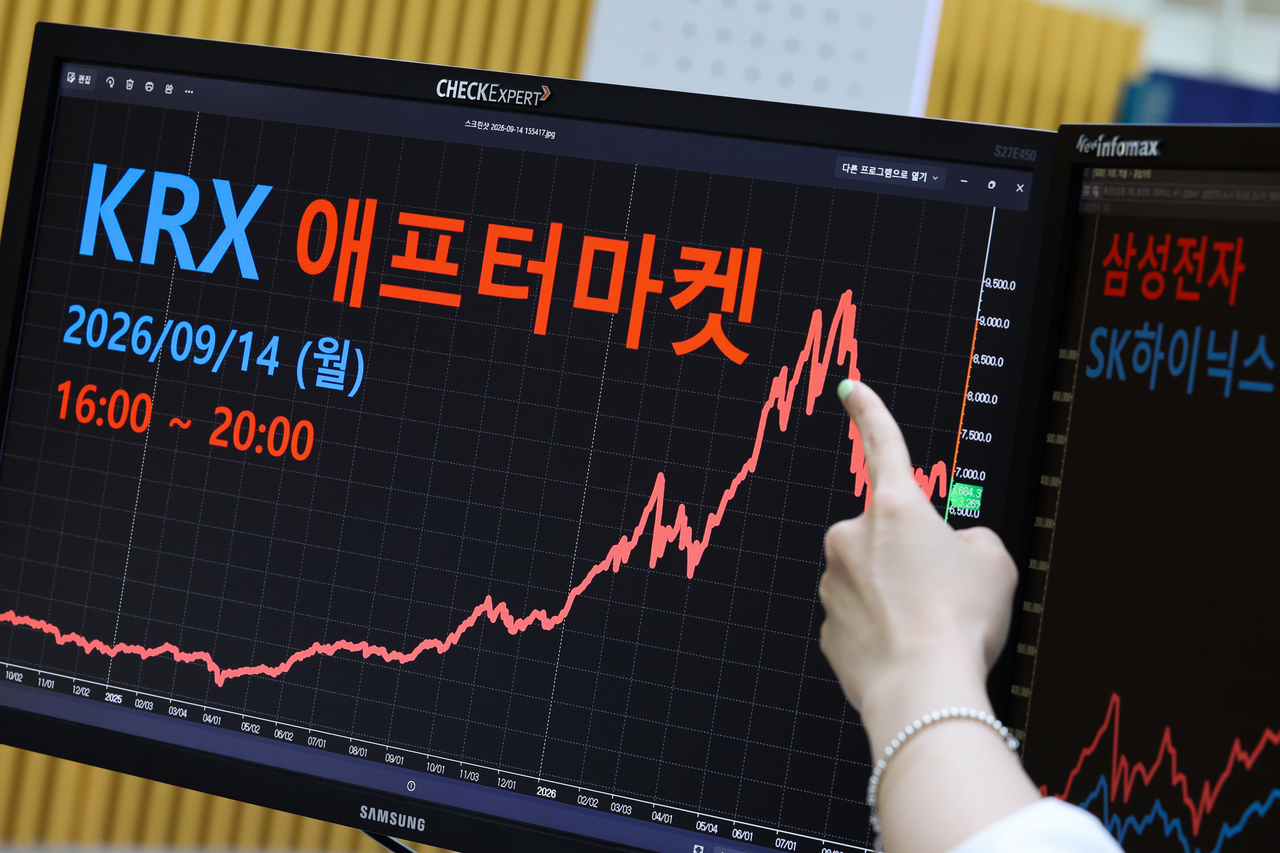
Korea Exchange launched its after-market Monday, entering the after-hours stock trading arena.
The evening market, which alternative exchange Nextrade had effectively run alone for a year and a half, now faces competition — but some in the industry say the practical change for investors is limited, while the expansion of evening trading to low-liquidity stocks has widened volatility risks.
According to the financial investment industry, the Korea Exchange after-market runs from 4 p.m. to 8 p.m. The existing 4–6 p.m. off-hours single-price auction has been abolished, replaced by a continuous auction system identical to the regular session, where orders are matched in real time. To account for thin liquidity during evening hours, only limit orders, best limit orders and most favorable limit orders are accepted — market orders are not.
The most visible change for investors is the number of tradable stocks. Nextrade's after-market covers only about 600 stocks. Korea Exchange, by contrast, includes nearly all Kospi- and Kosdaq-listed shares, excluding a handful under market surveillance such as investment-warning and delisting-process stocks. With 2,766 stocks currently listed, the number available for evening trading more than quadruples.
The problem is that a large portion of the roughly 2,000 newly added stocks are not actively traded even during regular hours. A thin order book means buy and sell orders are not stacked in layers across price levels.
In stocks with deep order books, even heavy selling is absorbed as successive buy orders at lower price levels step in to cushion the impact. In stocks with sparse orders, a single order can exhaust one price level and jump straight to the next, and the wider the gap between levels, the more sharply the execution price swings. Even small orders can move prices by several percentage points. Evening hours amplify this vulnerability, as institutional and foreign participation is comparatively low.
How prices can be distorted in off-hours markets was already demonstrated this year. SK hynix's opening price hit the daily lower limit on Nextrade's pre-market on two separate occasions roughly a week apart. When trading opened at 1.168 million won ($868) — 29.98 percent below the previous day's closing price — only 11 shares changed hands. Because the opening price under a continuous auction is set by the first trade rather than a single-price auction, that figure became the official opening price as-is.
At the time, Nextrade's pre-market had only a dynamic volatility interruption, or VI, which compares prices against the most recent execution. The opening price had no reference point and was confirmed without any brake. Nextrade responded by introducing a static VI based on the previous day's closing price, which took effect Monday.
Korea Exchange's after-market launched with that lesson already built in. Both dynamic and static VIs — identical to those in the regular session — apply from the outset. If an expected execution price breaches the threshold, the order is not immediately matched; instead, bids are collected for two minutes and a new price is set through a single-price auction. A dedicated market-making program for the after-market also operates for stocks with insufficient liquidity.
The key question is how far these safeguards can cover the vulnerabilities of low-liquidity stocks. A VI controls sharp price movements but does not itself fill the missing buy and sell orders. It also operates stock by stock, which limits its reach.
The market-making program similarly applies only to stocks covered by pre-arranged contracts. Having price-control mechanisms in place does not resolve the thin liquidity of the roughly 2,000 newly added stocks.
The structural weaknesses of off-hours trading have been flagged repeatedly in overseas markets as well. The Financial Industry Regulatory Authority in the United States notes that while off-hours trading volumes are growing, they still fall far short of regular-session volumes, and cites illiquidity as a leading risk.
Lee Chang-wook, head of the securities sector at the National Office and Financial Services Workers' Union, raised concerns at a stakeholder forum on extending Korea Exchange's trading hours. "When the United States extended trading hours, liquidity became fragmented and problems such as wash trading emerged — we could face similar transparency issues," he said. "The information asymmetry between foreign and institutional investors on one side and retail investors on the other is enormous. Extending trading hours unconditionally, with no alternative safeguards, is pushing retail investors into a gambling den."
Whether the market will actually grow in scale is also uncertain. The primary users of evening trading are retail investors, not institutions. One official in the investment and asset management sector said institutional use of the after-market is extremely low, adding, "Just because there are now two markets does not mean after-market trading volume will double."
The exclusion of ETFs and exchange-traded notes, or ETNs — products with a growing retail investor base — further limits the practical benefit. Investors who manage assets through pension accounts and ETFs will find nothing to trade even with the evening market open.
The burden on brokerages is clear. In a Korea Exchange survey, 38 of about 50 member securities firms said they would participate, representing a combined market share of 95.2 percent — effectively the entire industry. One industry official said longer trading hours inevitably increase operational workloads, adding that smaller brokerages gain little from the expansion while bearing the full cost.
That said, extended trading hours are not without merit. Earnings releases and overseas developments after the regular session close can be priced in without waiting until the next morning's open, reducing the risk of a sharp gap at the next day's opening price. The ability of foreign investors to trade Korean stocks during their own time zones also improves market accessibility.
th5@heraldcorp.com