Delinquency rate forecast at 1.74% in Q2 next year, up 0.2 percentage points from this year
Card spending stuck in low-growth phase for 39 consecutive months
Soaring funding costs squeeze card loan profitability and asset quality
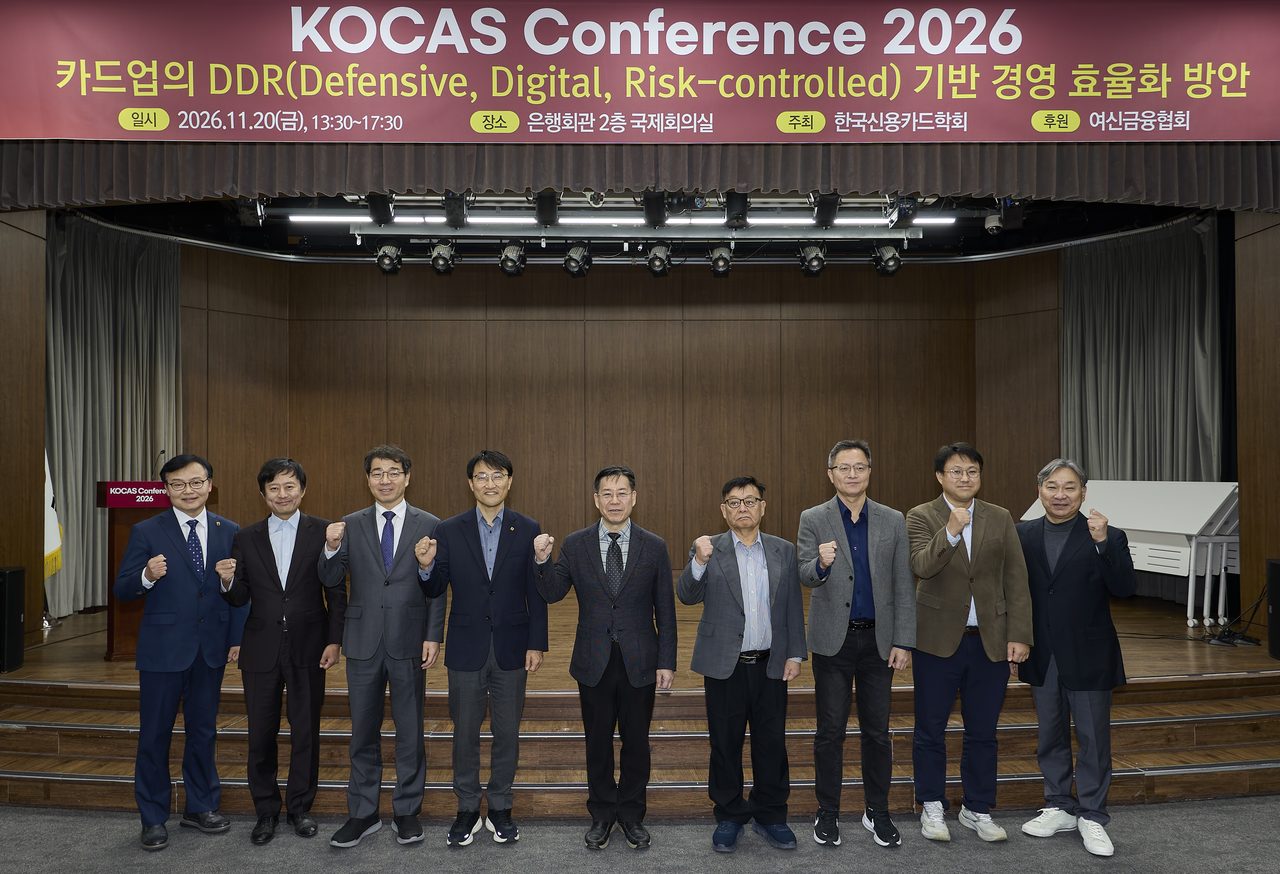
When card bond yields rise, credit card delinquency rates follow roughly a year later — and if historical patterns hold, the delinquency rate at dedicated card companies could climb to 1.74% in the second quarter of next year. That warning came Friday as analysts cautioned that card firms face simultaneous pressure on profitability and asset quality, with spending growth stalled for more than three years and funding costs surging.
Yoon Jong-moon, a director at the Credit Finance Research Institute, presented the findings at the KOCAS Conference 2026, hosted by the Korean Credit Card Association at the Korea Federation of Banks building in Jung-gu, Seoul.
According to Yoon's analysis, a 1-percentage-point rise in the yield on three-year card bonds is associated with a 0.16-percentage-point increase in the card delinquency rate approximately one year later. The lag reflects roughly four quarters between a shift in market rates and its effect on actual delinquencies.
Based on that relationship, the projected delinquency rate for dedicated card companies in the second quarter of next year stands at 1.74%, up 0.2 percentage points from 1.54% in the second quarter of this year. The rate could rise a further 0.25 percentage points year-on-year in the third quarter of next year. Yoon cautioned, however, that the projections assume the historical statistical relationship between interest rates and delinquencies continues to hold.
"There was no significant relationship between the low-growth phase and delinquency rates — in fact, the relationship with interest rates was far stronger," Yoon said. "Card companies need to use changes in card bond yields to forecast delinquency rates about a year out and incorporate that into their risk management."
The slowdown in card industry growth has also become entrenched. An analysis of card spending data showed the low-growth phase had stretched to 39 consecutive months as of July, well beyond the statistically estimated average duration of 27 months. "We are now in a phase where sluggish consumer spending and rising market rates are occurring at the same time," Yoon said. "Next year, card companies are likely to face simultaneous pressure on both their business operations and asset quality."
Seo Ji-yong, a professor in the business administration department at Sangmyung University, also warned that rising interest rates would erode card companies' profitability. Unlike banks, card companies cannot take deposits and rely instead on market borrowing — primarily through financial company bonds — to fund their operations. As a result, their funding costs rise quickly when market rates increase.
According to Seo, the yield on AA+-rated three-year financial company bonds climbed 1.06 percentage points, from 3.337% at the start of the year to 4.395% on Oct. 23 — more than double the 0.5-percentage-point benchmark interest rate increase over the same period. Of the approximately 5.24 trillion won ($3.94 billion) in financial company bonds maturing between late October and year-end, 55% fall due in December, adding to refinancing pressure.
The deeper problem is that card companies cannot easily pass higher funding costs on through card loan rates. Seo's analysis of data from seven dedicated card companies found that a 1-percentage-point rise in the benchmark interest rate pushes average funding costs up by 0.54 percentage points and card loan rates up by 0.58 percentage points. At the same time, the share of card loans in card company assets falls by 0.99 percentage points.
"Funding costs rise quickly and reliably for card companies, but the room to raise card loan rates may shrink further going forward," Seo said. "Legal interest rate ceilings and pressure to expand the supply of mid-rate loans make it structurally difficult to fully pass rising funding costs through to lending rates."
The outstanding balance of card loans fell for four consecutive months, from 43.25 trillion won at the end of May to 42.34 trillion won at the end of September. The balance edged back up to 42.67 trillion won at the end of October, rising 329.7 billion won from the previous month — the first increase in four months. The revolving payment balance rose for seven consecutive months, reaching 7.05 trillion won at the end of September.
"Borrowers who find it harder to access card loans are shifting to revolving credit or cash advance services — a balloon effect," Seo said. "Card loans, cash advances and revolving credit need to be managed in an integrated way at the borrower level, with more granular credit limits."
Seo also called for spreading out the maturities of financial company bonds, diversifying funding sources and strengthening loan-loss provisioning. Seo recommended that card companies reduce their dependence on card loans and build up fee-based revenue from credit card payments.
In opening remarks, Korean Credit Card Association Chairman Seo Ji-yong said, "Improving operational efficiency in the card industry is not simply a matter of cutting costs or growing assets. The choices made to protect near-term profits must not come at the expense of future competitiveness."
snsd@heraldcorp.com