Global shipments reach 779.9 GWh in first three quarters
Non-China regions account for 59.9%; North America grows 71%
LG Energy Solution up 355%, Samsung SDI up 46%
South Korean battery makers sharply expanded their share of the North American energy storage system (ESS) market this year. According to market research firm SNE Research, LG Energy Solution and Samsung SDI together held a combined 20.9% share in North America in the first three quarters of 2026, up from 13.4% in the same period last year.
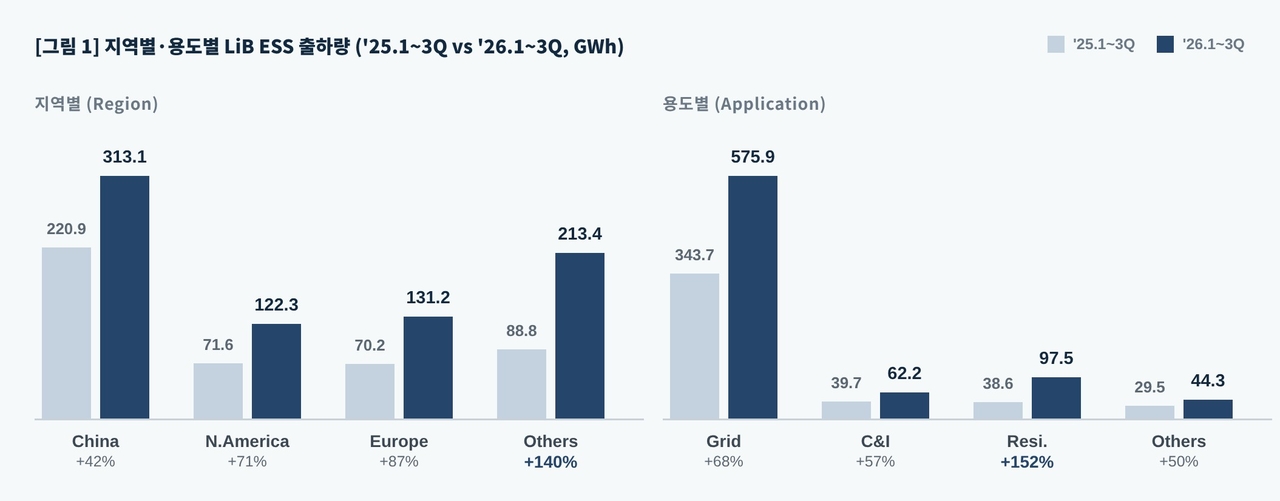
Global shipments of lithium-ion battery ESS reached 779.9 GWh in the first three quarters, a 73 percent increase from 451.5 GWh a year earlier, SNE Research said Thursday. Third-quarter shipments hit a quarterly record of 286.8 GWh, up 58 percent year on year.
China retained its position as the largest market, but shipments outside China reached 466.8 GWh, accounting for 59.9 percent of the global total — up from 57.3 percent in the first half. The North American ESS market grew 71 percent to 122.3 GWh.
In North America, LG Energy Solution shipped 18.4 GWh, lifting its market share from 4.8 percent to 15.0 percent and placing it third behind CATL (37.0 percent) and Hithium (16.5 percent). In the third quarter alone, LG Energy Solution shipped 8.1 GWh, surpassing Hithium's 7.1 GWh to rank second after CATL. North America accounted for 83 percent of LG Energy Solution's global shipments, with 96 percent of those North American volumes destined for grid-scale applications.
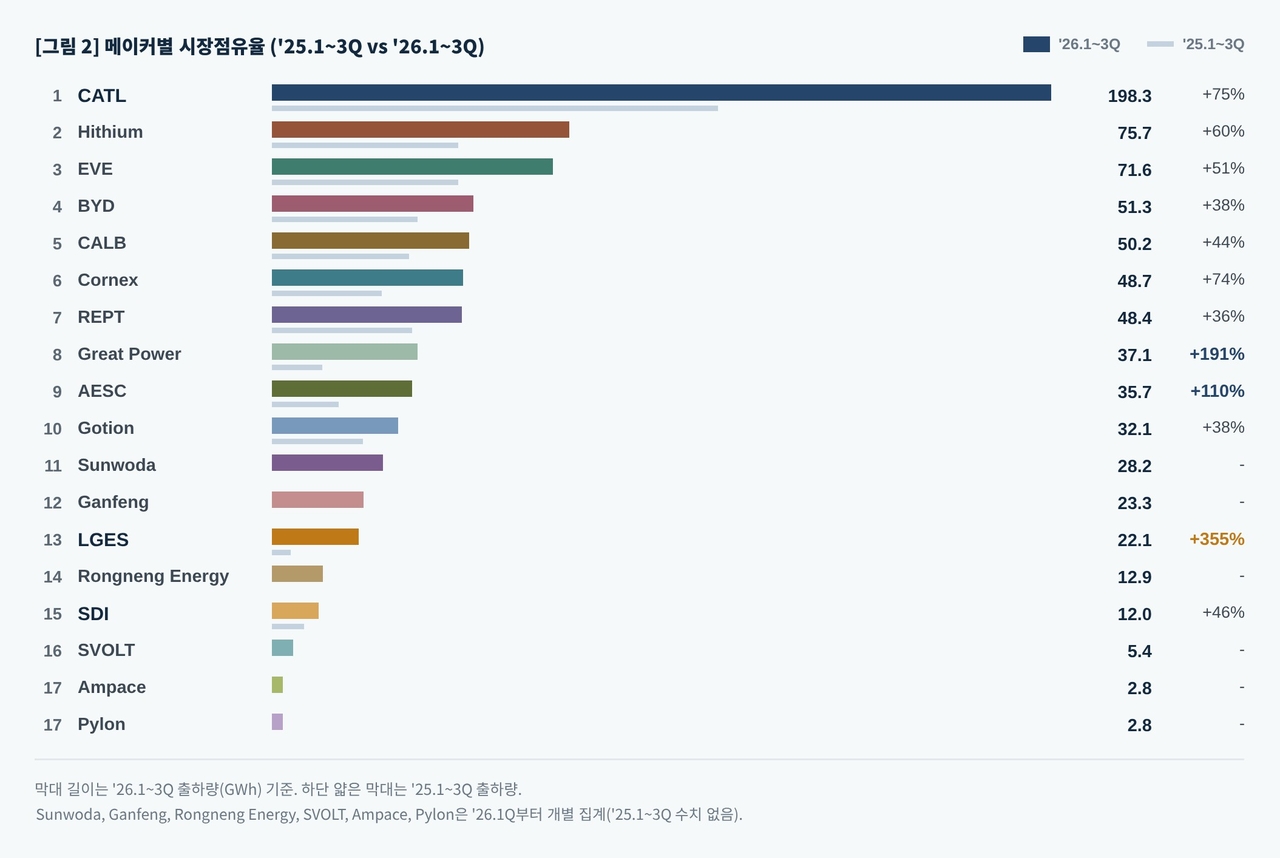
On a global basis, LG Energy Solution shipped 22.1 GWh in the first three quarters, a 355 percent increase, with its market share rising from 1.1 percent to 2.8 percent. Third-quarter shipments of 10.1 GWh were up 51 percent from the previous quarter, marking the first time the company surpassed 10 GWh in a single quarter.
Samsung SDI shipped 12.0 GWh globally, up 46 percent, and posted 5.6 GWh in the third quarter, a 70 percent jump from the prior quarter. In North America, the company shipped 7.1 GWh, a 17 percent gain, but that pace fell short of the broader market's growth rate, causing its regional share to slip from 8.6 percent to 5.8 percent. However, its supply for AI data centers in North America grew 68 percent, from 1.7 GWh to 2.8 GWh.
CATL led the global rankings with 198.3 GWh and a 25.4 percent share, followed by Hithium at 75.7 GWh and EVE at 71.6 GWh. China's combined share fell from 48.9 percent to 40.1 percent. LG Energy Solution and Samsung SDI together raised their global share from 2.9 percent to 4.4 percent, though that still trails the 44.3 percent combined share held by China's top three suppliers by a wide margin.
SNE Research said that as North America and Europe tighten tariffs and supply chain regulations on Chinese batteries, demand for suppliers with local production capacity is translating into actual shipments. The firm projected that Korean companies' market share could expand further once North American local production volumes and data center projects begin feeding into shipments in earnest.
eyre@heraldcorp.com