
Shifting standards for overseas financial account reporting
Seminar stresses importance of customer data management at insurers
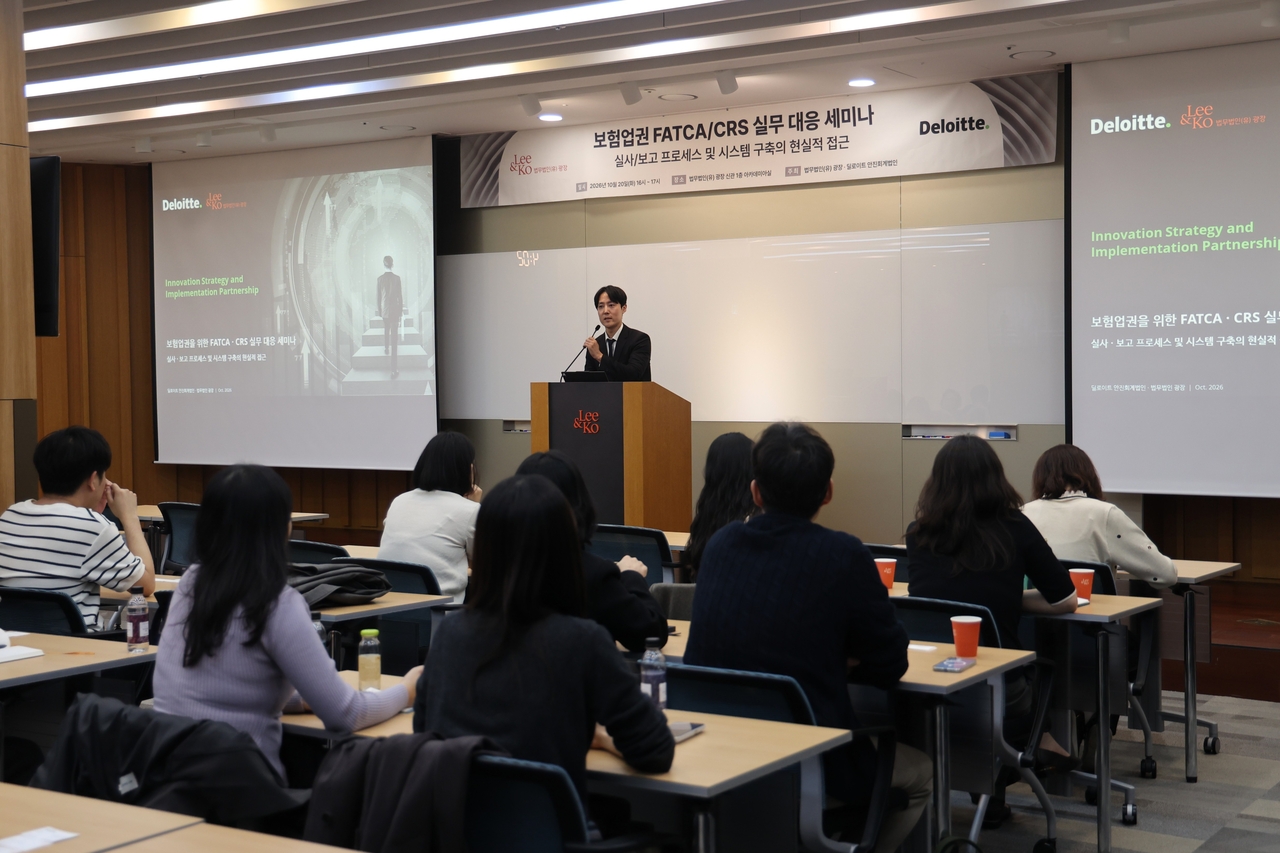
Law firm Lee & Ko announced Thursday that it recently co-hosted a seminar with Deloitte Anjin to discuss practical responses to international financial account information-exchange regimes, targeting professionals in the insurance industry.
The seminar was organized to help insurers assess what they need to prepare as cross-border financial account data-sharing requirements tighten. Particular focus was placed on managing information related to customers' overseas tax obligations and ensuring accurate reporting to tax authorities.
FATCA, the Foreign Account Tax Compliance Act, and CRS, the Common Reporting Standard, are regimes designed to prevent offshore tax evasion by facilitating the exchange of financial account information between countries. FATCA focuses on identifying overseas financial accounts held by US taxpayers, while CRS is an international standard for the regular exchange of financial account information among participating jurisdictions.
Upcoming changes to reporting and due-diligence requirements under a revised CRS have heightened the urgency for financial institutions to act. Key challenges for the insurance sector include determining which insurance contracts fall within the scope of reportable accounts and accurately managing customers' tax residency status and supporting documentation.
In the first session, Lee & Ko attorney Yoo Jeong-ho presented on recent National Tax Service trends and current practice related to FATCA and CRS. Yoo introduced the rollout of CRS 3.0 and the broader push to expand cross-border information exchange, and outlined areas where insurers should exercise caution in their day-to-day operations.
Key examples highlighted included determining reportability based on whether an insurance contract carries a cash value, handling contract terminations and dormant accounts, and managing documentation that establishes a customer's domestic residency. Yoo also said insurers should proactively review past reporting records and supporting materials in case tax authorities request explanations.
In the second session, Deloitte Anjin partner Seo Yeong-gyo presented on building due-diligence workflows and monitoring frameworks. Seo said financial institutions must strengthen verification systems to ensure that self-certification forms and supporting documents are managed systematically and that reportable customers are neither omitted nor reported with incorrect information.
A central message of the seminar was that financial institutions must go beyond simply submitting account information by set deadlines. Participants said firms need to review their end-to-end management systems — from customer identification and reportability classification to document retention and submission verification.
Meanwhile, Lee & Ko has provided FATCA and CRS consulting services across the domestic financial sector since FATCA was introduced in 2013. Working alongside the Deloitte team, the firm draws on experience accumulated across banking, insurance and securities to offer comprehensive advisory services covering regulatory interpretation, due-diligence processes, and the design and improvement of reporting frameworks.
Lee & Ko said it will continue to provide practice-oriented, specialized advisory support to help financial institutions respond effectively to the rapidly evolving international tax environment and ongoing regulatory changes related to FATCA and CRS.
arete@heraldcorp.com




