'Shinhan Super SOL Life Switching Savings Insurance' set for Monday release
Accumulated reserves used to pay riders for cancer, dementia coverage; exclusive-use rights applied for
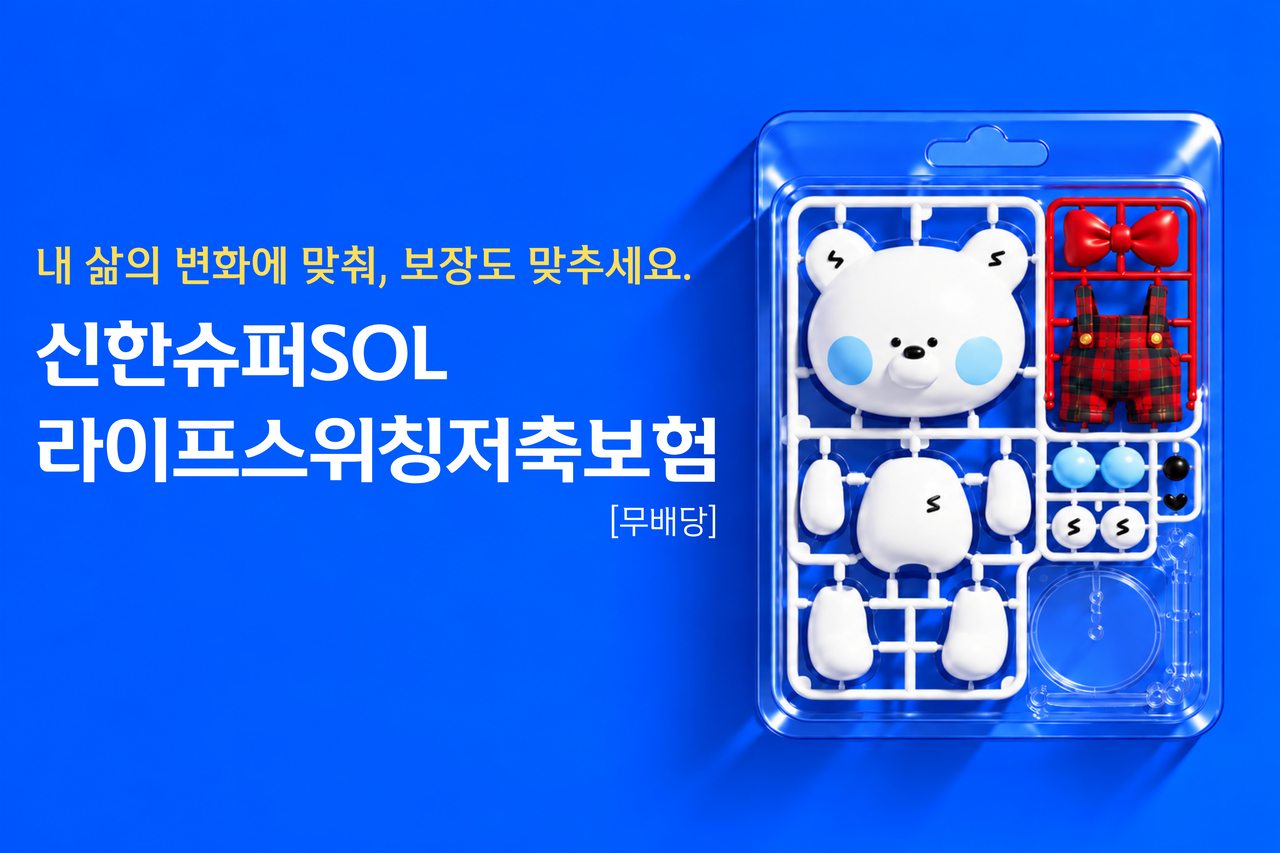
A new insurance product will allow policyholders to start with a savings plan and add health coverage whenever they need it.
Shinhan Life announced Wednesday it will launch the Shinhan Super SOL Life Switching Savings Insurance (non-dividend) on Monday. The product lets customers accumulate funds through a savings policy and then, at any point in their life cycle, add coverage for conditions such as cancer, cerebral hemorrhage, acute myocardial infarction, dementia and death. The company said the ability for customers to choose the type and amount of coverage, as well as when it takes effect, is an industry first.
The core feature is the "switching plan." Once a policyholder passes a single underwriting review at enrollment in the main contract, they can add riders without further review, subject to the product's conditions. Available coverage options include cancer, cerebral hemorrhage and acute myocardial infarction diagnoses; dementia; and death benefits.
Rider premiums are paid in a lump sum using a portion of the policyholder's reserve accumulated under the main contract. Customers can decide how much of their saved funds to allocate to each type of coverage and can stagger the start dates for different riders — for example, setting different effective dates for cancer and dementia coverage — to suit their circumstances.
Switching plan riders become available 10 years after the main contract is signed, and customers must apply at least two years before the desired start date. Each rider runs for a 10-year term, with renewal eligibility and age limits determined by the individual rider's terms.
The product is available through the Shinhan Super SOL app and comes in two types: a savings-only option (Type 1) and a life-switching option (Type 2) that incorporates the switching plan feature. The main contract is structured with a maturity age of 100 and a 20-year premium payment period.
Shinhan Life set up a dedicated innovation TF in the first half of this year to develop the product, bringing together teams covering product design, underwriting, claims payment, consumer protection, risk management and digital systems. The company also applied for exclusive-use rights this month.
"We designed this product so customers can build up funds for the future and then choose the coverage they need as their lives change," a Shinhan Life official said. "We will continue to introduce new products and services that expand the ways customers can make use of insurance."
Meanwhile, Shinhan Life has been moving quickly to secure exclusive-use rights as part of its product differentiation strategy. Its Shinhan Tontine Pension Insurance, launched in January as an industry first, was granted 12 months of exclusive-use rights by the Korea Life Insurance Association's new product review committee.
won@heraldcorp.com