October rate hike forecasts retreat rapidly
Global brokerages see one more move in December
Kashkari projects one hike this year, one next
Strong economy keeps door open to higher rates
The questions markets are asking about US interest rates are changing. When the Federal Reserve resumed rate hikes in September for the first time in three years and two months, attention centered on whether it would raise rates again in October. But after a string of signals from senior Fed officials urging a slower pace, expectations for a hike this month have retreated quickly.
Instead, market attention is shifting from the "pace" of tightening to its "ceiling." Even if the Fed pauses in October, if the US economy continues to absorb high rates better than expected and inflation proves stubborn, the central bank may need to push rates higher in this tightening cycle than originally anticipated.
Major global brokerages are now leaning toward a scenario in which the Fed holds rates at the Oct. 27–28 Federal Open Market Committee meeting before delivering one additional hike in December, according to Reuters on Thursday.
The mood was quite different just weeks ago. The Fed raised its benchmark interest rate by 25 basis points in September, lifting it from 3.50–3.75 percent to 3.75–4.00 percent — the first increase since July 2023. Fed officials' own rate projections pointed to one more hike within the year. But after energy prices surged following the outbreak of the Iran war and inflation pressures re-emerged, financial markets ran ahead of the Fed's own forecasts, rapidly pricing in the possibility of back-to-back hikes in September and October.
Then the Fed began signaling that markets were getting ahead of themselves.
New York Fed President John Williams said Tuesday that "there is no need to be in a hurry to change the current monetary policy stance." Williams also serves as vice chair of the FOMC, the Fed's rate-setting body. Fed Vice Chair Philip Jefferson added Thursday that future policy adjustments should be determined by "carefully examining the trend in data, the evolving outlook, and the balance of risks," and that more time "may be needed" to make that judgment.
With two of the Fed's most influential officials delivering the same message in quick succession, markets rapidly unwound bets on an October hike.
Evercore ISI, the research arm of investment bank Evercore, said Vice Chair Jefferson "confirmed the message from President Williams," adding that it "does not expect the Fed to deliver a consecutive rate hike at the October meeting and that it will take more time to assess the evolving economic situation." Tim Duy, chief US economist at SGH Macro Advisors, a macroeconomic research firm, said Williams' unusually clear message came because "market pricing of rate hike expectations had run too far away from the Fed."
Pace slows, but the rate ceiling may still rise
A lower probability of an October hike does not mean the Fed's resolve to tighten has weakened. If anything, a simultaneous message is emerging from within the Fed: there is no need to raise rates immediately, but how high they ultimately need to go remains an open question.
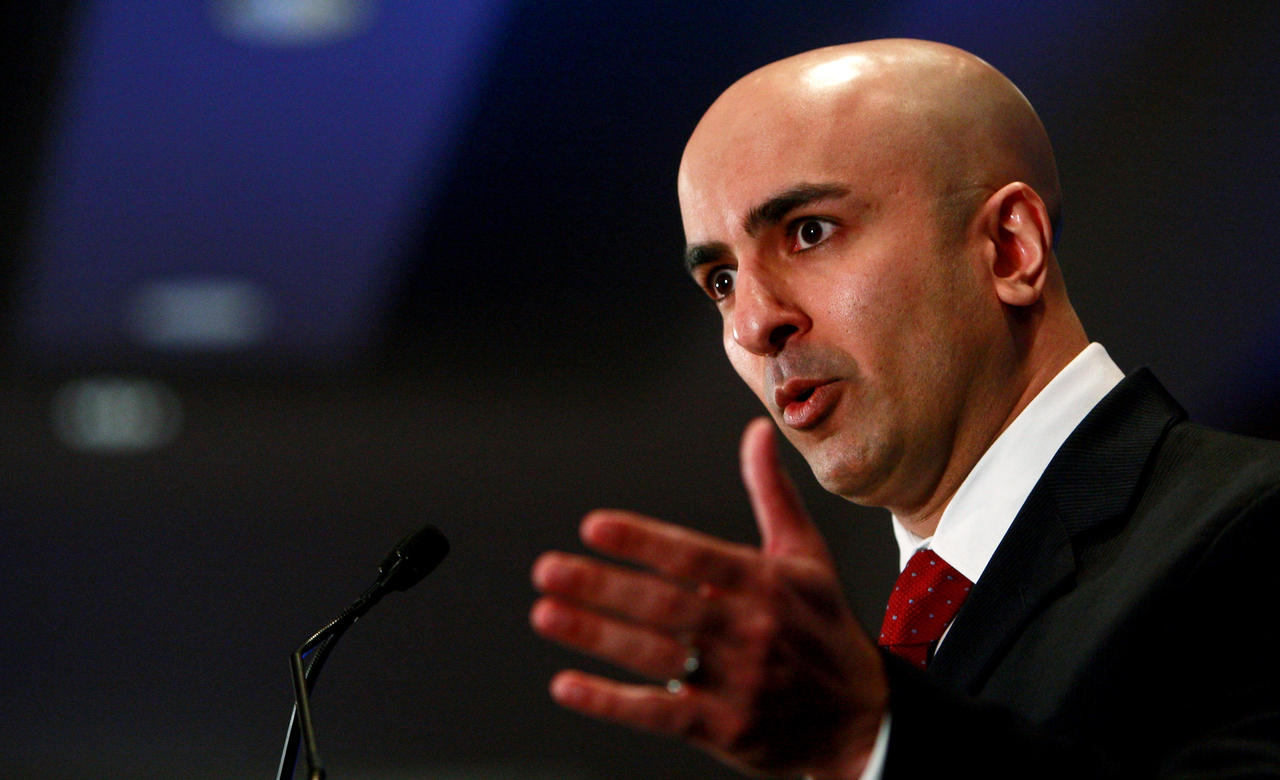
Minneapolis Fed President Neel Kashkari put it most plainly. In an interview with Reuters on Thursday, he said he had "an open mind" on whether to hike in October and held "no strong view" on the matter. The implication was that he saw no compelling reason to insist on an October move.
And yet, he said his own projections include one additional rate hike this year and one more next year. Pausing in October and ending the tightening cycle are, he made clear, entirely different things.
More notable was his assessment of the US economy. Kashkari said the economy had shown more resilience since the September FOMC meeting than he had expected. "If the economy is incredibly resilient and as a result inflation is stickier than I'm expecting, then the policy rate may need to go higher than I'm currently projecting," he said.
He also questioned whether the current benchmark rate is sufficiently restraining the economy, suggesting — based on strong employment and growth — that current monetary policy may "not be especially restrictive."
That is a significant point for the Fed. If consumer spending, employment and investment remain resilient even after rates have been pushed to 3.75–4.00 percent, the current level of rates may not be as high in real terms as assumed.
The goal of monetary policy is not to raise rates for their own sake, but to use higher rates to suppress demand and bring down prices. If the economy is weathering high rates better than expected, the rate level needed to achieve the same tightening effect may also need to be higher.
Recent economic data are deepening that dilemma.
The August personal consumption expenditures price index came in below market expectations, suggesting some easing of inflation pressures — reducing the urgency for the Fed to raise rates quickly in the near term.
Growth indicators, however, came in stronger than expected. The Commerce Department's final estimate for second-quarter GDP growth was revised up to an annualized 2.2 percent from a prior reading of 1.5 percent, a 0.7 percentage point upward revision. The personal consumption growth rate was also raised, from 3.4 percent to 3.8 percent.
Business investment — driven by AI data centers, semiconductors and power infrastructure — is also underpinning the US economy, a trend that runs counter to earlier expectations that high rates would cool the economy quickly.
Vice Chair Jefferson said he expects inflation to continue declining toward the Fed's 2 percent target, but assessed that the risks to the inflation outlook remain "tilted to the upside," citing geopolitical shocks and stronger-than-expected aggregate demand.
Therein lies the Fed's dilemma. Because inflation is running lower than feared, there is less urgency to raise rates again immediately in October. But because the economy is stronger than expected, it is equally difficult to declare the tightening cycle over.
If the economy's tolerance for high rates proves greater than anticipated, the terminal rate — the level at which the Fed ultimately stops — could end up higher than currently projected. That is why market attention is shifting from "October or December" to "how high will rates ultimately go."
For now, the most likely path appears to be: a hold this month following last month's hike, then one more increase in December. But even that is no guarantee of where tightening ends.
Kashkari has already built one additional hike next year into his baseline forecast. If growth and employment stay strong and inflation remains stickier than expected, rates could go "higher than I'm currently projecting," as he put it.
Conversely, if the economy and labor market slow sharply, the Fed could stop hiking altogether. The Fed's reluctance to rush an October decision also reads as an effort to buy time to assess that uncertainty.
Meanwhile, the latest jobs data appear to have given the Fed room to pause. The Labor Department reported Friday (local time) that the US economy added 29,000 nonfarm payroll jobs in September, far below the market consensus of 84,000. Employment figures for July and August were also revised downward, pointing to a broader cooling in the labor market. The unemployment rate edged up to 4.2 percent last month.
Phil Blancato, chief market strategist at asset management firm Osaic, called the numbers "exactly what the market wanted from a labor perspective" — "not too hot, not too cold, not too strong, not weakening."
The weaker-than-expected jobs report raised the probability that the Fed will pause at this month's FOMC meeting. Markets put the odds of a rate hold at 77.9 percent Sunday afternoon, up from 75.6 percent on Saturday.
Still, reading the Fed's signals as a whole, it is important to distinguish between "slowing the pace" and "ending tightening." Holding rates steady in October is better understood as a move to assess the effects of September's hike and gather more data.
If the US economy continues to absorb high rates in the meantime, the Fed faces a harder question — not whether to delay the next hike by a month, but how much higher rates ultimately need to go to actually cool the economy. That has become the central variable in the next phase of monetary policy.
Debriefing: The Herald Business international desk breaks down the untold stories behind the hottest global issues. Leave your questions in the comments — we read them all.
sjy@heraldcorp.com