FSS holds forum on cleaning up insurance broadcast advertising
Broadcast ad volume up 66.9% in a year
Misselling rate three times higher than other channels
Home shopping sanctioned just once in five years
FSS calls for lower penalty thresholds, broader disclosure
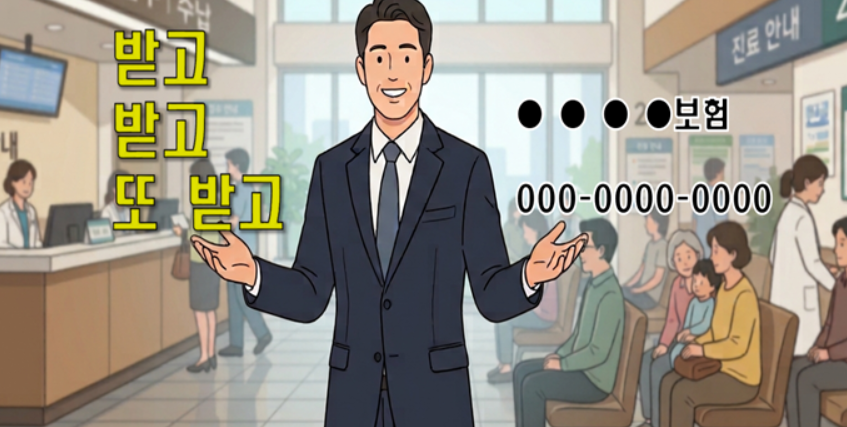
"My mom isn't home." Over footage evoking a sick mother's absence, an insurance enrollment pitch plays on.
"Get paid, and paid, and paid again" — the ad hammers home the promise of multiple payouts, yet never once says how many times a policyholder can actually collect.
These are among the cases the Financial Supervisory Service has singled out as prime examples of insurance broadcast advertising that misleads consumers and stokes anxiety.
Financial regulators have decided to crack down on insurance product broadcast advertisements that exploit consumer fears. Their concern: policies sold through broadcast ads carry a misselling rate three times that of other distribution channels, and a disproportionately high share of elderly policyholders.
The FSS said Thursday it convened a forum on "improving the integrity of insurance product broadcast advertising," gathering compliance officers from 13 companies — including insurers and home shopping general agencies (GAs) — alongside the Korea Life Insurance Association and the General Insurance Association of Korea. The forum is part of the regulator's financial consumer protection improvement roadmap.
Kim Uk-bae, FSS deputy governor for consumer protection, said in opening remarks that "despite self-regulatory frameworks put in place by the insurance industry to stamp out false and exaggerated advertising, there remains a persistent tendency to repeatedly air overly provocative ads that nudge consumers into impulsive purchases." He added that "policies taken out in response to sensationalist broadcast ads show markedly higher rates of elderly policyholders and misselling, indicating that old sales practices have not gone away."
Kim called on the industry to pursue three goals: establishing effective self-regulation, improving transparency in broadcast advertising information, and strengthening internal controls at insurers and GAs. He particularly emphasized that insurers' own review processes serve as "the first line of defense against false and exaggerated advertising" and urged them to tighten those reviews.
According to the FSS, insurance product broadcast ads aired an average of 1,121 times a day last year, totaling 57 hours of airtime daily — up 66.9% in volume from 2024, when ads ran 672 times a day for 35 hours.
The surge in advertising has amplified consumer protection concerns. The misselling rate for policies sold through broadcast ads last year was 0.036%, three times the 0.012% recorded for other distribution channels. The 13th-month policy retention rate stood at 79.3%, seven percentage points below the 86.3% seen in other channels. Policyholders aged 70 and older accounted for 13.4% of broadcast-channel customers, roughly 1.8 times the 7.4% share in other channels — a sign that vulnerable groups are being disproportionately exposed to provocative advertising.
The FSS also released examples of misleading ads. Some promoted multiple payouts with slogans like "get paid, and paid, and paid again" while burying the total payout limit in fine print, or displayed phrases such as "cancer treatment costs paid every time you receive treatment each year" in bold while rendering the restriction "covered only once per year" in thin, faint text. Ads depicting family caregiving and grief — including the "my mom isn't home" spot — alongside reenactments of traffic accidents and X-ray images of diseases were also flagged as examples of "fear marketing."
Participants noted that sanctions against home shopping ads have been largely ineffective. Because home shopping insurance ads air live, pre-broadcast review is not possible, leaving industry associations to conduct post-broadcast reviews. Under the current framework, however, corrective action can be deferred up to four times per quarter before a sanction is imposed, and the misselling rate threshold that triggers a one-month recorded-broadcast sanction — exceeding 0.4% over a half-year period — is far above the industry average of 0.03%. As a result, only one warning has been issued over the past five years.
Association disclosure records bear this out. The Korea Life Insurance Association issued a warning to CJ ENM's home shopping sales broadcast — for a Lina Life dental insurance product — in February this year, but the cited reason was "failure to comply with prize announcement time requirements," not the fear marketing or suppressed payout-restriction disclosures the FSS has flagged as problematic. All five sanctions disclosed by the General Insurance Association of Korea this year involved banner or GA business advertisements; not one concerned a home shopping broadcast.
In response, regulators and the industry agreed to rationalize the sanction deferral system and lower the misselling rate threshold for sanctions to better reflect the home shopping average. The associations plan to refine their review standards and continue circulating examples of non-compliant ads across the industry.
Disclosure requirements will also be expanded. Associations currently publish only the fact of sanctions related to broadcast advertising. Going forward, they plan to develop industry-wide voluntary disclosure standards — subject to public consultation — covering the number and duration of broadcast airings by insurer and the status of associations' ad reviews. Insurers and GAs will also explore ways to make their internal review processes more substantive, including direct involvement of consumer protection departments from the ad production stage.
Attendees expressed agreement on the need to strengthen broadcast advertising disclosure and tighten regulation, and said they would move quickly to develop voluntary improvement measures. An FSS official said the regulator would "actively support the industry's efforts to draw up concrete implementation plans and carry out self-correction at pace," adding that it would "step up broadcast advertising monitoring in cooperation with the associations."
won@heraldcorp.com