'2026 KIDI Insurance Future Forum' held in Seoul
'Demographics, biotech and AI are reshaping insurance'
Global speakers from Microsoft, CUHK and others participate
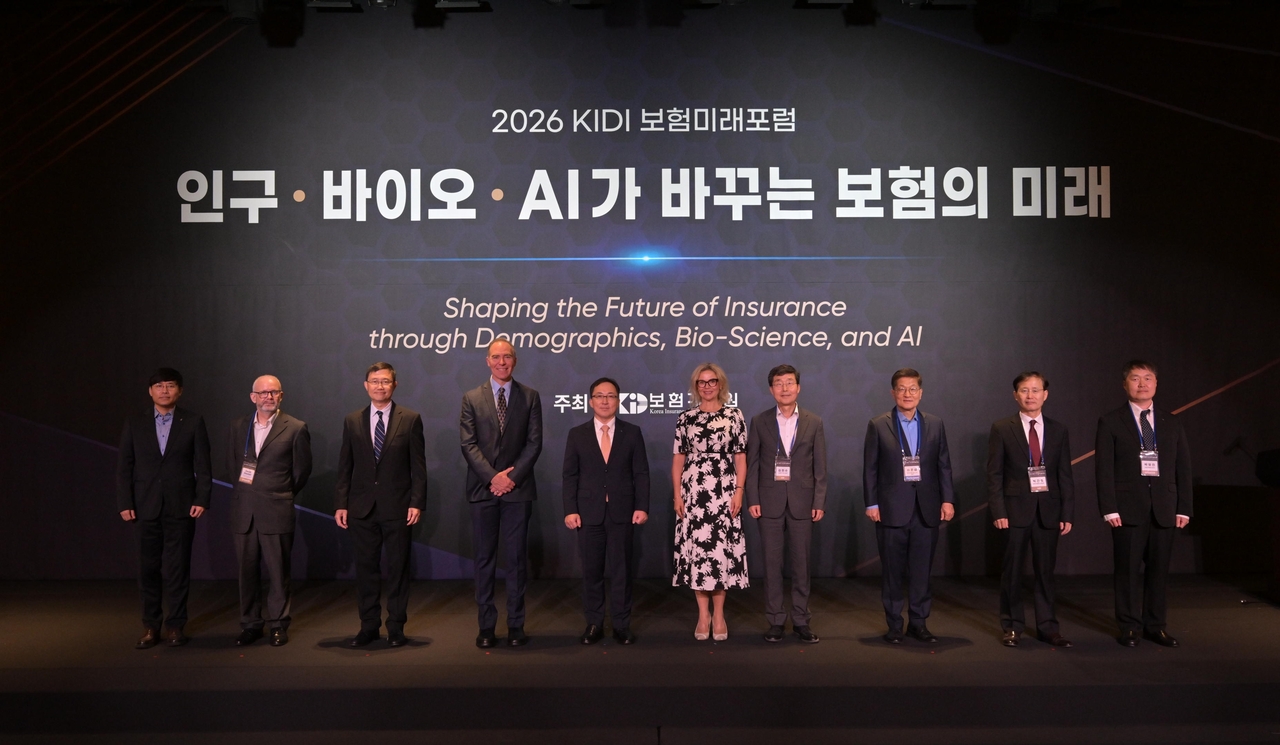
South Korea's insurance industry has reached a "singularity" — a tipping point at which simultaneous shifts in demographics, biotechnology and AI are upending the sector's very foundations, industry experts said Wednesday. Rather than simply paying out claims after accidents occur, insurers must rebuild their decades of accumulated data and expertise as the bedrock of a new AI-era business model, they argued.
The Korea Insurance Development Institute held the 2026 KIDI Insurance Future Forum at FKI Tower in Yeouido, Seoul, under the theme "The Future of Insurance Reshaped by Demographics, Biotech and AI." Now in its sixth year, the forum drew global speakers from Microsoft and Boston Dynamics, among others. Seong Won-myeong, a senior official at the institute who delivered the opening presentation, defined the industry's singularity as "technology redefining the nature of risk and transforming the very role of insurance." He identified three forces driving the change: demographic shifts, biotechnology and AI.
Citing Ministry of Statistics data, Seong said the share of South Koreans aged 65 or older will rise to 40.1 percent by 2050, while the working-age population between 15 and 64 will shrink by more than 10 million. "If the pool of new customers is shrinking, growth through volume alone becomes difficult," he said. "Insurers need to pursue quality over quantity — through senior care, lifelong management and similar services."
Biotechnology, Seong said, threatens to upend the very benchmarks used to set premiums. As genetic, blood and sleep data enable earlier disease detection, and as "digital twin" technology — which creates a virtual replica of a person's body to test drug efficacy — becomes more widespread, insurers will be able to move beyond actuarial tables based on population averages and tailor assessments to individuals. "Insurance will shift away from paying out only after illness strikes, toward early intervention and prevention," he said.
The forum also heard that while the spread of AI should reduce accidents caused by human error, it will create new categories of risk that insurers must prepare for. Agentic AI systems that set and pursue their own goals, along with physical AI applications such as robots and self-driving cars, will amplify risks stemming from software failures, cyberattacks and communication outages. "When a self-driving car is involved in an accident, who bears responsibility — the driver, the manufacturer or the software developer?" Seong asked, saying insurers will need the capability to assess not just human negligence but also systemic failures. On agentic AI, he said governance questions — "how much autonomy to grant AI and when to intervene" — remain unresolved, adding that "companies that strike the right balance between humans and AI will be the winners."
The distribution landscape will also be transformed, Seong said. As personal AI agents begin comparing insurance products and executing contracts on behalf of customers, the traditional intermediary roles of agents and brokers will diminish. Insurers that once competed on brand advertising and the size of their sales forces will instead find themselves "competing to win AI recommendations," he said. The scope of partnerships will also broaden: companies that prepare to join open network ecosystems alongside financial platforms, AI firms and data centers will be the ones that survive.
While relying on historical statistics and population averages has its limits, Seong said the accident, claims and underwriting data that insurers have accumulated over decades — along with their risk-assessment models — remain powerful assets in the AI era. He called for combining insurer data with AI-driven analysis of telematics records such as mileage, hard acceleration and sudden braking in auto insurance, as well as weather and building-age data in property insurance. "Rather than trying to predict the future perfectly, what matters is identifying new risks first and turning them into new insurance value," he said.
Park Young-jin, who leads the new-growth support team at the Korea Insurance Development Institute, framed AI as both an opportunity and a risk for insurers. AI-related incidents — such as malfunctions or deepfake fraud — represent new markets that insurers can move to cover. "Overseas, products have already emerged that cover losses from AI performance degradation and that partially replace the income of workers who lose their jobs to AI," Park said. He added that Samsung Fire launched a dedicated self-driving car insurance product in May covering manufacturer liability and hacking damage.
Conversely, insurers that misuse AI expose themselves to serious liability. US insurer State Farm faced a lawsuit alleging its AI claims-review system discriminated against certain racial groups — and could not explain how the AI had reached its decisions. Cigna drew scrutiny after rejecting more than 300,000 claims over two months at an average of 1.2 seconds per claim, raising allegations that the decisions were made by AI rather than humans. Citing these cases, Park advised that insurers should explain AI decisions in terms customers can understand, ensure that humans conduct final reviews of significant decisions, and clearly disclose how customer data is being used. "The priority must be the capability to deploy AI in a controllable manner, ahead of the level of technology or the speed of adoption," he said.
Benny Zee, a professor at the Chinese University of Hong Kong's medical faculty, presented AI technology that can estimate a patient's risk of stroke, dementia and diabetes within minutes from a single retinal photograph. During the question-and-answer session, Korea Insurance Development Institute President Yoo Jae-hoon asked whether the technology could also identify links to criminal behavior. Zee said it could be used to classify autism spectrum disorder, but added that it "would not be easy to use as courtroom evidence."
In his opening remarks, Yoo said the insurance industry must reinvent itself as an "integrated risk manager" that uses advanced technology to predict, prevent and manage risk.
won@heraldcorp.com