Operating profit at top 20 global automakers falls 63%
Average EBIT margin drops to 3.5% in first half of this year
Electrification costs, Chinese competition and tariffs weigh
Hyundai Motor, Toyota hold up relatively well
Global automakers sold more vehicles last year but saw their profits shrink sharply, a new report shows. Ongoing investment in electric vehicles, software and AI, combined with rising supply from Chinese manufacturers and mounting tariff burdens, has created a structural disconnect between sales recovery and profitability improvement.
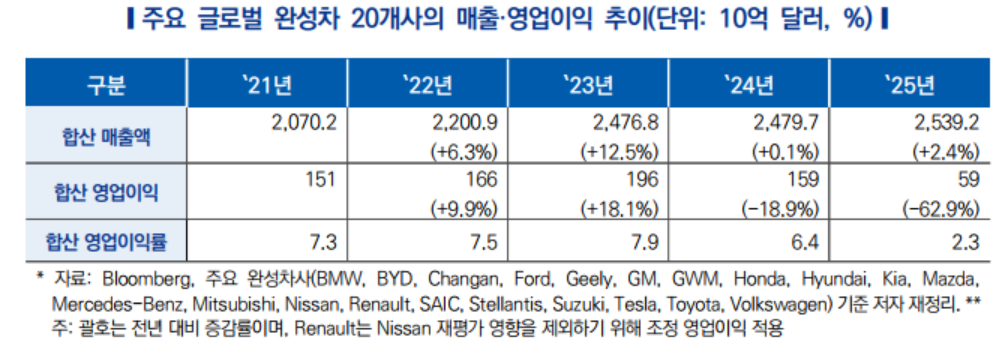
Combined sales at the world's 20 major automakers reached $2.54 trillion last year, up 2.4% from the previous year, according to a report released Tuesday by the Korea Automobile Research Institute titled "Changes in Automaker Profitability and Their Implications." Operating profit, however, plunged 62.9% — from $159 billion to $59 billion. The combined operating profit margin fell from 7.9% in 2023 to 6.4% in 2024 and further to 2.3% last year.
The situation has shown little improvement this year. An analysis of first-half earnings at 25 global automakers by Germany's Center of Automotive Management found that revenue slipped 1.0% from a year earlier while earnings before interest and taxes fell 16.3%. The average EBIT margin dropped from 4.4% to 3.5%, and EBIT per vehicle sold declined 14.3% — from 1,199 euros ($1,360) to 1,027 euros.
A decline in automaker profitability is not itself a new phenomenon. Given the industry's heavy fixed costs — large factories and substantial research and development spending — profit margins tend to fluctuate significantly with sales volumes and plant utilization rates.
Between 2021 and 2023, a global semiconductor shortage constrained new vehicle supply, reducing the need for discounts and prompting automakers to focus production on higher-priced, higher-margin models. Because profitability during that period was unusually elevated, some of the subsequent margin decline can be seen as a normalization, the report noted.
Last year, however, global vehicle sales and production both increased, yet profitability fell sharply at a significant number of automakers — a trend the institute said cannot be explained simply as normalization.
One of the heaviest burdens is a prolonged electrification transition. With demand for battery electric vehicles varying widely by region, automakers must continue supporting internal combustion engine and hybrid lineups while simultaneously investing in EV platforms, batteries and production facilities.
When EV demand falls short of expectations, utilization rates at already-built factories drop. Conversely, retooling a production line to respond to shifting demand requires between $200 million and $400 million per model and takes nine to 15 months, the report found. The need to sustain both legacy and electric vehicle operations at the same time means the investment burden could persist for years.
Software and AI represent another growing cost. Development spending on advanced driver-assistance systems, software-defined vehicles and AI is rising, but the pace at which these investments translate into actual revenue remains slow. Some 94 percent of Western automakers said they had monetized fewer than half of their software-defined vehicle features. Even after a vehicle is sold, costs continue to accumulate through software updates, cybersecurity maintenance and cloud operations.
Chinese automakers are also intensifying their push overseas. In the first half of this year, Chinese automaker sales in Europe surged roughly 65%, lifting their market share from 7% to 11%. Combined revenue at five Chinese manufacturers — BYD, Geely, SAIC, Changan and GWM — grew 71%, from $178 billion in 2019 to $305.1 billion last year. Their operating profit margins, however, remain in the 2% to 4% range, suggesting the companies are accepting thin returns in exchange for expanding supply.
Tariffs and the push to localize production are adding to cost pressures. US import tariffs on vehicles and EU countervailing duties on Chinese-made electric vehicles have made it increasingly difficult for automakers to rely on a single global production and procurement network as they once did. Building separate manufacturing and supply chains for North America, Europe and China is driving up fixed costs across the industry.
Volkswagen Group has responded to its deteriorating profitability with a sweeping restructuring that includes cutting staff and trimming its model lineup. Excess production capacity in Europe, weak sales in China and the combined weight of electrification and software investment pushed its first-half operating profit margin this year to 3.8% — roughly half the 7.9% it recorded in 2022.
Divergence among automakers is also widening. Suzuki, which derives a large share of its business from emerging markets such as India, maintained a strong operating profit margin of 10.1% in the first half of this year. Hyundai Motor Group and Toyota also benefited from offering multiple powertrain options — including hybrids alongside electric vehicles — which helped defend their margins. By contrast, some Japanese automakers with heavy exposure to the US market and export-dependent business models were hit relatively hard by tariffs.
"Going forward, the key will not be simply recovering profitability to past levels, but rather sustaining future investment on the back of existing business earnings and executing on the ability to translate that investment into actual sales and profit," said Kim Han-sol, a senior researcher at the Korea Automobile Research Institute. "There is also a need to reduce duplicated investment through co-development and standardization, and to concentrate in-house development resources on areas where differentiation truly matters."
kwater@heraldcorp.com