ISSA 5000 under the microscope
Compared with ISO, AccountAbility standards
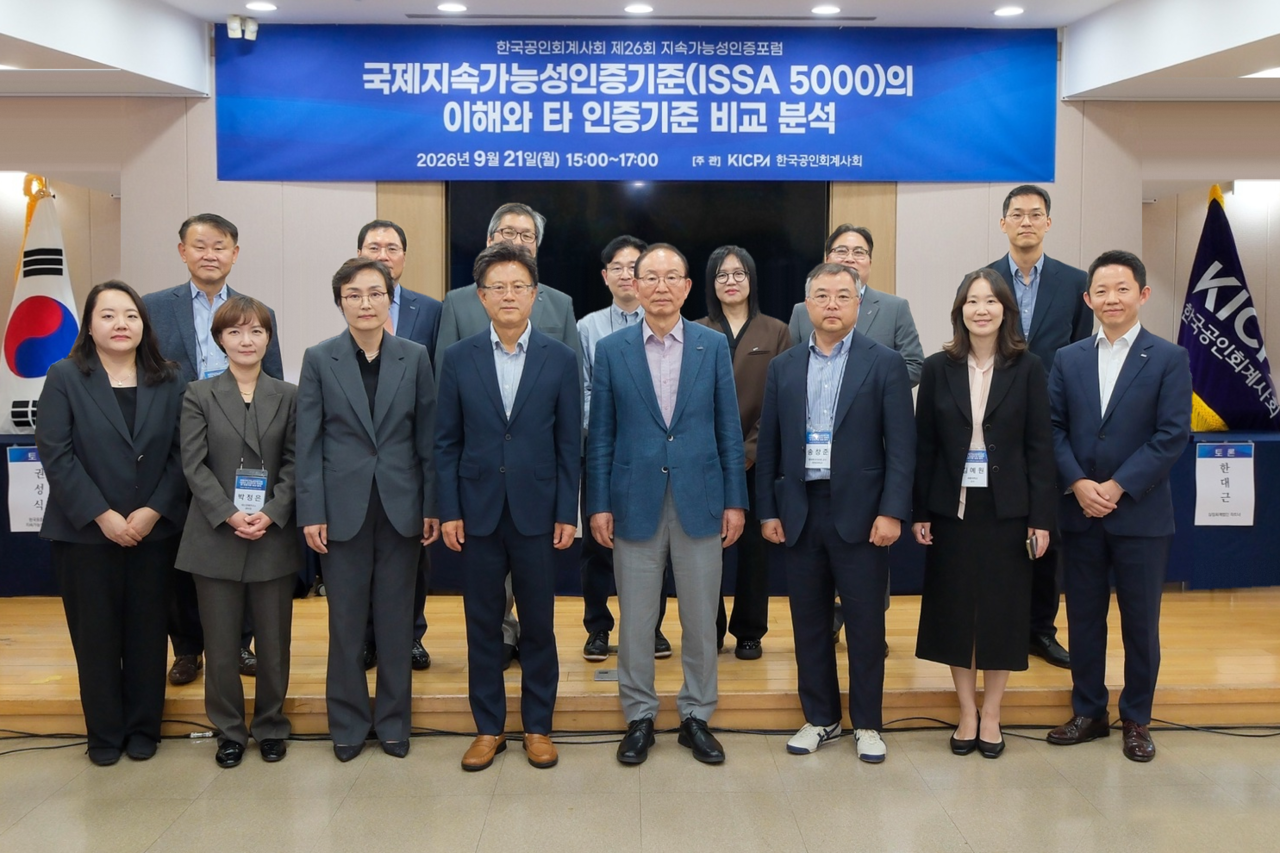
The Korean Institute of Certified Public Accountants held its 26th Sustainability Assurance Forum as a webinar Sunday, the organization announced Monday. The forum, themed "Understanding the International Standard on Sustainability Assurance (ISSA 5000) and a Comparative Analysis with Other Assurance Standards," drew participants from academia, industry and assurance bodies.
The institute has hosted the Sustainability Assurance Forum since 2022 to promote transparency and reliability in sustainability reporting. This edition focused on ISSA 5000, issued by the International Auditing and Assurance Standards Board, and compared it with ISO 14019 from the ISO and AA1000AS from AccountAbility, a London-based international organization.
Interest in internationally developed disclosure standards has grown since the Financial Services Commission mandated sustainability disclosures for Kospi-listed companies with consolidated assets of 10 trillion won ($7.4 billion) or more, effective 2028. The requirement will expand to companies with assets of 5 trillion won or more in 2029, and the commission plans to assess two years of disclosure practice before deciding whether to extend the mandate to companies with assets of 2 trillion won or more in 2030.
In his opening remarks, Chairman Choi Un-yeol said assurance standards are the cornerstone of high-quality assurance work. "ISSA 5000, which has received the endorsement of the International Organization of Securities Commissions, is designed to be used by all assurance practitioners regardless of profession, grounded in ethics, independence and quality management," he said. "I hope this forum deepens understanding of the standard and helps chart a concrete direction for the development of the domestic assurance regime."
Kim Beom-jun, a professor at the Catholic University of Korea, delivered the first presentation, comparing the background, purpose and practitioner requirements of each standard and sharing interview findings from both accounting-firm and non-accounting-firm assurance providers. "Given that IOSCO has recommended that its review of assurance regimes consider the application or incorporation of ISSA 5000, the standard is likely to establish itself as the primary assurance benchmark going forward," Kim said.
Kim Ye-won, a professor at Sejong University, delivered the second presentation, comparing detailed elements including practitioner responsibilities and roles, performance procedures, and criteria for forming assurance conclusions. "ISSA 5000 draws specific connections from the allocation of responsibility through the determination of procedures to the formation of conclusions," she said. "ISO 14019 delegates many specifics to separate verification programs, while AA1000AS has relatively limited provisions on concrete performance methods."
The panel discussion was moderated by Baek Tae-young, an emeritus professor at Sungkyunkwan University. Participants representing assurance bodies, academia, investors, corporations, standard-setting organizations and the accounting profession shared their views.
Kwon Seong-sik, head of the sustainability center at the Korean Standards Association, said ISSA 5000 has strengths in procedural precision — including quality management responsibilities, materiality judgments and the formation of conclusions on misstatements. "The institution-level accreditation system under ISO 14019 can help ensure cross-border consistency," he added. "AA1000AS, with its emphasis on practitioners' understanding of sustainability principles and individual qualification requirements, can make a positive contribution to Korea's nascent assurance market."
Kwon Se-won, a professor at Ewha Womans University, said that for new assurance standards to take root in practice, the experience of existing assurance bodies must be combined with the accounting profession's capacity for quality management and independence. "There is a need to establish a consultative body that brings together diverse assurance providers to share experience and expertise, and to raise awareness of sustainability assurance," she said.
Voices from the corporate side called for faster progress in the discussions. Shim Jeong-eun, a senior managing director at HD Korea Shipbuilding & Offshore Engineering, said predictability in assurance procedures and reliability in disclosed information are critical from a company's perspective. "We need to accelerate discussions on the international acceptance and mutual recognition of domestic assurance outcomes, develop specific criteria covering forward-looking information, financial impacts and materiality judgments, and build a reliable information infrastructure in line with disclosure preparation timelines," she said.
Han Dae-geun, a partner at Samjong KPMG, said standards that allow different practitioners facing similar circumstances to arrive at similar procedures and conclusions are essential. "We need specific guidance on group-level assurance for consolidated disclosures, the use of component practitioners and internal and external experts, and the use of existing greenhouse gas verification results," he said. "International acceptance must also be secured to reduce the burden of duplicative assurance on companies."
park.jiyeong@heraldcorp.com