Second blind fund to close in November with commitments near 800 billion won — four times the first fund
Housing management and elevator maintenance markets targeted for roll-up strategy
Some buy, some sell, and others reload for the next deal. Even in the same mergers and acquisitions market, private equity fund managers differ widely in strategy and results. [House Review] takes a close look at where major managers invested this year, what they achieved, and where they are looking next. [Editor's note]
Genesis Private Equity, a private equity fund manager, marks its 10th anniversary this year. Capital markets have gone through turbulent cycles over that decade, but the firm stayed the course — quietly repeating what it does best. It has carried the "success formula" proven in waste management platforms into the housing management and elevator maintenance markets, continuing its value-enhancement work. It is also acquiring semiconductor materials, components and equipment companies as it sketches out yet another platform.
The market's view of the firm has shifted. Limited partners responded enthusiastically to Genesis PE's fundraising for its second blind fund. The blind fund it launched in 2024 at 200 billion won ($147 million) has grown fourfold in about two years. The market rewarded with trust what it saw: a firm that invests according to firm, consistent criteria as an energy, environment and infrastructure private equity fund manager.
From waste to housing: building the next platform
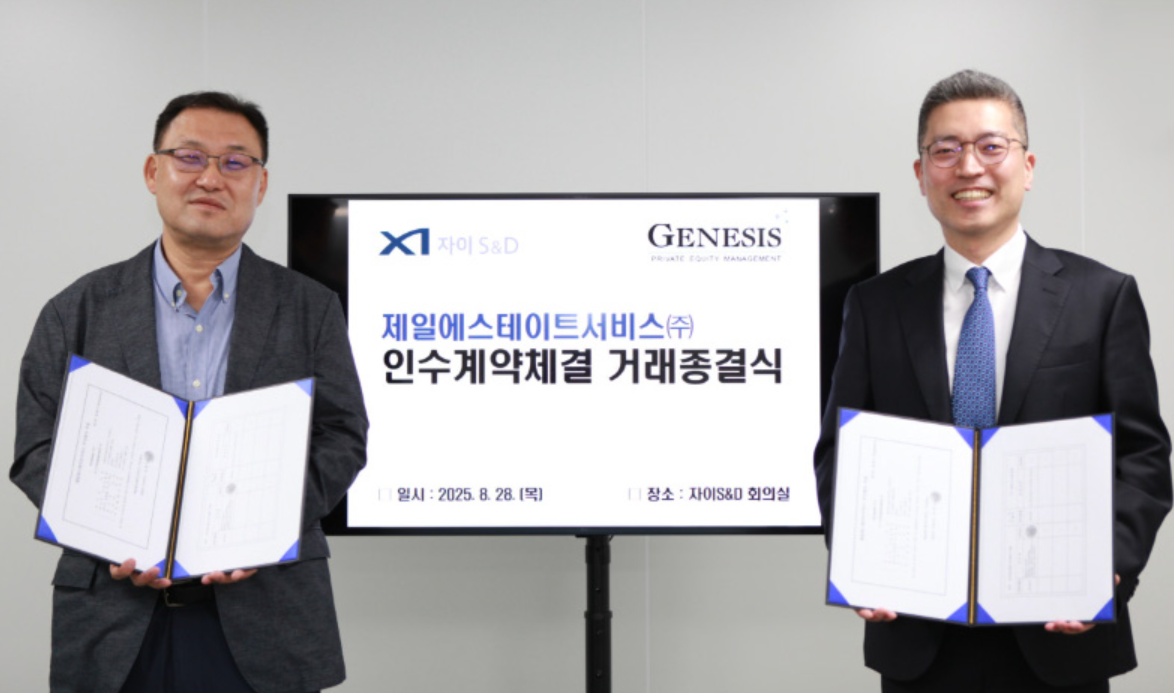
Genesis PE had a busy year. It identified the housing management market as its next arena for a roll-up strategy — acquiring and integrating companies in the same sector one after another. The firm had already acquired Xi S&D Home Service's business division (now Jeil Estate Service) and AJ Daewon (now Daewon Estate Service). This year it added Pureun General Housing Management and Gwangin Total Management to the portfolio.
A roll-up strategy involves acquiring multiple smaller companies to achieve economies of scale and improve operational efficiency. The key lies in complete integration. Simply buying similar or related businesses is not enough. The real challenge is eliminating the costs and inefficiencies that arise when companies operate independently, and weaving them together organically into a single platform through shared systems.
The definition of a roll-up is straightforward, but executing one is anything but. Genesis PE therefore invests considerable effort in selecting the industries where it will deploy the strategy, moving only when three conditions align: a fragmented market, steady cash flow and a strong growth outlook. Starting with KJ Environment in 2020, the firm acquired more than 10 waste and recycling companies in the Greater Seoul area, assembled the country's largest waste value chain, and sold it to EQT Partners for around 1 trillion won in 2024.
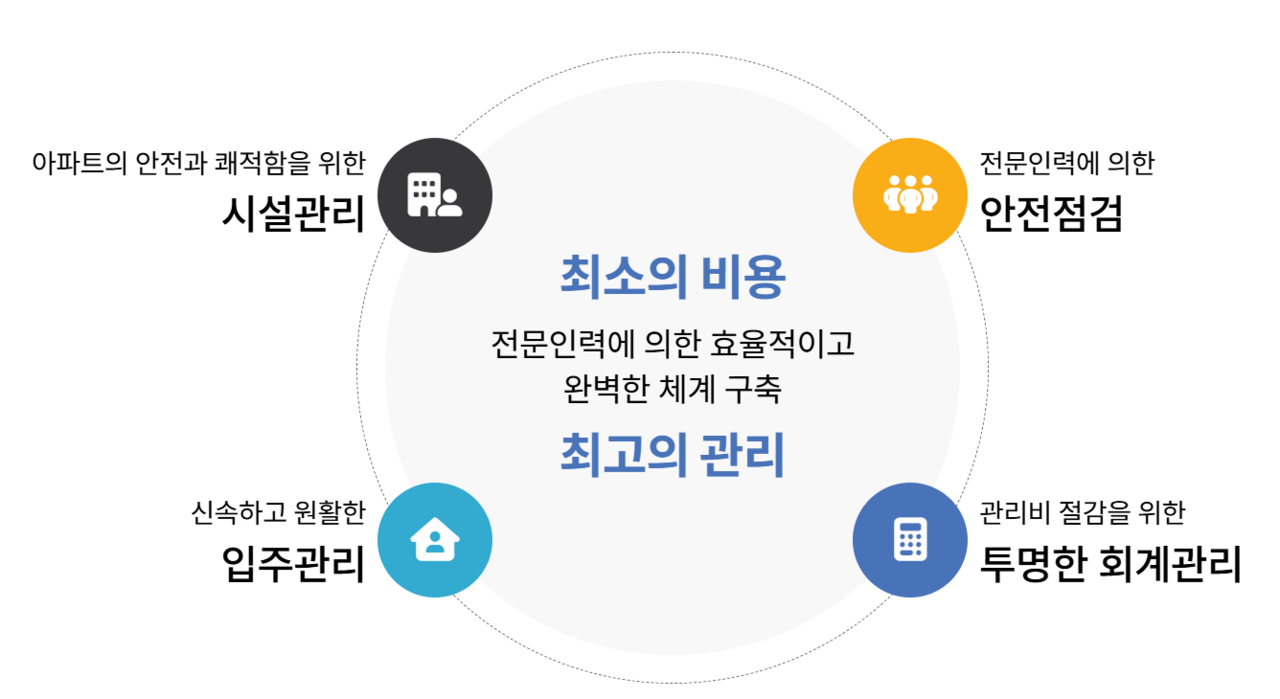
Housing management is one of the industries where Genesis PE spotted an opportunity. Once an apartment complex exists, demand for management services is inevitable. Collecting maintenance fees and inspecting facilities is just the beginning — security, cleaning, parking, various maintenance and repair tasks, and safety services all come with the territory. Demand for community-building services has also grown in recent years. Individual operators in the sector remain small-scale relative to the range and quality of services required.
Once an investment is underway, the next step is speed. Genesis PE acquired four housing management companies within a single year, then moved to add new capabilities. In August it signed a share purchase agreement to acquire a 100 percent stake in Capstech, a physical security and facilities management company under SK Group's SK Shielders. Where the firm had previously focused on "horizontal" expansion by buying companies in the same housing management space, the Capstech acquisition represents a "vertical" expansion — adding functions such as security services that housing management requires.
The idea is to bring in-house the physical security functions that housing management companies had previously outsourced to third parties, enabling more efficient operations. It is the essence of the Genesis PE roll-up approach: connecting the capabilities of individual companies to build a single platform.
Co-investment fund in the works as Xi Elevator roll-up gears up
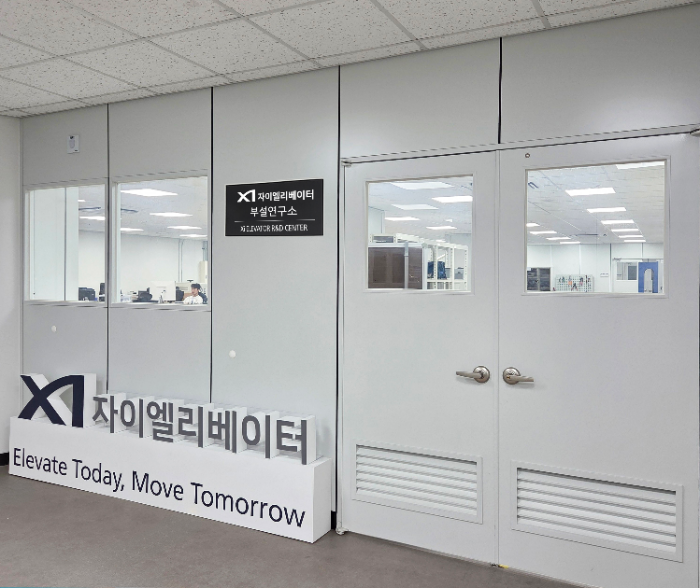
The same work is well underway at Xi Elevator, which Genesis PE acquired in 2024. The firm has its eye on the elevator maintenance and repair market that emerges after installation, rather than on manufacturing and installation itself. Large incumbent elevator manufacturers have long accumulated a substantial maintenance portfolio by following up their own installations with long-term service contracts.
Closing that gap through new installations alone is difficult. Instead, Genesis PE has been steadily acquiring small maintenance operators to build up its service volume. The number of units under management stood at 3,000 in 2024 and has grown fivefold to about 15,000 this year — a figure that speaks to the firm's execution. The goal is to secure more than 50,000 units by 2027 and capture more than 5 percent of the domestic elevator maintenance market, transforming Xi Elevator into a large-scale elevator maintenance and management platform.
To fund that push, Genesis PE plans to raise a co-investment fund of around 100 billion won and deploy it in additional acquisitions. A co-investment fund is one in which institutional investors commit separate capital alongside a manager's blind fund into a specific portfolio company. Previously, Genesis PE had channeled follow-on investment through its first blind fund.
The QT division of SGC Energy (now Quartz Technology), acquired in June, is another roll-up candidate. The company produces quartz crucibles — high-purity quartz vessels used in semiconductor wafer manufacturing. Because most quartz crucible producers are based in Japan, domestic companies have historically relied heavily on Japanese suppliers.
Genesis PE is targeting that domestic demand. It plans to lay the groundwork by securing external customers and upgrading its production and quality management systems, and is considering acquiring additional materials, components and equipment companies over the long term. Whether the firm can build yet another platform — this time in semiconductor materials, components and equipment, following waste management, housing management and elevator maintenance — is a question the market is watching closely.
Fund commitments quadruple in two years — where is the next blue ocean?
The market has responded to Genesis PE's consistent track record. Limited partners lined up behind a refined strategy that looks through individual companies to the industries they inhabit. The firm is approaching the final close of its second blind fund in November. It began fundraising with a target of 600 billion won, but commitments have now climbed to nearly 800 billion won.
Genesis Green No. 1 — the first blind fund Genesis PE raised, in 2024 — stood at 200 billion won, meaning the firm has roughly quadrupled its fund size in about two years. The second blind fund is named Genesis Blue No. 2. Where "Green" symbolized investment in eco-friendly industries, "Blue" carries the meaning of seeking newer opportunities across a broader range of sectors.
A larger fund means an expanded scope for Genesis PE — bigger industries to invest in and larger platforms to build. It is why limited partners have backed the investment approach the firm has refined over the past decade with even greater firepower. Which blue ocean Genesis PE will sail toward in its next decade is a prospect worth watching.
park.jiyeong@heraldcorp.com