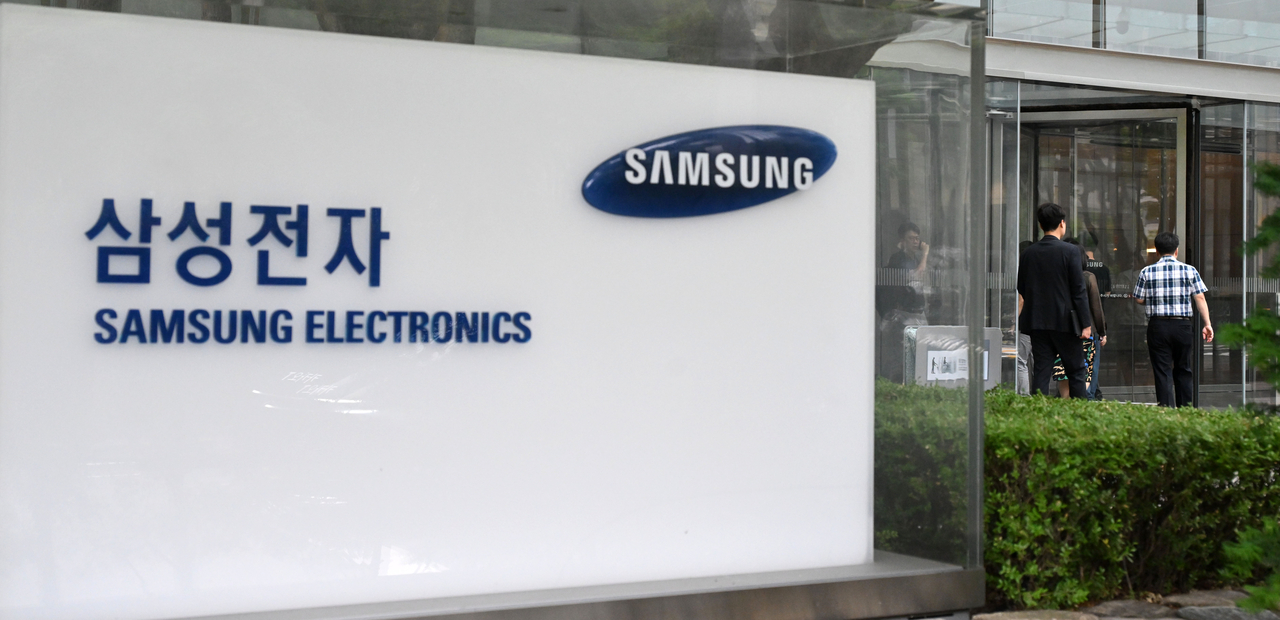
Samsung Electronics posted a record operating profit of 89 trillion won ($58.1 billion) in the second quarter, putting to rest growing market concerns that the semiconductor cycle had already peaked.
The company disclosed Tuesday that second-quarter sales rose 129 percent year-on-year to 171 trillion won, while operating profit surged 1,810 percent to 89.4 trillion won — a preliminary figure that beat the 85.05 trillion won consensus compiled by financial data provider FnGuide.
Samsung Electronics set aside provisions in the second quarter to fund a special performance bonus agreed upon through labor-management negotiations. Brokerages estimate the total provision, including retroactive amounts from the first quarter, at between 15 trillion won and 19 trillion won. Operating profit before the bonus provision is expected to have exceeded 100 trillion won.
The record results dispelled fears of a semiconductor peak-out that had weighed on the market in recent weeks. The earnings were also the first from a major chipmaker released since concerns emerged over a potential slowdown in AI investment following announcements by Meta, drawing intense attention from investors.
Those concerns arose after Meta unveiled plans to enter the cloud business using surplus computing resources, raising questions about whether big tech companies were pulling back on AI spending. The possibility of weakening demand stemming from Apple's product price increases had also dampened investor sentiment. Against that backdrop, Samsung Electronics delivered results that exceeded market expectations, demonstrating resilient memory chip demand.
Samsung Electronics' share price had been consolidating in recent weeks as peak-cycle concerns spread. Its one-month return stood at minus 5.93 percent as of Monday's closing price. Compared with the record closing high of 362,500 won reached on June 18, the stock has fallen 12.28 percent.
Brokerages expect Samsung Electronics to continue setting earnings records throughout this year, and say the recent pullback represents a buying opportunity.
Lee Jong-wook, an analyst at Samsung Securities, estimated Samsung Electronics' operating profit at 372 trillion won in 2026 and 565 trillion won in 2027. "With bit growth for both DRAM and NAND expected to slow next year, supply and demand will remain tight, making it highly likely that quarterly operating profit will stay above 100 trillion won for more than a year," he said. He added that investor concerns reflect market noise rather than any deterioration in fundamentals, and advised treating the current period as a buying opportunity.
Kim Seon-woo, an analyst at Meritz Securities, also said the record earnings are expected to be surpassed repeatedly throughout the year, citing rising memory chip prices through year-end as the key driver.
Brokerages emphasize that the memory super-cycle is still in its early stages. With supply shortages persisting, analysts say the earnings improvement could last longer than previously anticipated.
Kim said the memory cycle has yet to reach even its mid-cycle phase, adding that capacity constraints will make it difficult for memory supply to keep pace with demand growth at least through the fourth quarter of next year.
Nomura Securities also pushed back against the peak-cycle narrative, forecasting that supply shortages will continue and warning that the second half of the year could see the most severe supply-demand imbalance in the memory market on record.
Analysts see ample room for further share price gains. The highest target price on Samsung Electronics is 670,000 won, set by Nomura Securities, implying upside of 110.69 percent from Monday's closing price of 318,000 won.
Target prices by brokerage are as follows: Korea Investment & Securities and Shinhan Investment at 590,000 won; Hanwha Investment and Sangsangin Investment & Securities at 580,000 won; Eugene Investment & Securities and Daishin Securities at 560,000 won; and KB Securities and Mirae Asset Securities at 550,000 won.
Brokerages also highlighted the prospect of a shareholder return program set to ramp up in the second half of the year. Analysts said a large-scale share buyback and cancellation, on top of improving earnings, could provide fresh upward momentum for the stock.
Son In-jun, an analyst at Eugene Investment & Securities, said Samsung Electronics is expected to direct 50 percent of its annual free cash flow toward shareholder returns centered on share cancellations, adding that a large-scale return program is likely to drive outperformance in a stock that has lagged in recent months.
As of 10 a.m. Tuesday, Samsung Electronics shares were trading at 298,500 won, down 6.13 percent from the previous session. Despite the record earnings announcement, the stock was under pressure as investors moved to lock in profits.
moon@heraldcorp.com