Tax subcommittee to weigh deduction and loss carryforward issues next week
Deduction expansion faces headwinds over equity concerns from Assembly, government
'A 2.5 million won deduction structure, like overseas stocks, is more reasonable'
'Most small holders effectively excluded from taxation already'
Loss carryforward backed in principle, but revenue volatility concerns raised
Data submission rules likely to take effect early even as taxation is delayed
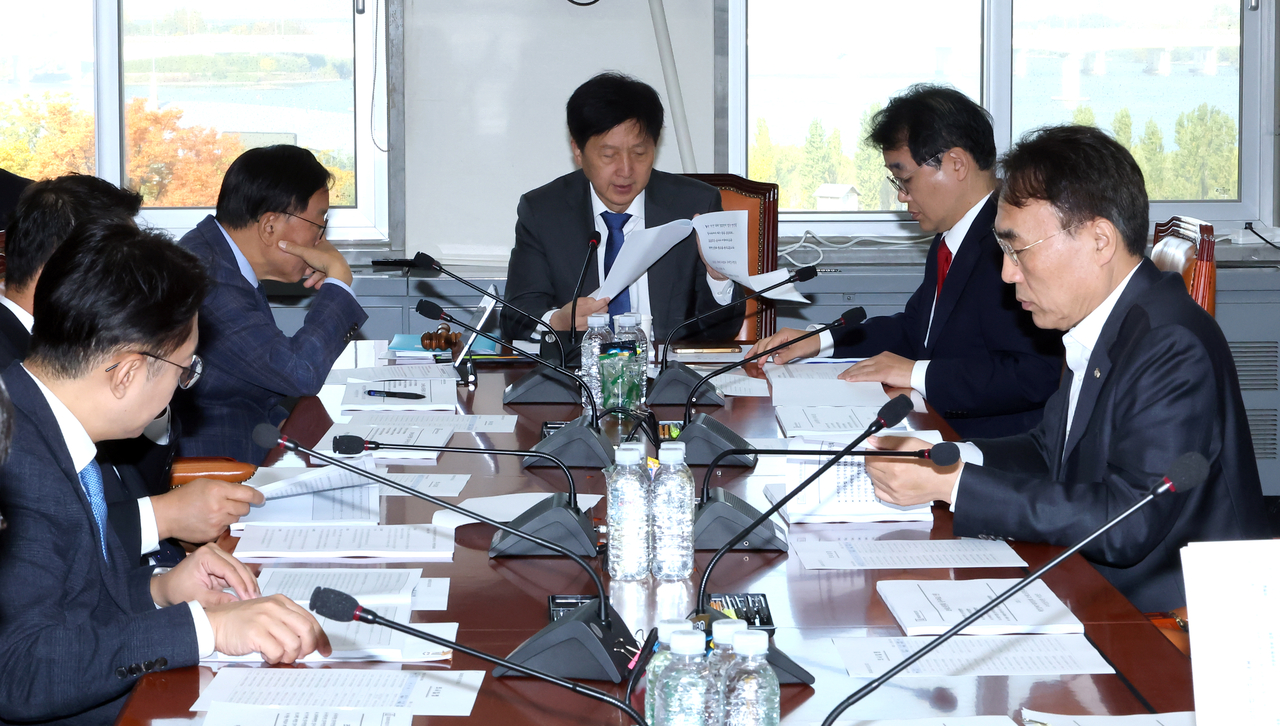
With the ruling and opposition parties having reached a tentative agreement to delay virtual asset taxation by two years, a National Assembly expert has said it would be unreasonable from a policy standpoint to raise the basic deduction from 2.5 million won ($1,880) to 50 million won. The expert said tax equity must be considered relative to other investment assets such as overseas stocks, which currently carry a basic deduction of 2.5 million won. Concerns were also raised that while the introduction of a loss carryforward deduction is warranted in principle, it could reinforce speculative behavior and increase tax revenue volatility.
According to the National Assembly, the Finance and Economy Planning Committee's tax subcommittee reached a consensus Wednesday on pushing back virtual asset taxation from 2027 to 2029. Three issues — expanding the basic deduction, introducing a loss carryforward deduction, and requiring virtual asset businesses to submit taxation data — were set aside for further discussion before a final decision is made. The next tax subcommittee session has been tentatively set for Thursday through Friday.
50 million won deduction for crypto? 'Equity with overseas stocks' 2.5 million won threshold must be weighed'
The proposal to expand the basic deduction was put forward in an income tax law amendment bill introduced by People Power Party lawmaker Choi Eun-seok. It would raise both the basic deduction and the minimum taxation threshold for virtual asset income from 2.5 million won to 50 million won — matching the level that had been planned for domestic listed stocks under the now-scrapped financial investment income tax — on the grounds that the tax framework should reflect both cross-asset equity and the growth of the virtual asset market.
In a review document submitted to the tax subcommittee, the Assembly expert said the policy rationale for supporting domestic stocks and virtual assets should be treated separately. Domestic stocks serve the purpose of channeling investment into corporate capital-raising, but virtual assets are not generally used as a means of corporate financing, making it difficult to justify the same level of tax support.
Even accounting for the similarity that investors treat virtual assets like stocks — buying and selling them repeatedly to generate capital gains — the expert said it is more appropriate to compare virtual assets with overseas stocks, which carry a basic deduction of 2.5 million won. Overseas stocks are currently taxed at an income tax rate of 20 percent on the net annual transfer gain after a 2.5 million won deduction.
The expert also said the argument that virtual assets deserve preferential tax treatment on the grounds of equity with the now-abolished financial investment income tax lacks a sufficient basis. There were also concerns that expanding the deduction would effectively exclude a large share of investors from taxation, running counter to the principle of a broad tax base with low rates.
According to a survey by the Korea Financial Intelligence Unit (KoFIU), 77.2 percent of virtual asset user accounts held assets worth less than 1 million won as of the end of June this year. Accounts holding 10 million won or more accounted for just 8 percent of the total. In practice, raising the basic deduction to 50 million won would mean the vast majority of investors would pay no tax at all.
Both inside and outside the Assembly, the expanded deduction is widely seen as unlikely to pass. Lawmaker Oh Ki-hyung said, "The government has been opposed on equity grounds, so we agreed to continue the discussion."
Loss carryforward backed in principle, but 'speculative risk and revenue swings' raise concern
On the introduction of a loss carryforward deduction, the Assembly and the government are largely aligned.
The government plans to use the tax deferral period to refine the detailed framework, allowing investment losses to be deducted from gains over the following three years. A bill introduced by lawmaker Ahn Do-geol similarly proposes allowing a three-year loss carryforward for confirmed deficits — whether through filing, assessment, or correction — with the provision applying to losses incurred from 2029 onward. The Assembly expert also agreed with the underlying principle of taxing actual net income.
However, the expert said allowing a loss carryforward exclusively for virtual assets — while denying it for overseas stocks, unlisted shares and real estate — could undermine tax equity. While the loss carryforward under the scrapped financial investment income tax had a policy rationale of encouraging investment in risk assets to foster venture capital, applying it to virtual assets could instead reinforce their speculative character.
The expert also flagged the risk of greater tax revenue volatility. "Given the high price volatility of virtual assets, deducting large losses accumulated during a downturn from income earned during an upturn could sharply reduce tax revenue and increase year-to-year instability in tax receipts," the expert said.
Early data submission mandate seen as positive, but scope remains a sticking point
Even if taxation is delayed, the obligation for virtual asset businesses to submit taxation data is expected to take effect early. Both the government and the Assembly expert agreed that domestic and overseas transaction data should be linked and analyzed during the deferral period, and that a filing support system and verification framework should be put in place ahead of the tax's implementation to reduce the reporting burden on investors.
However, the scope of data to be submitted and the timing of sanctions remain points requiring adjustment.
Lawmaker Ahn's bill adds to the list of required submissions "data necessary for preparing to implement income tax collection, as determined by presidential decree." The expert said delegating the scope and content of such data broadly to subordinate legislation could reduce predictability for businesses, and called for the delegation to be made more specific. The expert also said that even if the data submission obligation takes effect from 2027, sanctions such as corrective orders and fines should not be applied during the tax deferral period.
In response, the ruling and opposition parties agreed to conduct a further review of the specific content and scope of data to be submitted to tax authorities. Tax subcommittee chair Oh Ki-hyung said, "There was a view that relevant data should be collected and simulated in advance to improve the accuracy of the taxation system," adding, "We agreed to finalize the matter after reviewing the specific content of the data to be submitted."
Separately from businesses submitting data to tax authorities, there is also discussion of requiring businesses to provide investors with data for calculating their income. The expert acknowledged that this would reduce the reporting burden on investors, but said caution is warranted when it comes to requiring businesses to provide data that may be difficult to verify or that falls outside their scope of responsibility.
forest@heraldcorp.com