
Combined substandard-and-below loans reach 7.61 trillion won, up 1.3 trillion won in a year
Asset quality deteriorates, led by corporate loans; precautionary and estimated-loss credits also rise
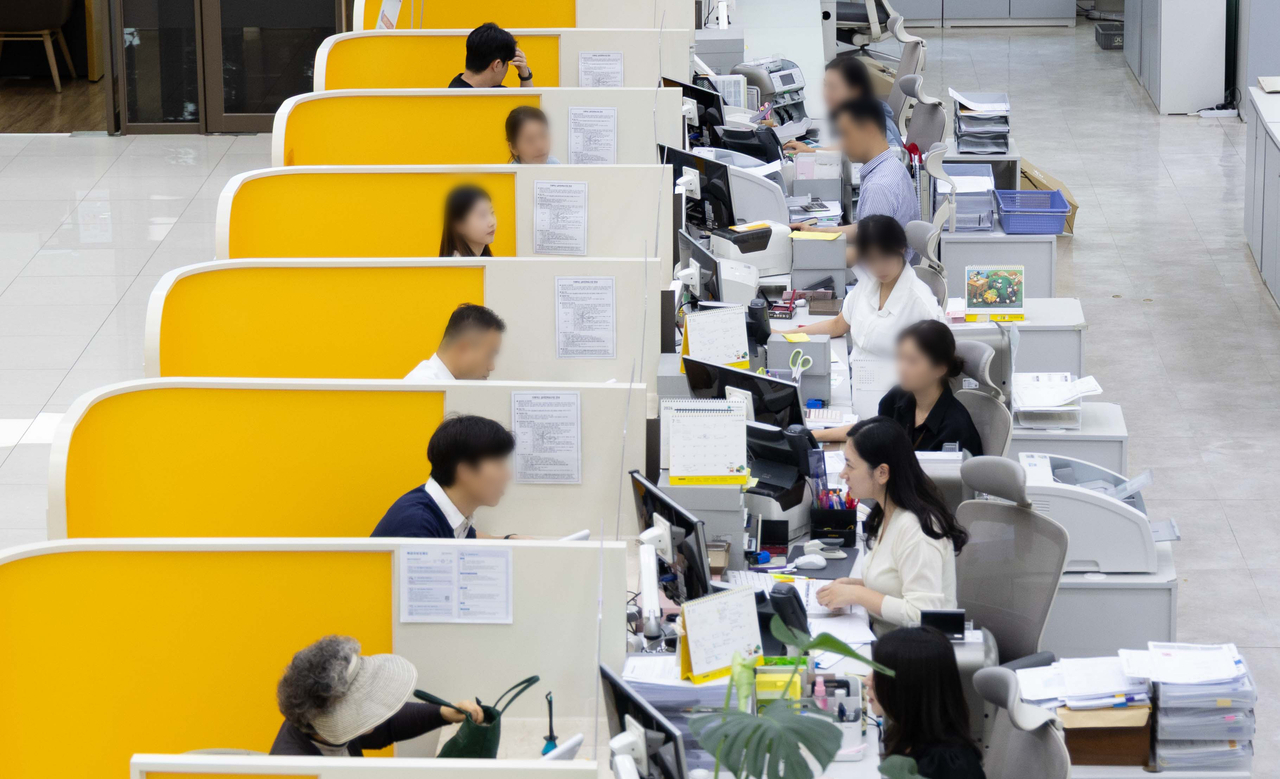
Small and medium-sized enterprise borrowers are finding it increasingly difficult to service their debts as sluggish domestic demand has cut into orders and sales while loan interest burdens have grown. The mounting repayment strain is pushing up bad loans across the banking sector, with the five major banks' substandard-and-below loans hitting their highest level in eight and a half years and asset-quality indicators deteriorating, particularly in corporate lending.
KB Kookmin, Shinhan, Hana, Woori and NH NongHyup Bank together held 7.61 trillion won ($5.7 billion) in substandard-and-below loans at the end of the third quarter, according to financial industry data released Sunday. That was up 1.28 trillion won from the same period last year (6.33 trillion won) and up 180.5 billion won from the previous quarter (7.43 trillion won) — the largest figure since the first quarter of 2018, when the total stood at 8.21 trillion won.
The five banks' combined substandard-and-below loans have risen steadily from 4.49 trillion won at end-2023 to 5.58 trillion won at end-2024 and 6.18 trillion won at end-2025. After crossing the 7 trillion won mark at the end of the second quarter this year, the figure continued to climb through the third quarter.
Financial institutions classify asset quality into five tiers: normal, precautionary, substandard, doubtful and estimated loss. Substandard-and-below loans — commonly referred to as non-performing loans, or NPLs — include credits that are at least three months past due.
The ratio of substandard-and-below loans to total outstanding loan balances also rose, driven mainly by corporate lending. The simple average NPL ratio for won-denominated loans at the five banks stood at 0.40 percent at the end of the third quarter, roughly flat from the previous quarter but up 0.05 percentage points from the same period last year (0.35 percent).
The NPL ratio for household loans edged up 0.03 percentage points, from 0.22 percent in the third quarter of last year to 0.25 percent this quarter. For large corporations, the ratio rose 0.08 percentage points to 0.32 percent from 0.24 percent, while for small and medium-sized enterprises it climbed 0.04 percentage points to 0.59 percent from 0.55 percent.
Deterioration in corporate loan quality was also evident at individual banks. One bank's NPL ratio for corporate loans reached 0.63 percent, the highest since the second quarter of 2019 (0.70 percent). Its large-corporate ratio hit 0.64 percent, also the highest since that period, while its SME ratio reached 0.66 percent, the highest since the third quarter of 2019 (0.71 percent).
Estimated-loss credits — loans deemed in effect unrecoverable — also increased. The five banks held 1.09 trillion won in estimated-loss loans at the end of the third quarter, up 18.7 percent from 921 billion won in the same period last year.
Precautionary loans, which signal potential future impairment, are also on the rise. The five banks' precautionary loan balance reached 10.53 trillion won at the end of the third quarter, up 2.5 percent from 10.27 trillion won a year earlier and up 3.0 percent from 10.22 trillion won the previous quarter. Precautionary loans are credits that banks monitor closely because the borrower's repayment capacity has weakened or default risk has emerged. Should delinquencies lengthen or repayment conditions worsen, these loans can be reclassified as substandard-and-below, meaning a further rise in precautionary credits could translate into more NPLs down the road.
There are also concerns that rising benchmark lending rates could push bad loans even higher by adding to borrowers' interest burdens. "Rates used as lending benchmarks — including COFIX and bank bonds — have been rising, increasing borrowers' interest costs and gradually pushing up delinquencies," an official at a commercial bank said. "As asset-quality indicators have been weakening recently, we are focusing on management."
attom@heraldcorp.com




