Cho Jung-hoon: 'This is regulation in effect, not voluntary consultation'
Lawmaker calls for legal framework or bank autonomy over loan targets
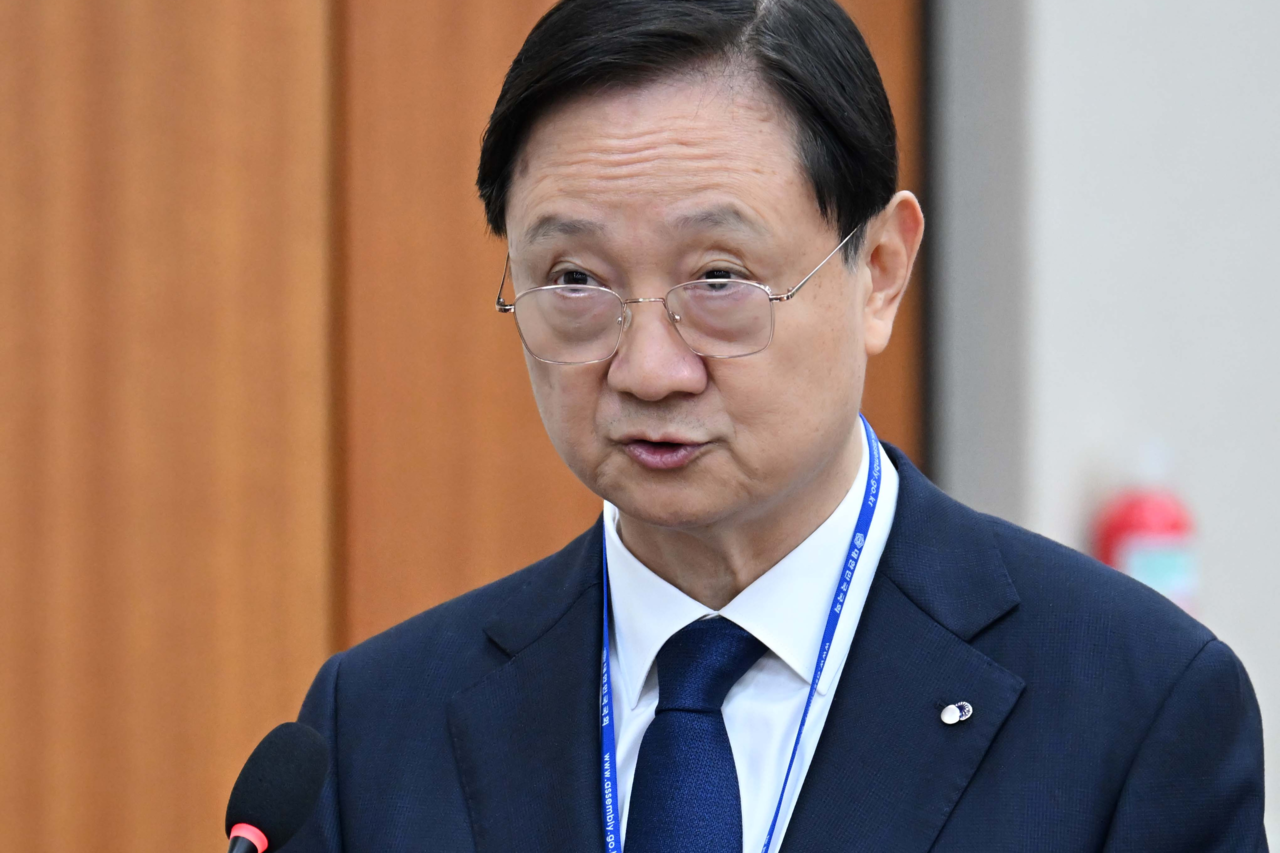
The financial authorities' practice of capping total household loan volumes at commercial banks came under scrutiny Monday at a national audit conducted by the National Assembly's Political Affairs Committee. When People Power Party lawmaker Cho Jung-hoon pressed Financial Supervisory Service Director General Lee Chan-jin on the legal basis for the caps, Lee said he did not believe any direct regulatory provision existed.
Cho questioned the chiefs of the five major commercial banks on how they coordinate annual household loan growth targets with the financial authorities.
He asked Shinhan Bank President Jeong Sang-hyeok in particular whether the household loan growth target set by the financial authorities this year had come in below the bank's own management plan drawn up at the start of the year. Jeong said it had.
Cho then asked whether the FSS had any legal authority to restrict the total volume of household loans at banks. Lee said he did not believe any direct regulatory provision existed.
Cho said it was misleading for the financial authorities to describe the process of setting loan targets for individual banks as "voluntary consultation." "The bank presidents all know what penalties await them if they fail to comply — calling it consultation is just a polite word," he said. "The scale of household lending is a critical management decision that affects interest income, the risk of bad loans and net profit for the period."
Cho pressed Lee again on the legal basis for the total loan caps. Lee repeated that he did not believe any direct regulatory provision existed.
"The authorities are interfering with the business operations of financial institutions without any legal basis," Cho said, adding that while managing financial soundness was necessary, imposing volume caps went beyond the FSS's authority.
He also said that if the authorities could demand that banks reduce their total loan volumes, the same logic would allow them to demand that banks lend more than planned. "Either establish a legal basis or let banks set their own targets," he said.
Cho also argued that the volume-management approach could weaken banks' credit screening functions, as banks would end up adjusting lending to meet the growth targets set by the authorities rather than assessing individual borrowers' repayment capacity and creditworthiness.
In response, Lee said the household loan volume management regime had been in place for a very long time. "This is currently carried out as part of financial policy, and the FSS is responsible for its implementation," he said.
rim@heraldcorp.com