'Technological benefits and investment returns are separate' — AI boom compared to railroad, internet frenzies
$9 trillion in projected investment through 2032; analysts warn earnings could suffer when data center construction slows
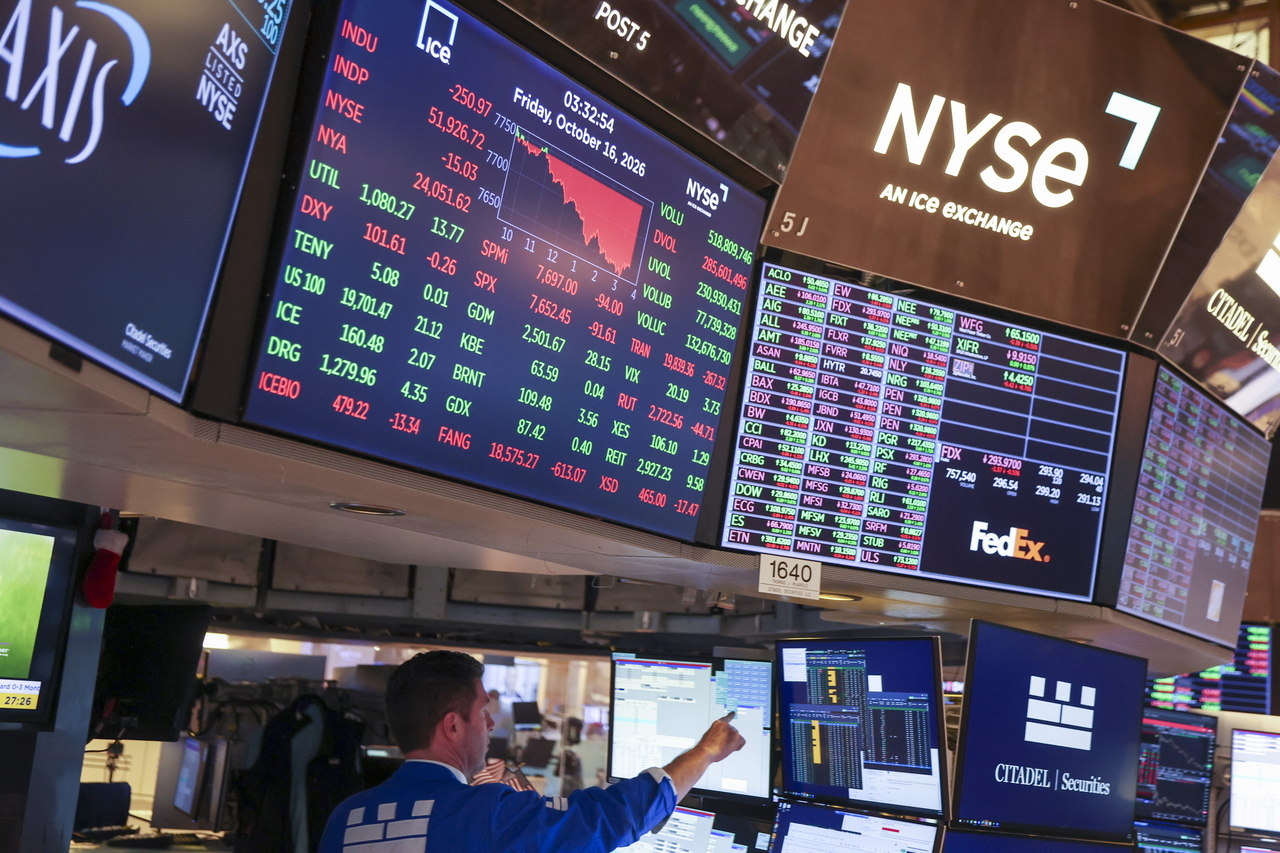
Warnings are growing that the AI industry's astronomical spending by Big Tech could repeat the history of overinvestment seen in the railroad and internet booms — eras when massive capital outlays failed to deliver the returns investors had expected.
Wall Street Journal columnist James Mackintosh raised the alarm in a column published Sunday, titled "The Lesson AI Stock Wobbles Are Teaching Us: This Time Isn't Different," arguing there is still no evidence that the current AI investment boom can avoid the pitfalls that plagued past waves of large-scale capital spending.
Mackintosh invoked the phrase "This time it's different" — what legendary investor John Templeton called the most dangerous words in investing — to argue that the enormous profits AI-related companies are generating today offer no guarantee of future investment returns.
He pointed to the British railway investment bubble of the 1840s and the fiber-optic network buildout during the dot-com era around 2000 as prime examples. Both waves of investment delivered enormous benefits to society as a whole, yet left investors disappointed — either because it took far too long to realize returns or because intensifying competition eroded profits well below expectations. The AI industry, Mackintosh warned, could face a similar fate.
Stijn Van Nieuwerburgh, a professor at Columbia Business School, estimated in a recent Brookings Institution report that total AI-related investment in the United States could reach $9 trillion through 2032. That would amount to an average of 3.2 percent of annual US GDP devoted to AI investment over the period — potentially the largest capital investment project in American history.
Mackintosh said that even if vast sums are poured into building data centers, a significant portion of that investment may never be recouped if AI technology fails to generate sufficient economic value.
He also said the high profits that AI-related companies are currently enjoying may not last. Sales and earnings for companies supplying semiconductors, cooling systems and generators have surged alongside the data center construction boom, but demand for those products could fall once the building frenzy subsides.
Investors appear to share that skepticism, judging that today's elevated profits are unlikely to hold — a dynamic reflected in AI-related share prices rising far less than earnings growth would suggest. Nvidia, the most valuable company in the United States by market capitalization, has seen its share price climb 15 percent, yet its forward price-to-earnings ratio — based on projected earnings over the next 12 months — has fallen from 23 times to 15 times.
Memory chipmaker Micron has seen its share price triple, yet its forward P/E ratio remains below five times.
Concerns have also mounted recently that higher-than-expected US inflation could raise borrowing costs and dampen data center investment. Against that backdrop, shares of data center operator CoreWeave plunged 24 percent last week, wiping out all of this year's gains, while Micron fell 11 percent. Samsung Electronics and SK hynix in South Korea dropped 17.8 percent and 24.3 percent, respectively, posting their worst weekly declines since the 2008 financial crisis.
Mackintosh said that even if AI investment proceeds as planned, vast sums could be wasted if the technology fails to generate adequate returns — and that if investment slows instead, the earnings of chipmakers and other related companies could take a serious hit.
yckim6452@heraldcorp.com