KT&G posts weekly gain of 8.19%
Record operating profit forecast for Q3
Shareholder return policy adds support
KT&G shares climbed more than 6% this week even as the broader domestic market sold off sharply, driven by expectations that the tobacco company will post record earnings in the third quarter. Its appeal as a defensive stock — backed by steady earnings growth and a high dividend yield — also drew investor attention.
According to Korea Exchange, KT&G shares rose 8.19% from Monday through Friday, in stark contrast to the Kospi's 16.69% plunge over the same period. The stock surged 3.96% on Thursday alone, the day the Kospi tumbled more than 7% and triggered a circuit breaker.
Institutional investors and pension funds were net buyers over the five trading sessions, purchasing 80 billion won ($59.3 million) and 11 billion won worth of shares, respectively, helping support the index.
Expectations for third-quarter results are the main driver of the share price strength. Analysts forecast KT&G will post record operating profit, buoyed by growth in overseas cigarette sales and improved profitability in its domestic tobacco business.
KB Securities estimates KT&G's consolidated third-quarter sales at 1.94 trillion won and operating profit at 496.8 billion won, up 13.9% and 19.8%, respectively, from a year earlier. The operating profit estimate is expected to be in line with the market consensus.
Overseas cigarette sales are seen as the key growth driver, with the segment forecast to rise 12% year-on-year. Last year, overseas cigarette sales accounted for 22% of KT&G's total sales.
"On top of growth in the overseas tobacco business, cost-reduction effects in the domestic segment and pre-sale revenue from the real estate division will combine to set new all-time highs in both sales and operating profit," said Choi Go-un, a researcher at Korea Investment & Securities.
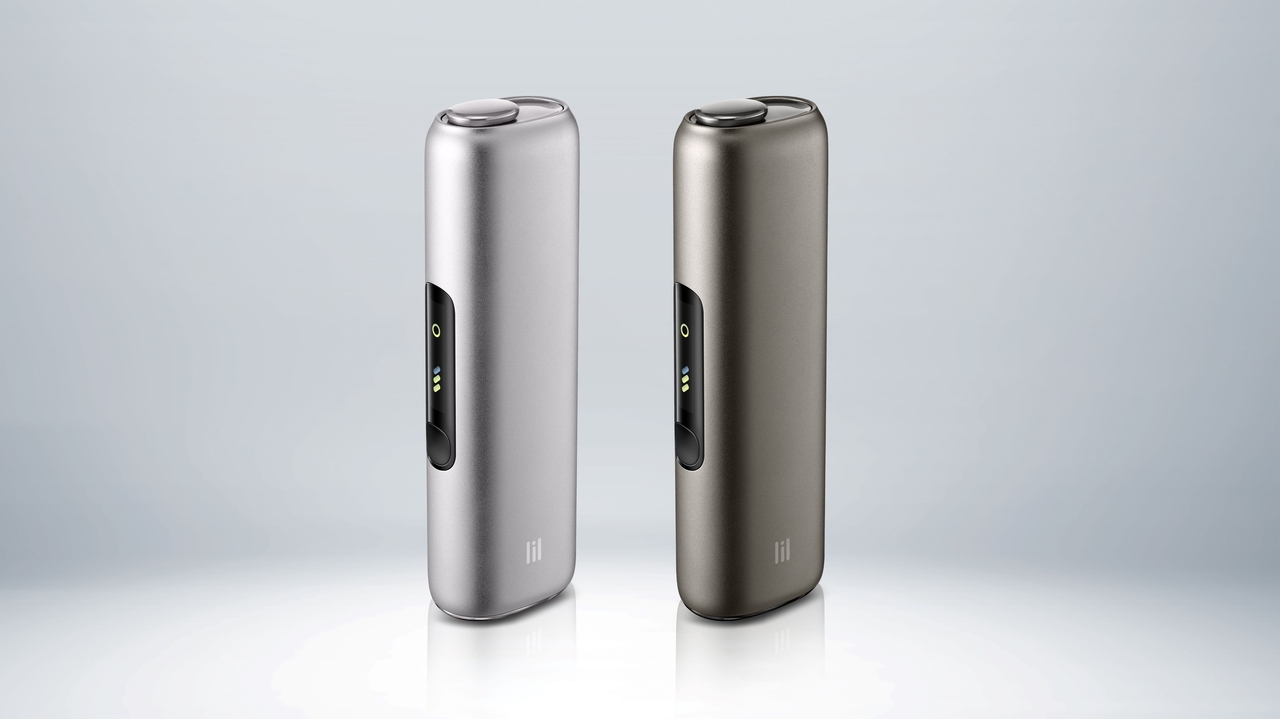
An aggressive shareholder return policy is also underpinning the share price. According to Daol Investment & Securities, KT&G's dividend yield this year is estimated at 4.4%, with the company's continued commitment to expanding dividends expected to make the stock increasingly attractive to income investors.
A buyback is also underway. KT&G plans to repurchase 2.07 million shares worth 360 billion won between last month and December. Total shareholder returns planned from 2024 through 2027 amount to 3.7 trillion won. The company is also set to announce a new shareholder return policy next month.
"A virtuous cycle is taking shape in which the strategy of focusing on three core growth businesses — heated tobacco, global operations and health functional foods — along with new growth drivers such as nicotine pouches, feeds into robust shareholder returns, pointing to a steady share price trajectory," said Jo Sang-hun, a researcher at Shinhan Securities.
A falling won-dollar exchange rate remains a wildcard for fourth-quarter earnings. Given the company's high proportion of overseas sales, a stronger won weighs on results. "The recent sharp drop in the won-dollar rate means fourth-quarter earnings expectations need to be revised down," said Kwon Woo-jeong, a researcher at Kyobo Securities.
"We believe concerns over the weaker exchange rate are already priced into the stock, and we expect annual operating profit growth to meet the guidance range of 10 to 13 percent," said Ryu Eun-ae, a researcher at KB Securities. "While the exchange rate impact in the fourth quarter is unavoidable, the downside risk to the share price is limited when factoring in the new dividend-focused shareholder return policy set to be announced in early next month."
moon@heraldcorp.com