Rehabilitation plan approved, green light for recovery
Jeil M&S seeks injunction to halt delisting
Kosdaq-listed Jeil M&S, currently undergoing court receivership, has reached a critical juncture in its bid to return to normal operations.
According to investment banking industry sources Thursday, the Suwon Rehabilitation Court's 50th Civil Division approved Jeil M&S's rehabilitation plan. Deloitte Anjin is serving as the sale manager.
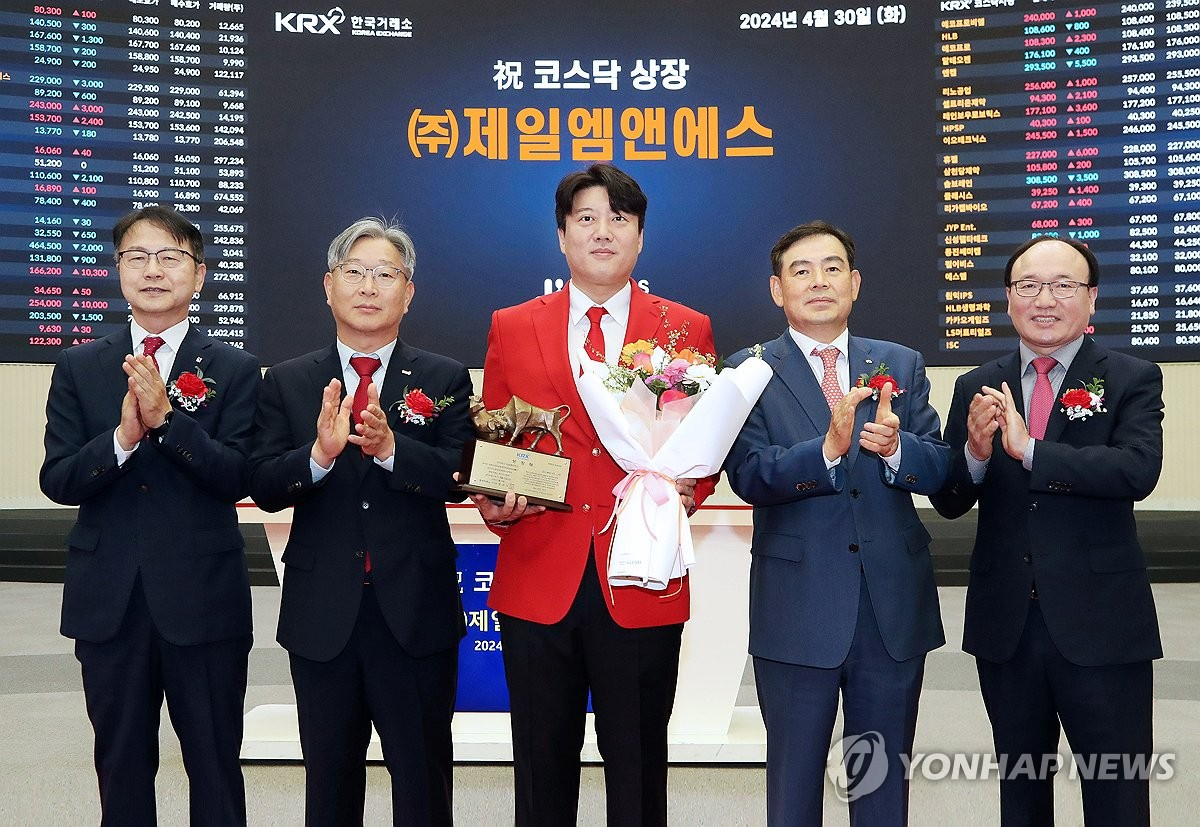
Jeil M&S, founded in 1986, is a manufacturer specializing in mixing equipment and facilities for secondary batteries. The company earned recognition for its technology after becoming the first in South Korea to domestically produce secondary battery mixing equipment, and listed on Kosdaq in 2024. At the time of listing, its market capitalization reached approximately 450 billion won ($336 million), based on an IPO price of 22,000 won ($16) per share.
Just a year after listing, however, the company's auditor issued a disclaimer of opinion on its financial statements for fiscal year 2024, triggering grounds for delisting. Its financial position then deteriorated sharply after key client Northvolt filed for bankruptcy, prompting Jeil M&S to apply for court receivership in December last year.
After receivership proceedings began, the company moved relatively quickly to secure a buyer. The Suwon Rehabilitation Court approved a stalking-horse pre-approval merger and acquisition process in March, and Pureun Investment was confirmed as the preferred acquirer in May. Pureun Investment's largest shareholder is Kosdaq-listed Finger, an affiliate of Sungho Electronics. Finger recently acquired Sea FSI as well.
The complication came when Korea Exchange decided to delist the company. While an acquirer had already been selected and a detailed rehabilitation plan was being drawn up, the Kosdaq Market Corporate Review Committee voted to delist Jeil M&S on Sept. 17.
Industry and legal circles have described the situation as somewhat unusual. While there have been past cases where a delisting decision followed the conclusion of rehabilitation proceedings — whether through completion or rejection of a rehabilitation plan — it is rare for a company to be delisted while an acquirer has already been chosen and an M&A process is actively under way.
This is because, when a listed company pursues a pre-approval M&A, the maintenance of its listing status is one of the key conditions of the deal. Acquirers weigh not only the target company's business and assets but also whether it remains listed. The delisting decision against Jeil M&S has raised concerns that the buyer could walk away or that the rehabilitation plan could be voted down.
"Even a company that is little more than a shell commands a premium if it is listed, because getting a company listed takes money and effort," said one attorney specializing in corporate rehabilitation. "When a listed company pursues a rehabilitation M&A, listing status is not only a key factor in the investment decision — it also determines the scale of capital committed."
Some observers note that the situation arose because Korea Exchange's delisting review and the court's rehabilitation process operate under different objectives and standards. Rehabilitation courts prioritize a company's viability and repayment to creditors, while the exchange places investor protection above all else — meaning that the mere fact of an acquirer being identified through rehabilitation proceedings is not enough to deem the company a safe investment.
Against this backdrop, Jeil M&S has mounted a legal challenge to the delisting decision. The company has filed for an injunction to suspend the effect of Korea Exchange's delisting ruling, with a hearing scheduled for Oct. 21. Even if the injunction is granted, it would only temporarily pause the exchange's decision and would not constitute a final confirmation of continued listing status. The legality of the delisting decision and the question of whether listing status can be maintained would need to be litigated separately through a full trial.
The approval of the rehabilitation plan means Jeil M&S has cleared the first hurdle on the road to recovery. However, the delisting decision has made that road considerably more complicated. If the delisting is finalized, the listing premium the acquirer had counted on would disappear, potentially disrupting its strategy for recouping its investment. The acquirer would be left bearing the risks that come with a delisted company.
"It seems the government's push to tighten delisting standards led the exchange to apply strict criteria regardless of the rehabilitation process," said one IB industry official. "If similar cases accumulate, transaction uncertainty rises and rehabilitation M&A becomes harder to execute."
park.jiyeong@heraldcorp.com