Fed expected to pause rate hikes at October FOMC
NASDAQ, AI stocks rally; domestic semiconductor shares seen benefiting
Bank of Korea also likely to hold on Oct. 22
Long-term bond yields, oil prices and exchange rate remain wildcards
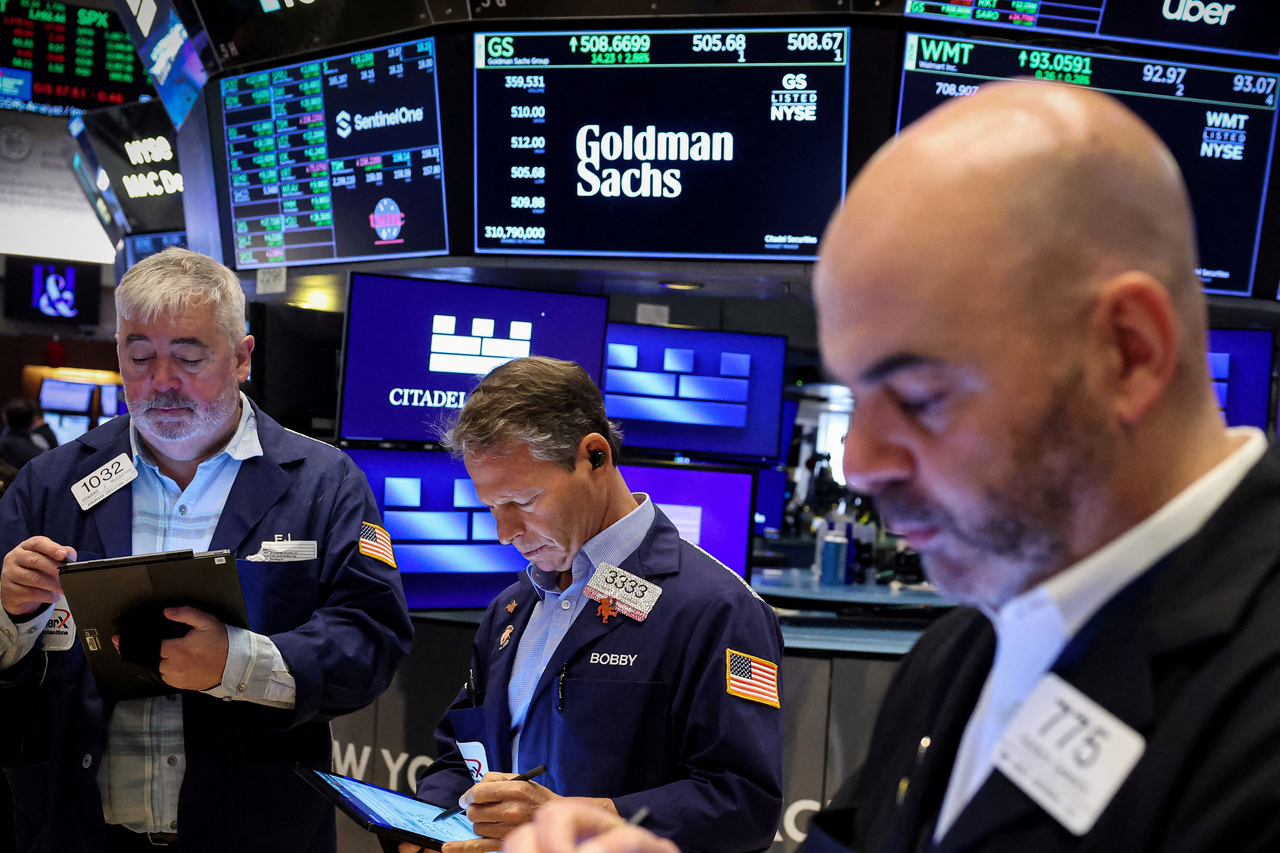
A weaker-than-expected US jobs report has sparked a relief rally in global markets. With the likelihood of a Federal Reserve rate hike at the October FOMC meeting fading, analysts expect investor sentiment in South Korea to improve, led by semiconductor and AI-related stocks. The Bank of Korea is also seen as more likely to hold rates in October and assess the impact of its two previous hikes rather than move again.
The Dow Jones Industrial Average rose 250.40 points, or 0.49 percent, to close at 51,176.96 on Friday (local time). The S&P 500 gained 0.73 percent to finish at 7,722.72, while the NASDAQ Composite climbed 1.19 percent to 27,190.86. The NASDAQ 100 set a new all-time high.
According to the US Department of Labor, nonfarm payrolls rose by just 29,000 in September — far below the market consensus of 84,000. July and August figures were also revised down by a combined 60,000. The unemployment rate edged up to 4.2 percent, and average hourly earnings growth slowed to 0.1 percent month-on-month and 3.0 percent year-on-year.
The simultaneous softening of employment and wage growth fueled expectations that the Fed will not rush to raise rates at its October FOMC meeting. The probability of a rate hold in October, as priced in interest-rate futures markets, rose from 75.6 percent to 77.9 percent on Friday.
With rate-hike pressure easing, technology stocks led the advance. Nvidia surged more than 3 percent during trading to hit its highest level in five months before closing up 1.34 percent. AMD gained 2.95 percent. Analysts say Samsung Electronics and SK hynix, along with other semiconductor and AI-related names, could lead the Kospi higher when domestic markets reopen.
The Kospi recovered the 7,000 mark on Friday, closing at 7,003.74 — up 32.39 points. A reduced risk of further US tightening could ease concerns about a stronger dollar and foreign capital outflows, lending support to the index holding above 7,000. A recent survey of domestic fund managers found that a majority expect the market to dip early in the fourth quarter before rebounding — a pattern of weakness early and strength later.
However, the scope for further gains may be limited. The US 10-year Treasury yield initially fell after the jobs data but rebounded to 5.283 percent. South Korea's three-year government bond yield also rose to 3.937 percent. While rate-hike fears have eased, persistently high long-term yields continue to weigh on the valuations of growth stocks. Middle East tensions, international oil prices and the won-dollar exchange rate remain additional variables that could sway foreign investor flows.
The US jobs data is also expected to influence the Bank of Korea's rate path. The central bank raised its benchmark interest rate by 0.25 percentage points each in July and August, bringing it to 3.00 percent per annum. If the likelihood of further US hikes diminishes, the Bank of Korea faces less pressure to move quickly to narrow the Korea-US rate gap or counter won weakness.
Markets are now leaning toward the Monetary Policy Board holding rates at its Oct. 22 meeting and monitoring the economic and inflation effects of two consecutive hikes. However, the Bank of Korea remains alert to inflation running above its target, rising home prices in the Greater Seoul area and growing household lending — meaning a hold would not necessarily signal the end of the tightening cycle.
Ultimately, the direction of South Korea's financial markets will hinge on US consumer prices, Treasury yields, international oil prices and the won-dollar exchange rate. The Kospi may attempt a short-term rally led by semiconductor stocks, but if interest rates and the exchange rate fail to stabilize, high volatility and sector rotation near the 7,000 level are likely to persist.
attom@heraldcorp.com