Working-level party-government meeting held at National Assembly
'5% rule' revision, joint voting rights deregulation under review
Bear hug bill targeted for passage in regular session
Exchange's low-PBR disclosure rollout to be monitored
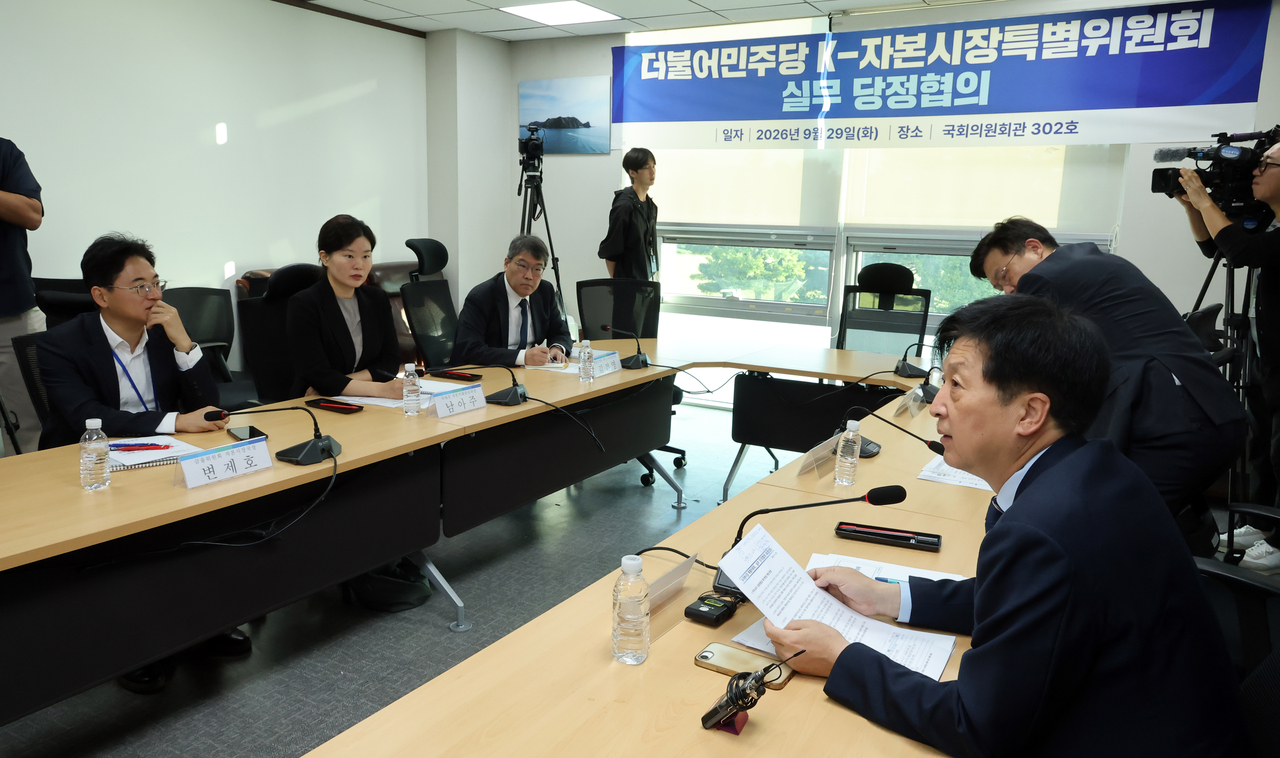
The government and the ruling party plan to significantly strengthen stewardship code activities by institutional investors to root out the Korea discount and share price suppression in domestic stock markets. The measures include linking institutional compliance evaluations to national pension fund management mandates, revising regulations that have hampered institutional coordination — including the so-called "5% rule" — and launching a "naming and shaming" disclosure system for low price-to-book ratio companies, with the first public announcement scheduled for Nov. 2. A "Korean-style bear hug" bill aimed at curbing share price suppression through enhanced disclosure requirements will also be fast-tracked.
The Democratic Party's K-Capital Markets Special Committee held a working-level party-government meeting at the National Assembly on Tuesday morning to discuss proposed revisions to the inheritance and gift tax law and legislative tasks under the Capital Markets Act to prevent share price suppression.
Oh Ki-hyung, a Democratic Party lawmaker and chairman of the special committee, said the policy agenda rested on two pillars: securing transparency in corporate governance, and improving the stewardship code to strengthen communication between institutional investors and management.
Lawmaker Kim Nam-geun said the committee would pursue compliance evaluations as a core mechanism to systematically promote stewardship activities by institutional investors targeting undervalued companies. "We will assess how pension funds and asset managers have carried out their stewardship duties, and next year, when the national pension fund assigns asset management mandates, those who performed poorly will receive less and those who performed well will receive more — that is how we will invigorate stewardship activities among institutions and pension funds," Kim said.
Legal barriers that have long prevented domestic institutional investors from acting in concert were also put on the agenda. Kim said that while institutional investors in other countries coordinate freely, in Korea even the national pension fund — which holds the largest institutional stake in most companies — cannot decisively influence proxy contests on its own. "In such cases, institutional investors need to exercise voting rights jointly, but we are over-regulating this to the point of imposing criminal penalties if they do so without prior disclosure," he said. "We will reform the system."
Oh echoed the point, citing Japan's experience of using the stewardship code to facilitate dialogue between institutions and long-term investors to address low PBR and discuss more efficient use of capital. "On top of the practice improvements being pursued by the FSC and the Financial Supervisory Service, we will actively push for improvements to the 5% rule under the Capital Markets Act and to the joint-holder regime," he said.
The low-PBR disclosure system, to be implemented through administrative measures, will launch as planned in early November. Oh said the Korea Exchange would roll out the naming-and-shaming disclosure system and make its first announcement of companies' PBR levels between Nov. 1 and Nov. 2, reaffirming the committee's commitment to consistent disclosure reform.
The committee also plans to introduce a Korean-style bear hug mechanism as a market-driven remedy for undervaluation through mergers and acquisitions. Under the proposed system, listed companies that receive acquisition proposals would be required to disclose the details and conditions of such offers, and their boards would be obligated to state their position on any tender offer — making information previously known only to controlling shareholders and the board available to ordinary shareholders as well. "If the books are sound, a low-PBR company is a value stock and an M&A target," Oh said. "We need a system where M&A happens through market mechanisms and low PBR is resolved that way." He added that the committee would amend the Capital Markets Act to mandate disclosure of acquisition proposals so that market participants can make informed decisions, and pledged to build internal party consensus on supplementary measures before the end of the year.
Meanwhile, the special committee also plans to process proposed amendments to the inheritance and gift tax law aimed at preventing share price suppression within the current regular National Assembly session if at all possible.
jiyun@heraldcorp.com