"I got stuck holding shares at the 300,000-won peak." — A Naver investor
Naver's share price has been falling steadily, disappointing investors who bought in expecting gains from the internet giant's joint AI factory project with Nvidia.
On Wednesday, Naver shares closed down 2.49 percent at 196,000 won ($144), slipping below the 200,000-won support level. The stock had previously hit 300,000 won on Nvidia enthusiasm before retreating.
Many investors who bought near the top during the surge are now crying foul.
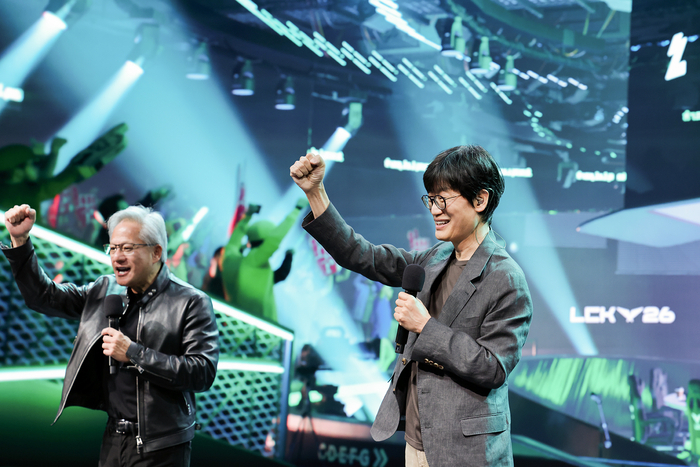
The stock soared after a high-profile meeting between Nvidia CEO Jensen Huang and Naver Chairman Lee Hae-jin captured public attention, only to plunge back toward multi-year lows almost immediately.
"We thought Naver was finally breaking out of its slump after being left behind in the bull market — instead it fell even harder," one Naver shareholder said.
The stock had once drawn predictions that it could rise tenfold to 1 million won, sparking a nationwide buying frenzy. A Naver official had said at the time that reaching a market capitalization of 150 trillion won — implying a share price of 1 million won — was "not so much a goal as a reality to be achieved."
Analysts say concerns about competition from global tech giants and weakening earnings are weighing on the share price.
Mirae Asset Securities estimates Naver's operating profit this year at 2.17 trillion won ($1.6 billion), down 1.7 percent from 2.21 trillion won last year. The operating margin is forecast to narrow from 18.3 percent last year to 15.7 percent this year, with third- and fourth-quarter operating profit expected to fall 3.9 percent and 8.3 percent, respectively, from the same periods a year earlier.
Analysts expect a revaluation of the company once revenue from its AI factory — data center — business begins in earnest.
"Since Naver announced its entry into the AI factory business in June, concrete details have emerged, including Nvidia's participation in a $1 billion rights offering," Lee Hyo-jin, a researcher at Meritz Securities, wrote in a report Tuesday. "However, revenue generation has been pushed to next year, leaving the stock in a momentum vacuum, and investor disappointment has grown over capital deployment whose returns remain unclear."
Lee added that GPU shipments and order disclosures were likely to materialize around the time Nvidia's rights offering payment is due. "Potential customers could expand beyond Anthropic and OpenAI to global cloud service providers that need domestic inference infrastructure," she said.
park@heraldcorp.com