"This has gone too far." — Samsung Electronics and SK hynix investor
"Should I sell now?" — Samsung Electronics and SK hynix investor
Lee Ju-wan, an industry analyst who sparked controversy by setting fair-value share price targets of 70,000 won for Samsung Electronics and 200,000 won for SK hynix, has continued to issue alarming forecasts, stirring fresh debate among investors.
Investors have been left confused, with reactions ranging from "He speaks too carelessly" to "The market is already struggling — this just makes it more frightening" and "Should we even believe this?"
Appearing on YTN Radio on Friday, Lee doubled down on his position, saying both Samsung Electronics and SK hynix "are still in overvalued territory."
He said his 70,000-won and 200,000-won fair-value targets had been his consistent view for the past year.
"It was quiet back then, so I find it strange that it's only becoming a topic now," he said. "Even accounting for future earnings improvements, the price-to-book ratio will still be elevated."
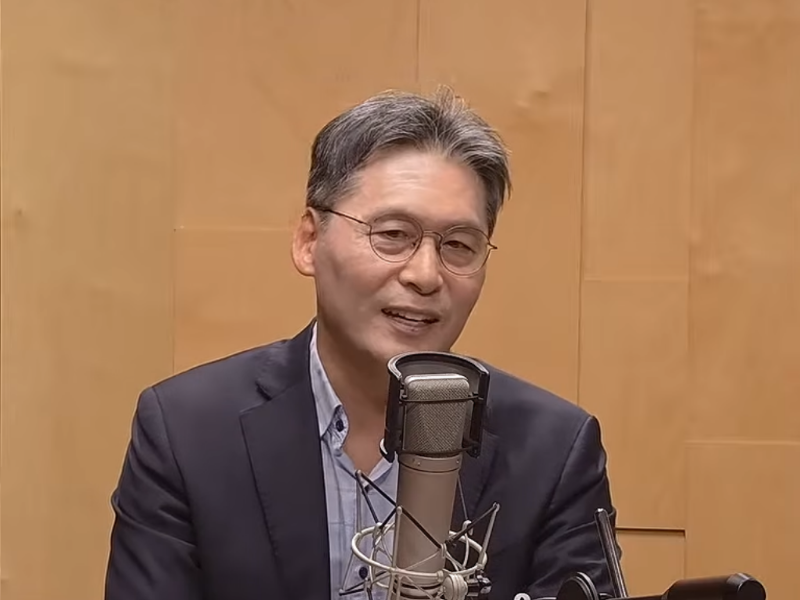
"Volume hasn't increased at all — only prices have risen, and prices cannot rise forever," Lee said. "Nvidia's growth came from volumes expanding more than tenfold, but memory has seen prices alone surge roughly tenfold."
He added that once supply normalizes, prices will inevitably return to where they were, pointing to memory chip prices reverting to pre-April 2025 levels. "That would put the companies back in the red," he said. "Within one to two years, they will almost certainly shrink to a level where losses become a real concern." He went on to say that "the current share price rally is a bubble built on earnings that will vanish like a sandcastle, like a mirage."
Shares of Samsung Electronics and SK hynix have plunged more than 20 percent this month, deepening fear among investors. The prevailing view in the brokerage community, however, is that the recent selloff reflects an excessive correction driven by thin liquidity and weakening investor sentiment in the domestic market, rather than any deterioration in corporate fundamentals.
Kim Dong-won, head of research at KB Securities, wrote in a report that the sharp declines in Samsung Electronics and SK hynix shares "appear to be an excessive correction caused by a liquidity vacuum and weakened investor sentiment in the Korean stock market, rather than any damage to fundamentals."
"Despite the steep share price correction, the earnings outlook for Samsung Electronics and SK hynix is actually being revised upward," Kim said. He added that "the current moment offers more upside potential from valuation normalization than downside risk from further declines."
Experts identified the upcoming earnings releases and shareholder return policies of Samsung Electronics and SK hynix as the key variables that will shape the stocks' trajectory. SK hynix is scheduled to hold its third-quarter earnings conference call on Oct. 28, with Samsung Electronics following on Oct. 29. Samsung Electronics reported preliminary third-quarter consolidated sales of 195 trillion won ($145 billion) and operating profit of 107.4 trillion won on Oct. 8, up 126.59 percent and 782.50 percent, respectively, from the same period a year earlier.
Meanwhile, concerns over AI investment and a sharp rise in international oil prices combined to push all three major Wall Street indexes lower on Friday (local time). A wave of selling concentrated in AI and semiconductor-related stocks dragged the Nasdaq Composite down more than 2 percent. Micron fell 5.63 percent, Broadcom dropped 4.52 percent, AMD slid 5.95 percent, and SK hynix's American depositary receipts declined 6.58 percent.
park@heraldcorp.com