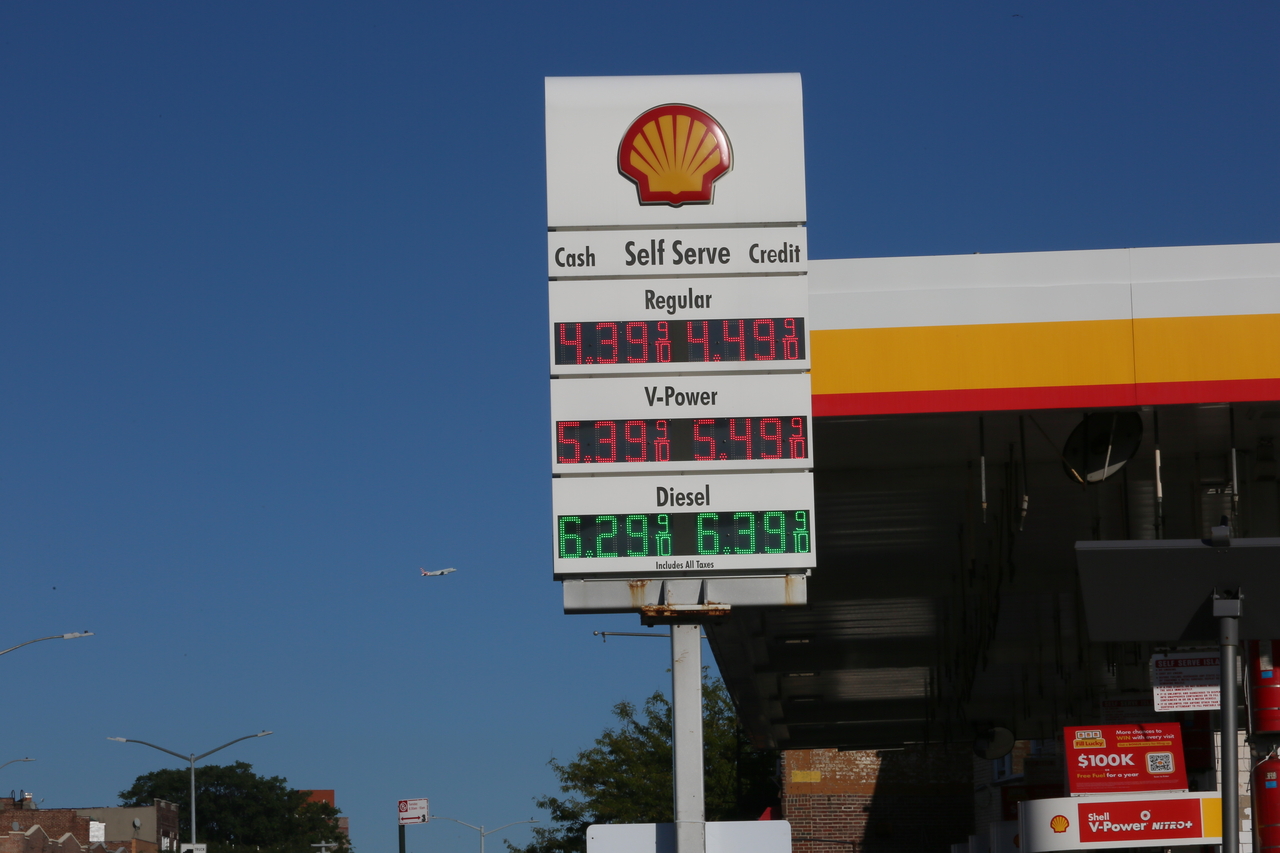
Oil prices, which had surged for two consecutive days to their highest level in four months, reversed course Wednesday (local time), apparently driven by reports that Saudi Arabia is pursuing alternative crude supply routes.
Brent crude futures for November delivery closed down 2.69 percent at $105.83 per barrel on the London ICE Futures Exchange. West Texas Intermediate futures for October delivery settled 3.21 percent lower at $102.43 per barrel on the New York Mercantile Exchange.
Prices had been climbing on growing fears that strikes on Saudi Arabia's east-west pipeline and a Houthi blockade of the Red Sea would disrupt supplies. The rally eased Wednesday after reports emerged that Saudi Arabia is exploring maritime rerouting options. Reuters, citing sources, said Saudi Aramco had offered Asian long-term contract buyers additional crude transshipment at sea near Oman's Port of Sohar.
Weekly crude and refined product inventory data from the US Energy Information Administration also weighed on prices. Contrary to market anxiety, the drawdown in crude stockpiles was smaller than expected, while inventories of refined products such as gasoline and diesel actually increased. The data suggested the crude and refined product markets are holding up better than feared, helping temper the recent price surge.
Geopolitical tensions surrounding the Middle East, reduced traffic through the Strait of Hormuz, and disruptions at major oil-producing countries and refining facilities remain unresolved, however, and sharp price swings are expected to continue for now.
kate01@heraldcorp.com