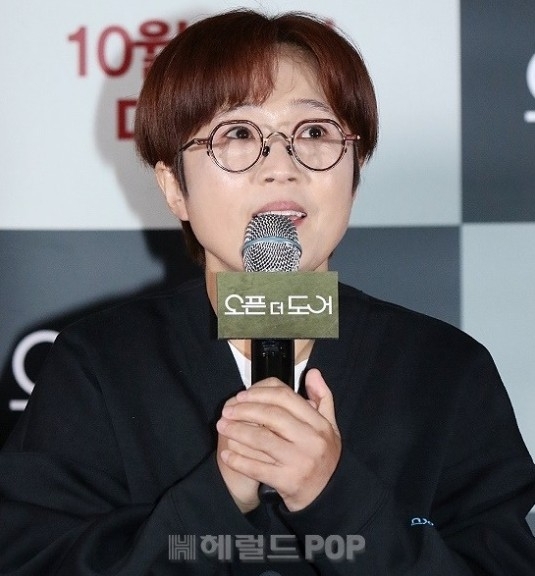
Broadcaster Song Eun-i has drawn attention after revealing that the cumulative return on a pension savings product she has held since 1993 has surpassed 30 percent.
In a video titled "Song & Sook Reveal Their Investment Returns: Where Do Securities Firm Employees Invest?" posted on the YouTube channel Vivo TV on Wednesday, Song and fellow broadcaster Kim Sook each revealed their investment portfolios and returns.
Before her phone call with a securities firm employee, Kim said, "My ETF return right now is minus 37 percent," expressing frustration over her recent investment losses.
In response, Song said, "My pension savings return was recently reported in an article, but cumulative returns are different from short-term returns. Right now, my cumulative return is in the 30 percent range."
Kim protested, "Mine is minus 37 percent — are you bragging?" to which Song replied, "That is because it is cumulative — cumulative," emphasizing that hers was a long-term investment.

Song has previously drawn attention on various broadcasts for revealing that she does not invest in stocks at all, opting instead for a habit of consistent saving.
She said, "In 1993, when I was earning a monthly salary of 200,000 won ($149), I signed up for a bank pension savings account. The bank keeps recommending that I cancel it, but I never will. Just looking at the interest rate makes me happy," a remark that drew wide attention at the time. The interest rate then was as high as around 20 percent.
However, Song drew a line against speculation that the financial product had made her considerably wealthy.
She explained, "I signed up at the time to receive tax benefits and a pension. Of course, the interest rate is much higher than savings accounts today, but the amount is not large. It looks to people as if my retirement is all set because of that account, but that is not the case."
She added, "I have kept the account without breaking it. The interest rate was in the 20 percent range back then, but it has since depreciated to the 10 percent range," and said, "What matters is that I kept doing it consistently."
Song's pension savings return illustrates the true value of long-term investment that many experts have emphasized.
John Lee, former CEO of Meritz Asset Management, advises retail investors who want to build wealth but do not know where to start. He recommends they first sign up for a pension savings fund. Depending on income, contributions of up to 6 million won a year qualify for a tax credit of 13.2 to 16.5 percent. Additional benefits include tax deferral and lower tax rates.
In a recent YouTube broadcast, he also said, "The best time to invest is today. Do not hesitate — open an account right away. In particular, if you do not have a pension savings fund account, open one and start investing."
Pension savings reserves near W200tr last year, returns at 10.6%
The Financial Services Commission and the Financial Supervisory Service released the "2025 Pension Savings Investment White Paper" in June. It showed pension savings reserves reached 198.2 trillion won last year, up 10.8 percent from 178.9 trillion won the previous year.
The overall return on pension savings products stood at 10.6 percent. By product type, pension savings funds and ETFs posted the highest return at 29.3 percent, followed by pension savings trusts at 4.0 percent and pension savings insurance at 0.8 percent. Broken down further, the annual return was 31.3 percent for funds and 27.4 percent for ETFs. The cumulative return stood at 8.1 percent for funds and 19.9 percent for ETFs.
The share of pension savings funds among all pension savings products also grew, rising from 17.6 percent in 2023 to 22.7 percent in 2024 and 30.9 percent last year.
The total number of pension savings subscribers reached about 8.4 million last year, up 761,000, or 10.0 percent, from the previous year. By age group, those in their 40s and 50s accounted for more than half of all subscribers at 50.5 percent, the largest share. The fastest growth rate was seen among those under 20, at 53.4 percent.
Financial authorities said subscribers across all age groups have continued to increase since a 2023 revision to the Income Tax Act expanded the scope of the tax credit.
Caution is needed when signing up for pension savings products. If the principal that received a tax credit and any investment gains are withdrawn early, the withdrawal is treated as a non-pension payout. It is then subject to other income tax of 16.5 percent.
betterj@heraldcorp.com