AI rate-cut service benefits 162,000 users, saving 100.3 billion won in interest
Scope to expand to debt restructuring, refinancing and policy fund applications
Self-employed and small-business owners to be included; virtual assets and policy finance data to be linked
Pilot program under innovative finance designation considered ahead of Credit Information Act revision
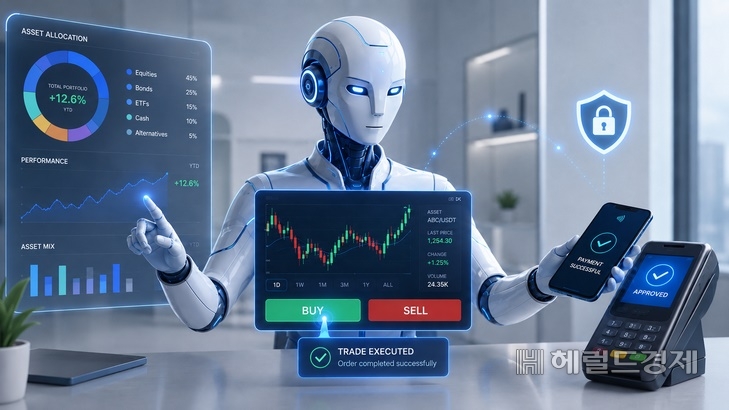
South Korea's financial authorities are pushing to expand the MyData service — which currently aggregates bank accounts and card transaction histories in one place — into a platform where AI acts on behalf of consumers to carry out financial tasks. The core of the plan is to extend AI-powered proxy services beyond the existing interest-rate reduction request system to cover debt restructuring, loan refinancing, policy fund applications and voice-phishing damage relief.
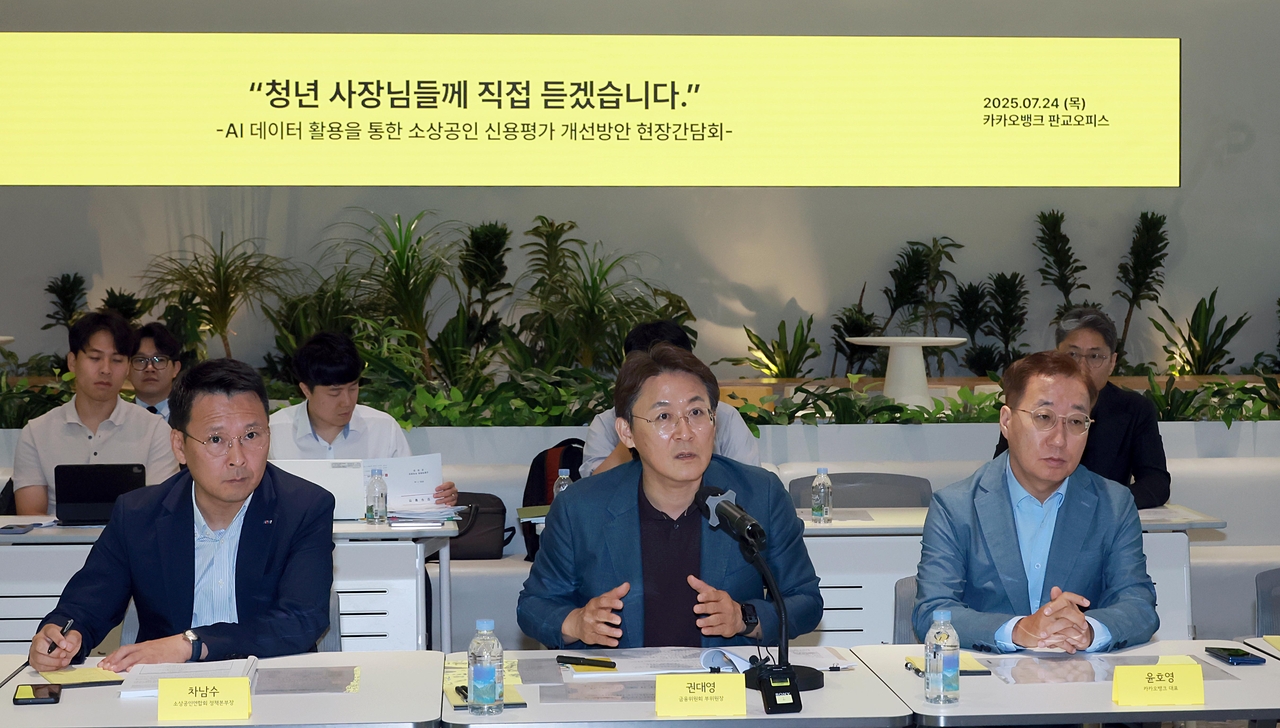
The Financial Services Commission held the second meeting of its Personal Credit Information Consent System Reform Legal Advisory Panel on Tuesday, chaired by FSC Vice Chairman Kwon Dae-young, and unveiled the "MyData Development Plan for the AI Era." The FSC plans to expand MyData eligibility beyond individuals to include sole proprietors and small-business owners, and to revise data regulations to better accommodate AI use.
From rate cuts to policy funds and debt restructuring
The centerpiece of the overhaul is broadening MyData's function from information retrieval and analysis to the actual execution of financial transactions. Under the current system, even when users check their asset and loan status or receive product recommendations, they must still complete separate authentication and application steps on their own.
AI-driven proxy execution is already underway for interest-rate reduction requests. After 18 MyData operators received innovative financial service designation in December last year, about 4.07 million people had signed up for the service through July this year. Of those, 162,000 users received actual rate reductions, saving a combined 100.3 billion won ($72.6 million) — an average of 610,000 won per person.
The FSC plans to expand the range of rights that MyData operators can exercise on behalf of users. Eligible proxy tasks could include debt restructuring requests, voice-phishing damage relief applications, policy fund and loan refinancing applications, and searches and claims for unclaimed insurance payouts. For example, the system would identify suitable policy funds for a user, prepare required documents such as tax payment records and income verification, and complete the application on their behalf.
The consent framework for AI proxy execution will also be revised. The FSC is pursuing a system that allows advance blanket consent when the purpose, scope, method and duration of a service are clearly defined. However, broad consent covering vague terms such as "all service provision" or "all affiliated services" will not be permitted.
Expansion to sole proprietors; virtual assets and policy finance to be linked
The FSC is also pushing to extend MyData eligibility to sole proprietors and small-business owners. Under the current Credit Information Act, only individuals hold the right to request the transfer of their own credit information, limiting the ability of sole proprietors to consolidate and manage business-related data.
The FSC plans to amend the law to expand the subjects of the data transfer right and the scope of MyData information provision to cover "all credit information subjects." Once introduced, the available data would go beyond financial information such as loans and card records to include sales and payment figures, tax and national insurance payment histories, business registration and suspension or closure records, and utility payment histories.
The types of information handled through MyData will also be broadened beyond conventional financial data from banks, card companies and insurers to include virtual assets and policy and microfinance information. Financial holding company subsidiaries and strategic partners will be allowed to share data within defined parameters, provided they clearly disclose in advance the purpose of use, the categories of information involved and their management responsibilities.
Given that AI will be executing financial transactions on behalf of users, safeguards will also be put in place. New obligations will require AI to record and explain to consumers the reasons behind each action it takes, the information it used, and the details and outcomes of what it did. Guidelines covering data combination and security standards will also be established.
The key measures in the plan are not immediately enforceable, as they require amendments to the Credit Information Act and its enforcement decree.
The FSC said it will gather broad input from financial consumers, the financial industry, relevant institutions and experts before drafting a Credit Information Act amendment and moving swiftly to push it through the legislative process. It added that even before the law is revised, it will actively consider allowing qualifying operators to run pilot programs through the innovative financial service designation process, subject to review.
rim@heraldcorp.com