"We are meeting not only home-appliance companies but also online and offline retailers. It is not uncommon for companies to reach out first to inquire about digital asset business cooperation."
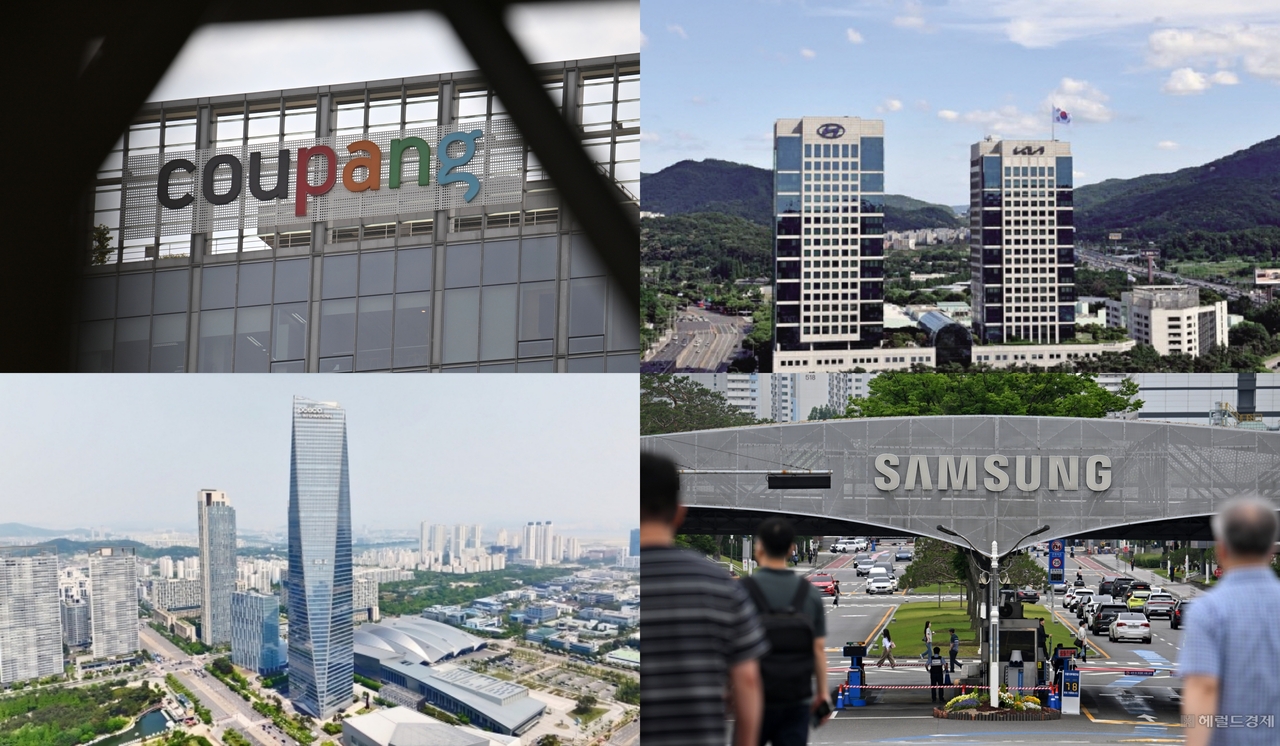
An official at one of South Korea's five major financial holding companies made that assessment Wednesday, describing the level of corporate interest in stablecoins. What began as passing curiosity in the early stages of regulatory discussions has evolved into something more concrete: Coupang Inc, POSCO International, Hyundai Motor and Samsung Electronics are each actively identifying stablecoin applications suited to their own businesses — spanning payments, settlement and trade finance. Industry observers say companies have begun treating digital assets not merely as a topic of interest but as a piece of business infrastructure, and are starting to integrate them into actual operations.
Coupang Inc, with 49 trillion won ($34.6 billion) in annual sales, pursues fee savings through digital assets. For retail platform companies, the areas of greatest interest in stablecoins are payments and settlement. Because they already have large user bases, merchant networks and proprietary payment infrastructure, retail platforms have relatively more points of contact where stablecoins can be grafted onto existing operations. For a large platform like Coupang Inc, even a modest improvement in payment and settlement efficiency can translate into significant cost savings given the sheer volume of transactions.
A recent proof-of-concept conducted by Woori Bank and Coupang Inc focused on confirming exactly that potential. The two companies tested a process in which a won-denominated stablecoin was used to settle payments to merchants based on Coupang Eats orders, and also verified an on/off-ramp function that converts between won and stablecoins across bank accounts and digital wallets.
Two specific scenarios were tested. The first used the existing credit card payment network as-is, applying stablecoins at the settlement stage when paying merchants — essentially examining whether an off-chain payment network could be linked to blockchain-based settlement.
The second processed everything from payment to settlement entirely in stablecoins. Merchants received payment in stablecoins, which could then be used for further transactions, creating an on-chain circulation of funds. Woori Bank handled the conversion between won and stablecoins by linking bank accounts to digital wallets.
This was not the first stablecoin pilot built around a delivery app. Shinhan Bank verified related payment technology in December last year using the Ddaenggyeoyo app. At the time, a structure was designed to link stablecoin payments to offline transactions together with a domestic retailer, but the pilot reportedly did not progress to live testing with actual merchants.
Woori Bank and Coupang Inc similarly used simulated rather than real merchants in their proof-of-concept to demonstrate the stablecoin payment and settlement process. The pilot used Tempo, a layer-1 blockchain in which Coupang Inc has invested.
Industry observers point to transaction fees as the primary reason retailers are drawn to stablecoins. For large retail platforms, even fees of around 1 percent accumulate into a substantial cost, so the prospect of reducing them is a strong incentive for adoption. "With 49 trillion won in sales, even a 1.8 percent fee adds up to a considerable sum," one industry expert said. "For retailers, the biggest advantage is the ability to cut financial fees."
Easy integration with existing points and mobile payment infrastructure is another draw. Retailers already have their own customer touchpoints — points apps, barcode payments and the like — reducing the burden of building separate channels. Companies with significant overseas operations in Southeast Asia or Japan also see potential to move beyond the limitations of domestic-only points programs, extending stablecoin use to payments and settlements with overseas affiliates.
"From the user's perspective, the experience would not be much different from using existing points," one retail industry official said. "You could design a structure that keeps the existing app and barcode payment method intact while simply switching the underlying payment instrument to a stablecoin on the back end."
POSCO International eyes on-chain trade finance. Unlike retailers, general trading companies are focused on overseas remittances and trade finance. Given the nature of a trading company with numerous overseas subsidiaries and counterparties, consolidating transaction and settlement data scattered across countries into a single ledger — and digitizing the accounts receivable generated in the trade process — could significantly improve operational efficiency.
POSCO International has recently been running a series of pilots using different blockchain networks to verify this potential. In a proof-of-concept conducted with LG CNS, the company used the layer-1 blockchain Injective to test a structure for issuing, transferring, settling and managing trade receivables as digital assets. The pilot used dummy assets to build out a full process from receivables issuance through asset management. It also implemented a system in which the head office, overseas subsidiaries and counterparties share transaction data in real time on a shared ledger, and applied AI to the review of letters of credit and trade documents.
Separately, POSCO International is building a blockchain-based overseas remittance and payment infrastructure with Hana Financial Group and Dunamu. The setup records overseas remittance transactions on Dunamu's GIWA chain and links them to Hana Bank's foreign exchange account system. Actual funds move through the existing bank payment network, but remittance instructions and transaction status are shared on the blockchain — a structure similar to JPMorgan's institutional blockchain payment network, Kinexys.
Last year, POSCO International signed an MOU with Kinexys to introduce a blockchain-based payment network. The two sides examined a plan to process the roughly 40,000 overseas remittances the company handles annually in real time, cutting what had been a one-to-two-day transfer window to a matter of minutes.
The market views this as part of a broader push by POSCO International to digitize its existing trade finance operations. Having long been active in financing involving letters of credit, trade payments and accounts receivable, the company's move into blockchain-based overseas remittances and receivables tokenization is seen as a natural extension of its core business.
Looking ahead, there is also talk of eventually connecting receivables tokenization with the overseas remittance and payment infrastructure into a single integrated flow — issuing and managing trade receivables on-chain, using them as a basis for funding, and then linking payment and settlement to the blockchain as well.
Trade finance does, however, involve large transaction volumes, making processing speed, fees and scalability critical. Meeting the regulatory requirements of multiple countries simultaneously is another key challenge. "POSCO International has more than 80 overseas bases outside Korea, so domestic regulation alone cannot be the only consideration," one industry official said. "Infrastructure that can accommodate the compliance requirements of each country is essential."
Hyundai Motor Group is also continuing stablecoin pilots with commercialization in mind. With factories spread across the globe, the effort has the clear character of preparing for real-world stablecoin use in inter-subsidiary remittances.
The first remittance proof-of-concept took place between Hyundai Motor's US and Mexico subsidiaries. The US unit sent $20,000, which was converted into the dollar-backed stablecoin USDT, transferred to Mexico and then converted back into dollars. The entire process, including remittance and verification, took an average of seven minutes. Participants included Hyundai Card, Hyundai Motor's US and Mexico subsidiaries, Tether, Avalanche and blockchain payment infrastructure firm Axiym.
A notable feature of the proof-of-concept was that Hyundai Motor's overseas subsidiaries did not directly hold or handle stablecoins. Axiym has the authority to mint or procure USDT through a direct link with Tether, so stablecoins were used only at the stage of moving funds between Axiym's wallets.
Hyundai Card and Hyundai Motor also used the pilot to review the regulatory requirements that would be needed for actual commercialization — including accounting, tax, legal and internal control considerations at the overseas subsidiaries. The decision to adopt a structure in which the subsidiaries do not directly hold stablecoins is understood to reflect a desire to reduce the regulatory burden of corporate digital asset holdings while still confirming improvements in remittance speed and cost.
Hyundai Card announced last month that it is moving into a second proof-of-concept targeting Hyundai Motor's overseas subsidiaries in Europe. This round will use not only dollars but also local currencies, and will examine the costs incurred during currency conversion to assess the real economic viability of stablecoin remittances. Countries where Hyundai Motor has production bases — including the Czech Republic — are being mentioned as likely pilot locations.
Samsung Electronics has recently joined a global dollar stablecoin project as it explores related business opportunities. Market experts say the company's existing device and payment infrastructure — Galaxy smartphones and Samsung Wallet, already in the hands of a massive user base — positions it to serve as a key channel if stablecoins become widespread.
In June, Samsung Electronics joined the OpenUSD (OUSD) consortium, which counts more than 140 global companies including Visa and Mastercard among its members. OUSD drew attention by proposing a structure in which interest generated from reserves is shared with participating companies rather than kept exclusively by the issuer. Some observers suggest this model could affect the market position of Circle, the issuer of USDC, the world's second-largest dollar stablecoin.
Industry insiders point to Samsung Electronics' broad proprietary business areas connectable to payments as the backdrop for its OUSD participation. With products sold worldwide spanning home appliances, smartphones and semiconductors, integrating stablecoins into payments and remittances could reduce the time and cost of moving funds, they say.
"Samsung is a company that has been preparing for the digital asset business for a long time," one financial investment industry official said. "It is worth paying attention to the fact that it already has the devices and pay platform capable of using already-issued stablecoins." The official added: "Just as you register a credit card in Samsung Wallet to make payments, you could envision a structure where stablecoins are received in the wallet and connected to payments."
Samsung Electronics announced at the Galaxy Unpacked 2026 event in London last month that it would add stablecoin functionality to Samsung Wallet. Lee Dinham, a product manager at Samsung Electronics, said it would be "one of the first cases of a major mobile brand natively integrating stablecoins into a smartphone."
Samsung has also held meetings with domestic financial institutions and blockchain infrastructure companies to discuss digital asset business. "Samsung Electronics has a powerful user touchpoint in its mobile devices and wallet, giving it high utility in the payments space," one industry official said. "With many global production bases as well, it could over the long term expand its scope to cover payments between overseas subsidiaries or B2B fund transfers."
Even so, observers note that for ordinary companies to move into digital asset businesses in earnest, regulatory frameworks must come first. They say the momentum behind discussions on a basic digital assets act stalled around the local elections, pushing the legislative schedule back by more than six months and taking some of the wind out of corporate efforts.
"From last year through early this year, we received a lot of inquiries from general companies about related business," one commercial bank official said. "But with legislation delayed, the atmosphere is not as actively focused on exploring digital asset business as it once was."
kyoung@heraldcorp.com