FSC and banks begin working-level talks on long-term fixed-rate home loans
New product seen as tool to improve household debt quality by shielding borrowers from rate hikes
Covered bond incentives and other bold measures expected to win over lenders
Banks' resistance may soften as variable rates climb above fixed-rate levels
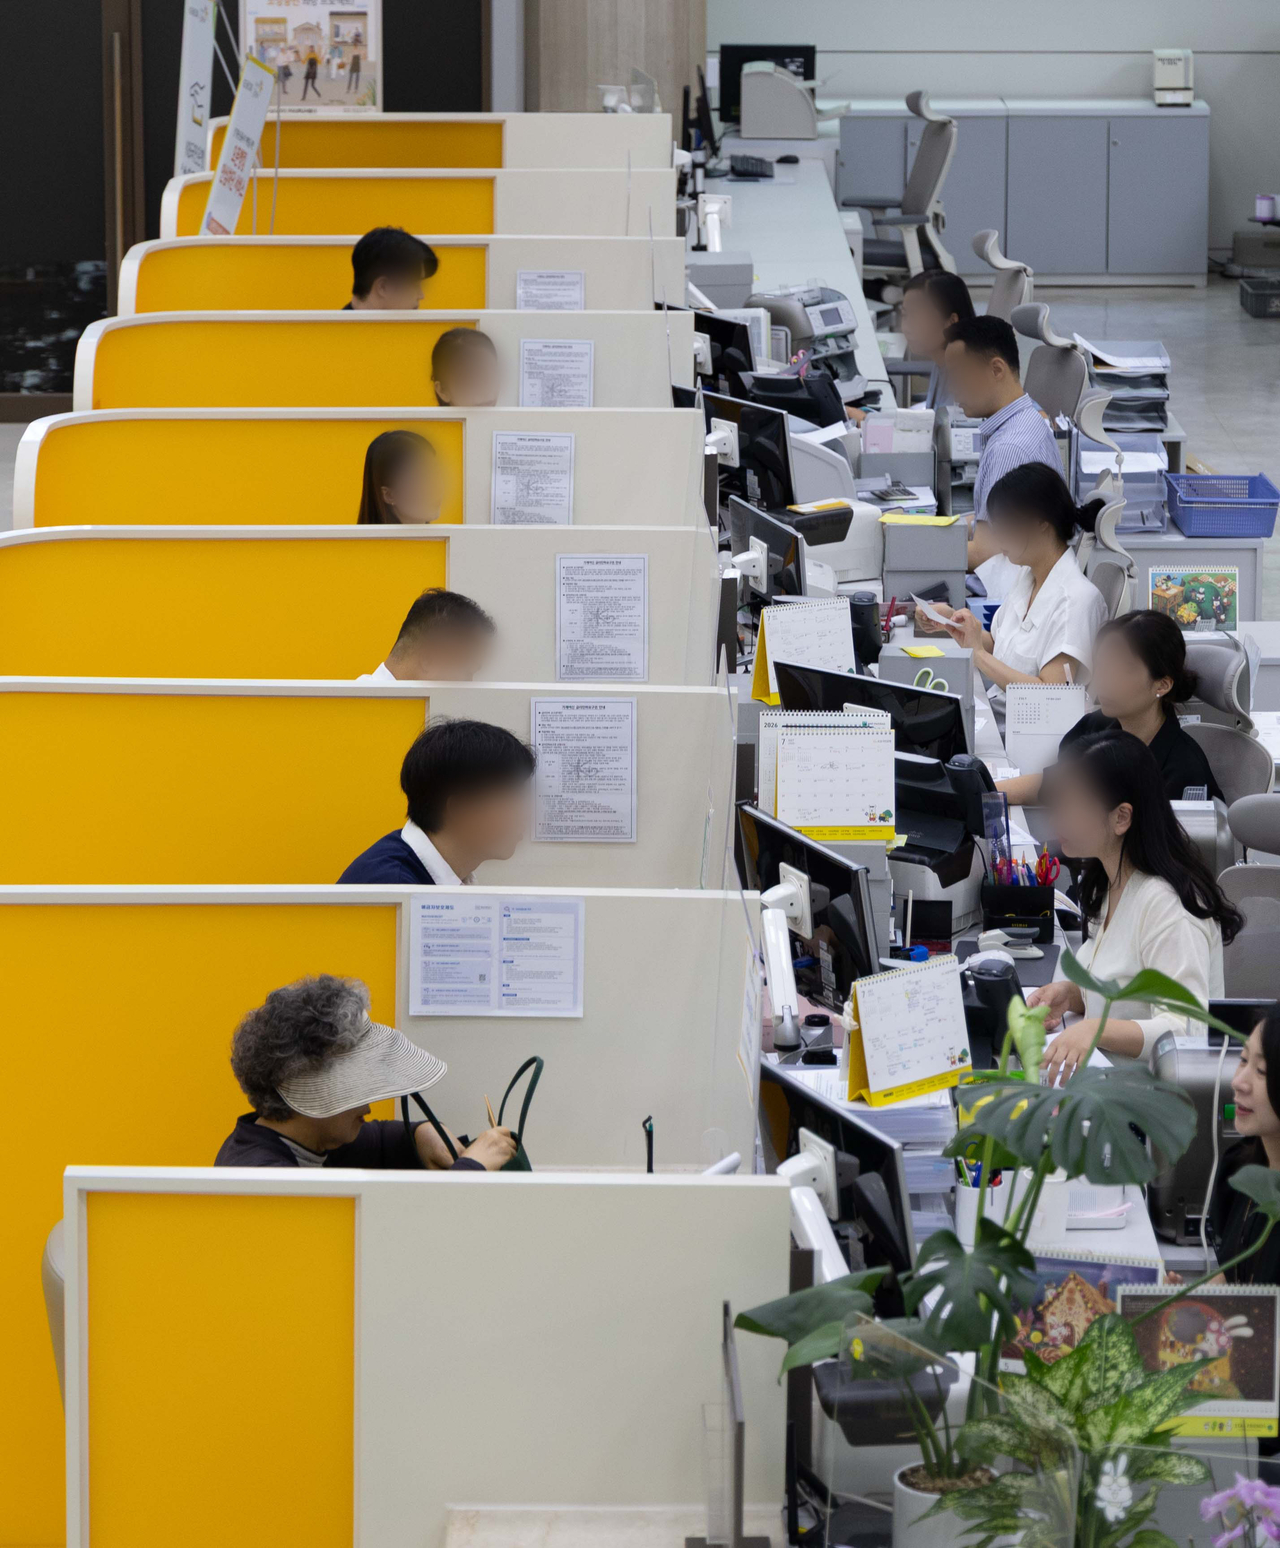
A long-term fixed-rate mortgage that locks in an interest rate for at least 10 years is set to hit the market as early as next year. Financial authorities plan to finalize an incentive package with banks by year-end to encourage lenders to offer the product — and their task may be getting easier, as variable rates have recently begun to exceed fixed rates in some cases, weakening the banking sector's main argument against the new loan type.
The Financial Services Commission held a working-level meeting with bank officials last week to discuss the launch of long-term fixed-rate home loans, according to financial industry sources. At the meeting, the FSC asked banks to offer mortgages benchmarked to bank bonds with maturities of at least 10 years. The FSC is targeting an early next year launch and plans to resume talks once the National Assembly's budget deliberations wrap up.
"There was a request that the fixed-rate period be at least 10 years, while allowing each bank to tailor the specifics to its own circumstances," a commercial bank official said.
Currently, fixed-rate mortgages at most banks reset every five years, as they are benchmarked to five-year bank bonds. The long-term fixed-rate product the FSC has in mind would use 10-year bank bonds as the benchmark, extending the rate-lock period to a full decade.
Promoting long-term fixed-rate mortgages has long been a priority for the FSC. South Korea's household debt stood at 90.5 percent of GDP at the end of 2024, and any rise in interest rates would significantly increase the repayment burden on borrowers. The FSC believes that giving borrowers the option to lock in a rate and avoid interest rate risk would meaningfully improve the quality of the country's household debt.
President Lee Jae-myung also flagged the risk at a press briefing in October, warning that borrowers who took out fixed-rate mortgages could face repayments 2.5 times higher than their original interest costs if their rates were converted to variable terms.
The FSC aims to finalize an incentive plan with banks by year-end to promote the product. Banks have long been reluctant, arguing that long-term fixed-rate loans carry higher rates than five-year fixed products — dampening borrower demand — while saddling lenders with greater funding management risk. Currently, only Shinhan Bank and Industrial Bank of Korea offer such products.
The most likely incentive under consideration is an additional improvement to the covered bond activation measures the FSC announced in 2024.
When a bank issues covered bonds backed by long-term fixed-rate mortgages, Korea Housing Finance Corp. provides a payment guarantee to lower the bank's funding costs. Under the earlier plan, the FSC agreed to give additional credit to covered bond balances when calculating banks' won-denominated loan-to-deposit ratios; the new package is expected to raise that credit further.
The FSC also created a re-securitization program allowing Korea Housing Finance Corp. to purchase covered bonds issued by banks, and further improvements to that program are also expected. As of now, the corporation has yet to complete a single covered bond re-securitization transaction.
Given the FSC's strong push for long-term fixed-rate mortgages, the talks could yield unusually generous incentives capable of moving the banking sector. "Ultimately, the discussion will center less on what the authorities are willing to give and more on what the banks want to receive," one financial authority official said.
The case for banks to resist has also weakened as long-term rates have fallen. According to the Korea Financial Investment Association, the spread between five-year and 10-year bank bond yields stood at 0.236 percentage points on Monday — narrower than the peak of 0.407 percentage points recorded on May 18.
Demand for fixed-rate products is also recovering. Data from the Bank of Korea's economic statistics system show that fixed-rate mortgages accounted for 75.6 percent of newly extended bank home loans in January, fell to 31.9 percent in July, and rebounded to 34.2 percent by September.
The trend is expected to continue. The new COFIX — the benchmark for variable-rate mortgages — has been rising sharply as year-end approaches, driven by intensifying competition among banks for deposits. According to the Korea Federation of Banks, the new-business COFIX for October came in at 3.62 percent, up 0.19 percentage points from the previous month — the highest level since February 2024 and a gain of 0.44 percentage points over just two months.
As a result, two of the four major banks — KB, Hana, Woori and NH — that offer new COFIX-linked mortgages now have variable rates exceeding their fixed-rate equivalents, as of Tuesday.
"Even if the product sees limited use during the current rate-hike cycle, expanding borrowers' options in preparation for the next period of rising rates is meaningful in itself," one financial industry official said.
hyuk@heraldcorp.com