Tiered basic deductions based on residency could deepen Greater Seoul concentration; long-term holding deduction overhaul raises concerns over market freeze and taxpayer trust
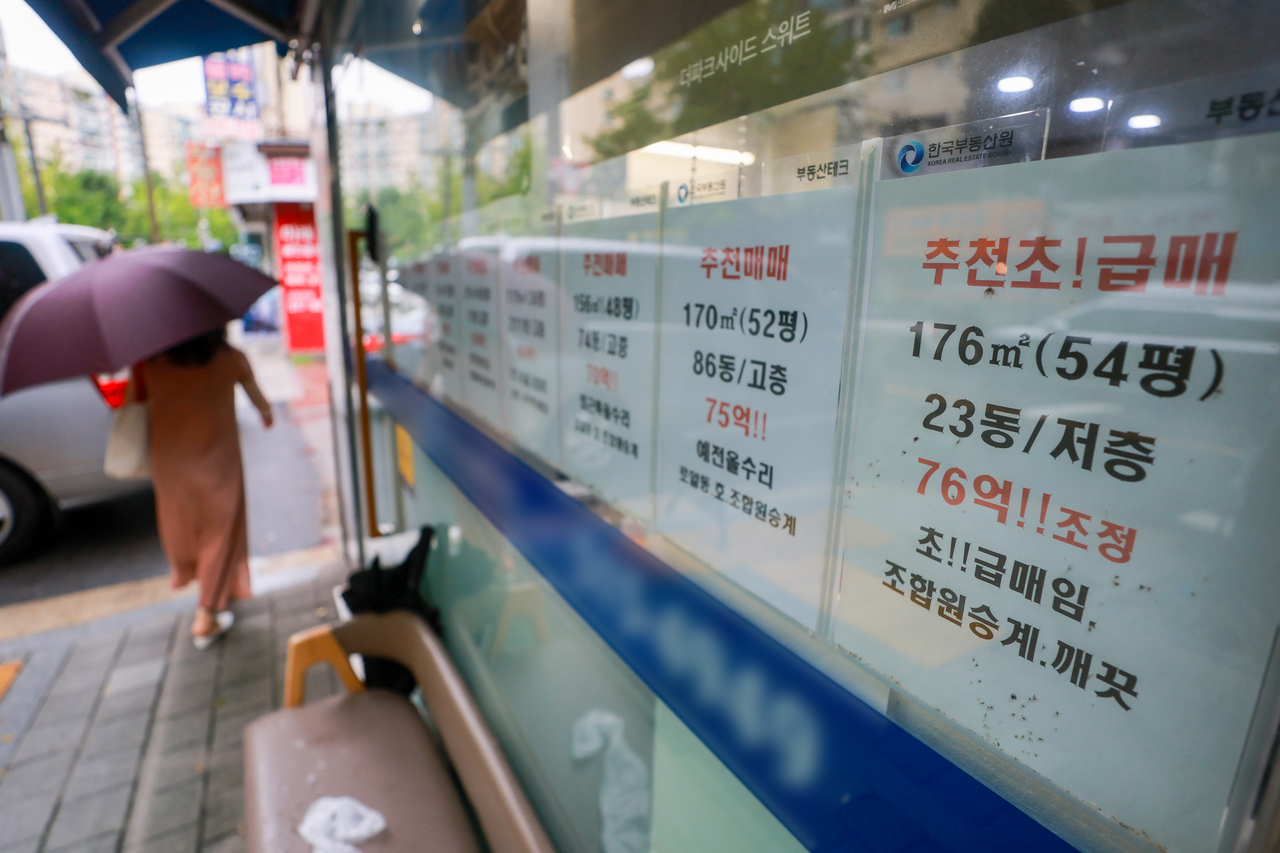
The National Assembly's Finance and Economy Planning Committee has warned that raising the comprehensive real estate tax rate on housing could push the tax burden onto tenants by driving up rents, potentially distorting the jeonse and monthly rent market.
The committee laid out the concerns in a legislative review report on tax bills, issued under the name of Chief Research Officer Lee Jeong-eun, according to tax authorities and political circles Sunday.
"A heavy property-holding tax burden on multi-home owners raises costs for landlords, which could be passed on to tenants in the form of higher rents," the committee said in the report. "This could, contrary to the policy's stated goals, increase tenants' housing costs and distort the jeonse and monthly rent market."
The committee also flagged concerns that higher rates on single-home owners could restrict economic freedom and freedom of residence "regardless of the policy objective of reducing housing concentration."
The proposed amendment to the comprehensive real estate tax law would unify the tax rate structure based on assessed home value and raise rates above current levels for brackets exceeding a taxable base of 600 million won ($453,000).
The rate for the bracket between 600 million won and 1.2 billion won — currently set at 1.0 percent — would rise to 1.3 percent from 2028. For the four brackets above 1.2 billion won, owners of two or fewer homes would see rates increase by 0.7 to 2.3 percentage points.
The committee noted that because the comprehensive real estate tax is levied on asset values rather than realized income, it "could compound a tax burden that is disconnected from a taxpayer's short-term income and cash flow," raising the possibility of tax resistance or policy outcomes that diverge from expectations.
"Higher holding costs from a rate increase should theoretically push home prices down," the committee said, "but because home prices are shaped by many factors beyond tax burdens — including interest rates, income, housing supply and financial conditions — the policy effect of a rate hike could be diluted and may not materialize fully when expected."
On the bill's plan to set differentiated basic deduction amounts based on whether a taxpayer lives in the home, the committee said consideration should be given to "the possibility that supply in the Greater Seoul jeonse and monthly rent market could shrink and rents rise, passing the tax burden onto tenants, and that the concentration of population in the Greater Seoul area could intensify."
The amendment sets the basic deduction for multi-home owners using the formula: 500 million won multiplied by the ratio of the owner-occupied home's value to total home value, plus 400 million won. The committee noted this formula could incentivize multi-home owners to live in relatively more expensive homes in the Greater Seoul area in order to maximize their deduction.
"This could deepen the concentration of people in the Greater Seoul area and further reduce supply in the jeonse and monthly rent market there," the committee said. "Reduced supply could push rents higher, and landlords may pass their increased tax burden on to tenants through higher rents."
The committee also warned that a plan to raise the floor for the fair market value ratio — which affects the taxable base — from 60 percent to 70 percent "could, combined with the rate increase, excessively raise the tax burden on asset-rich but income-poor households with limited cash flow."
However, the committee assessed that raising the basic deduction for owner-occupants of a single home "should ease the tax burden on those who own relatively modest properties." It also conveyed the view of supporters of the amendment, who expect the differentiated deduction structure to help curb speculative real estate demand.
The government has also proposed an income tax overhaul that would convert the long-term holding special deduction — which currently allows up to an 80 percent deduction when a single-household homeowner sells a property — into a long-term residency income deduction, and cap the currently unlimited deduction at 1 billion won starting in 2029.
The report also addressed the expected effects and potential side effects of the long-term holding deduction overhaul.
The committee said supporters could argue the change promotes owner-occupancy and improves tax equity, but it raised the possibility of adverse effects, warning the reform "could chill real estate transactions and reduce the supply of listings on the market."
From 2029, when the holding deduction would be eliminated, non-residents worried about higher capital gains taxes might delay selling in order to accumulate residency periods, while others hoping for a future increase in the deduction cap might also hold off — creating a freeze effect and potentially reducing the supply of rental and for-sale properties, the committee said.
The committee conveyed the view that the government's proposal "fails to protect the legitimate expectations and trust of taxpayers who have held real estate for a long time in anticipation of the long-term holding deduction," and highlighted options such as extending the grace period before the changes take effect.
The committee also recommended that when reforming the comprehensive real estate tax and the long-term holding deduction to favor owner-occupants, policymakers should account for those unable to meet residency requirements due to unavoidable circumstances such as work or study obligations.
The committee also weighed in on non-real estate tax bills. It assessed that raising the cap on the family business inheritance deduction from the current 60 billion won to 100 billion won could weaken the redistributive function of the inheritance tax and deepen the regressive nature of the tax system by disproportionately benefiting heirs inheriting large businesses.
On a proposal to shift the childbirth and adoption tax credit from a tax support measure to a fiscal support program under a future response fund, the committee said stable operation would be difficult to guarantee because funding would depend on tax revenue conditions.
The committee also analyzed a proposed new "productive finance" ISA, finding that its benefits could be concentrated among subscribers with greater financial capacity.
oskymoon@heraldcorp.com