Foreign net selling of SK hynix tops 91 trillion won this year, surpassing Samsung Electronics
SK hynix faces triple headwind: profit-taking, Solidigm listing rumors, buyback end
Markets eye additional shareholder returns at Oct. 28 earnings release
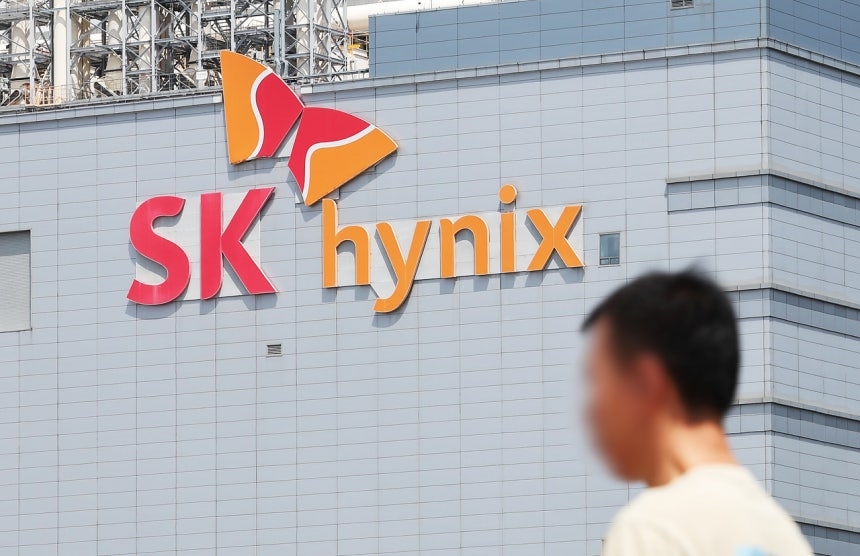
SK hynix is facing a triple headwind ahead of what is expected to be a record-breaking earnings report: mounting foreign selling pressure, speculation over a US stock market listing by its subsidiary Solidigm, and the imminent end of its share buyback program. Profit-taking has intensified as the company's share price has surged more than 90 percent since the start of the year, while concerns over a holding-company-style discount tied to a potential Solidigm listing have emerged and the buyback that has underpinned the stock nears its conclusion. Foreign investors' cumulative net selling of SK hynix this year has now overtaken that of Samsung Electronics — the first such reversal in roughly eight months since Feb. 13.
According to Korea Exchange data released Friday, foreign investors had net sold more than 91 trillion won ($67.5 billion) worth of SK hynix shares from the start of the year through Thursday. That surpasses the roughly 89 trillion won in net selling recorded for Samsung Electronics over the same period. SK hynix first overtook Samsung Electronics in cumulative foreign net selling on Oct. 7.
Although foreign selling has continued in both stocks this month, the pressure on SK hynix has been notably heavier. Over the past seven trading sessions, foreigners sold SK hynix at 1.5 times the rate of Samsung Electronics — net selling more than 6 trillion won of SK hynix compared with 4 trillion won of Samsung Electronics during that period. SK hynix shares fell 29 percent over the same stretch, outpacing Samsung Electronics' 24 percent decline.
Analysts say the concentrated foreign selling ahead of what is expected to be a historic earnings result reflects both profit-taking after a steep run-up and elevated performance expectations. SK hynix shares have gained more than 90 percent since the start of the year, outpacing Samsung Electronics' rise of more than 70 percent.
Industry observers lean toward the view that the widening valuation discount on SK hynix stems more from Korea-market-specific factors than from any deterioration in the memory chip cycle. Forecasts point to a record quarterly profit driven by demand for HBM and other AI semiconductors ahead of the third-quarter earnings release on Oct. 28, but foreign investor flows have not recovered since the Chuseok holiday, and speculation about a Solidigm US listing has stoked fears of a holding-company discount.
The debate over a Solidigm listing presents a dilemma between raising capital and protecting existing shareholder value. Proceeding with a listing would secure external funding for business expansion, but having the subsidiary valued separately could weigh on SK hynix's own valuation. "If Solidigm does not list, SK hynix's capacity to raise funds would shrink and the scale of shareholder returns could fall," said Kim Jun-young, an analyst at iM Securities. "It is a no-win situation in which the structural discount is difficult to resolve either way."
The 40 trillion won share buyback and cancellation program, which entered its final stage in mid-October, could also add near-term supply pressure as the buying demand that has supported the stock's floor disappears once the program ends. Markets are watching for additional shareholder return measures to be announced alongside the third-quarter results on Oct. 28. SK hynix has previously stated its intention to return more than 50 percent of cumulative free cash flow from 2025 through 2027 to shareholders.
Some analysts argue that share cancellations alone have limited power to close the valuation gap. "Cancellations support the share price but do not change the multiple," Kim said. "The inflection point at which we can expect the premium discount to narrow is the additional return measures that will accompany the third-quarter results at the end of October."
kacew@heraldcorp.com