Samjong KPMG publishes display strategy report
Firms urged to build mass-production competitiveness in form factors, AI capabilities by sector
The global display industry is rapidly shifting its competitive focus from picture quality to form factor innovation and AI-based interfaces. Technologies that reshape screen form — foldable, rollable and stretchable displays — are expanding well beyond smartphones and TVs into vehicles, wearables, extended reality and robots. A new analysis finds that South Korean display companies must secure not only premium technology competitiveness but also mass-production capabilities in form factors and the ability to respond to AI demands across individual industries.
Samjong KPMG released a report Wednesday titled "Display Utilization Strategy Driven by Form Factor Innovation," outlining how the global display market environment is changing and what growth strategies domestic companies should pursue.
According to the report, Korean companies maintain unrivaled competitiveness in the premium market centered on OLED, but competition is intensifying as overseas rivals — including Chinese firms — rapidly advance their technology. It has become urgent for Korean companies to move beyond simply improving picture quality and instead secure technologies and business models capable of generating new demand.
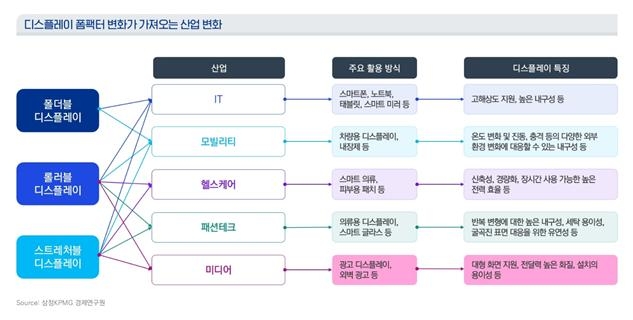
The report identifies three axes of display innovation: picture quality, form factor and AI interface. Picture quality — covering brightness, color reproduction, response speed and power efficiency — remains the foundational competitive baseline. Advances have reached a level that consumers can barely perceive, yet it still serves as an essential technological underpinning for realizing form factor and AI interface capabilities.
Form factor has fundamentally changed how displays look and function, spanning curved, foldable, rollable and stretchable designs. It is now a key driver opening new markets beyond smartphones and TVs, including vehicles, healthcare, fashion and humanoid robots. In the AI interface domain, displays are evolving from mere information-delivery devices into intelligent core components that support device operation and user interaction.
Real-world adoption across industries is also accelerating. Wearables require high brightness, touch functionality and close-fitting designs, while XR and AR applications demand high resolution and speed for immersion alongside lightweight construction, low power consumption and heat management. In the mobility market, curved and rollable displays handling infotainment and controls are gaining prominence as software-defined vehicles spread. The role of displays in robotics is also expanding, with visual signals such as facial expressions and status indicators enabling emotional communication.
Domestic companies are picking up the pace. Samsung Electronics is expanding its foldable lineup, while LG Display has moved into the robotics market by unveiling a P-OLED for humanoid robots, following its large-screen rollable TV technology. Samsung Display has revealed an RGB OLEDoS for smart glasses and XR applications and is supplying variable OLED panels for Hyundai Motor's GV90 SUV.
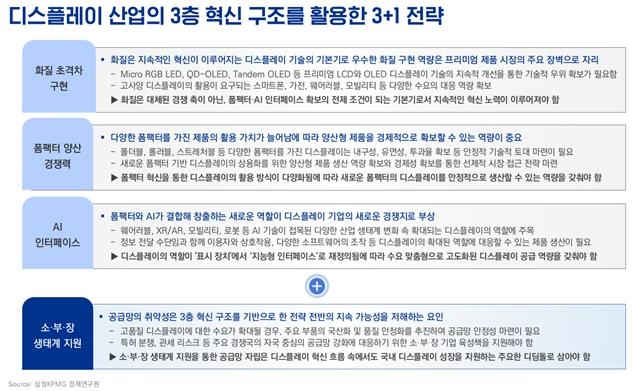
Samjong KPMG said Korean companies should pursue a "3+1 strategy" to secure leadership in next-generation markets. On picture quality, the report said companies must continuously advance premium technologies such as RGB LED, QD-OLED and tandem OLED to proactively meet high-spec demand in mobility and wearables.
On form factor, the report recommended building economical and stable mass-production systems while improving durability, flexibility and transmittance to establish a competitive edge in volume manufacturing. On AI, it identified securing customized supply capabilities optimized for the usage environments of individual industries — mobility, XR and robotics — as a key challenge.
The report added that companies should pursue a parallel "+1 strategy" of diversifying the supply chain for materials, parts and equipment that determine core display performance, while strengthening cooperation with the domestic materials-parts-equipment ecosystem to address patent and trade issues.
"The global display industry has entered a period where differentiation through picture quality alone is no longer viable," said Kang In-hye, vice president and technology industry leader at Samjong KPMG. "Domestic display companies must maintain their premium technology edge in OLED and similar areas while gradually building mass-production competitiveness across diverse form factors and the capacity to develop AI-based solutions tailored to each industry."
Meanwhile, Samjong KPMG — which closes its fiscal year in March — posted operating revenue of 905.6 billion won ($667 million) for the current fiscal year running from April 2025 through March 2026, up about 3.4 percent from the previous year, crossing the 900 billion won threshold for the first time.
an@heraldcorp.com