'Not just loans — all funding channels must be examined'
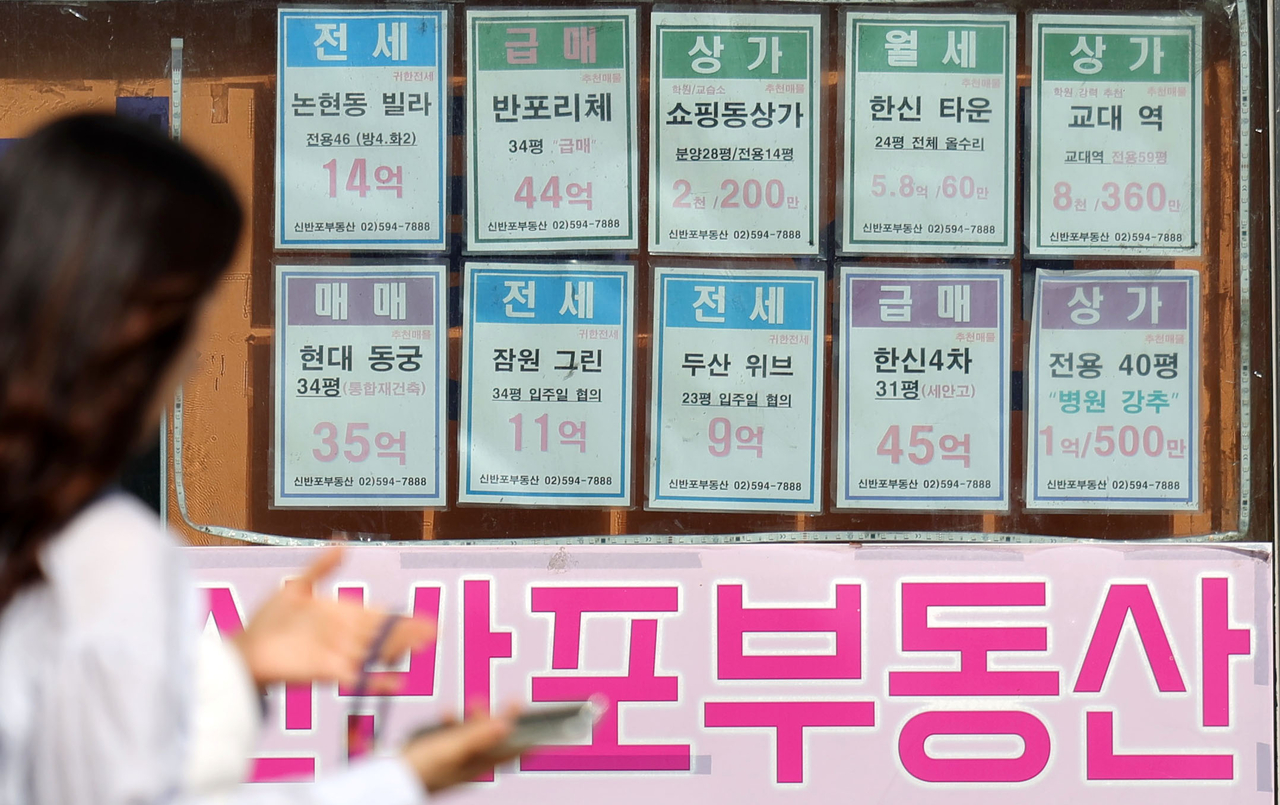
Every 0.25-percentage-point increase in South Korea's benchmark interest rate causes nationwide apartment sale prices to fall 1.2 percent six months later, according to a new study by a state-run research institute, released as the Bank of Korea presses ahead with rate hikes.
The Korea Research Institute for Human Settlements published the findings Sunday in a research note titled "Analysis of Housing Market Volatility During a Period of Rising Interest Rates and Its Implications."
The note's authors — Associate Research Fellow Park Jin-baek, Land and Housing Construction Research Division Head Park Cheon-gyu, and Real Estate Market Policy Research Center Director Jeon Seong-je — said the publication was prompted by a growing need to assess the housing market's exposure to rising rates as rate increases have resumed.
The report found that the downward pressure on housing prices from rate hikes tends to be sharper in the short term during a rising-rate cycle.
"When estimated specifically for a rising-rate period, the cumulative response of nationwide apartment sale prices to a 0.25-percentage-point rate shock is minus 1.2 percent after six months, minus 1.1 percent after 12 months, and minus 0.9 percent after 24 months," the report said.
It added that across the full sample period, the figures were minus 0.5 percent, minus 0.9 percent and minus 1.2 percent, respectively. That indicates that during a rising-rate cycle the price decline hits harder in the near term, while over the full period the effect builds more gradually over a longer lag.
The Bank of Korea's Monetary Policy Board raised the benchmark interest rate by 0.25 percentage points to 3 percent at its Aug. 27 meeting, up from 2.75 percent. It was the second consecutive increase, following a hike in July.
Against that backdrop, the report warned that if rising rates lead to falling housing prices and heavier debt-service burdens on households, borrowers' repayment capacity could deteriorate and the risk of delinquency could rise.
However, the report highlighted that liquidity is flowing into the housing market through a range of channels beyond bank loans — including jeonse deposits, gifts and intra-family borrowing, and proceeds from the sale of shares and bonds. It recommended that housing market monitoring cover all of these funding channels, not just institutional lenders.
An analysis of how Seoul homebuyers financed their purchases showed that the share funded through institutional loans rose from 15.7 percent in 2021–2022 to 22.6 percent in 2023–2025, and further to 23.6 percent in the first four months of 2026.
Over the same period, the shares funded through real estate disposal proceeds, stock and bond sale proceeds, and gifts and inheritances each increased compared with 2021–2022 levels — by 5.0 percentage points, 3.8 percentage points and 2.7 percentage points, respectively, in the first four months of 2026. Notably, the shares from stock and bond sales and from gifts and inheritances nearly doubled, rising from 3.4 percent and 3.7 percent in 2023–2025 to 6.6 percent and 6.4 percent, respectively, pointing to a diversification of funding sources well beyond institutional lending.
"Interest rates and market liquidity are closely interlinked in their effect on the housing market," the Korea Research Institute for Human Settlements said in the report. "Given that market liquidity has been expanding recently, it is necessary to continuously monitor both the interest rate channel and liquidity flows, and to examine the scale and sources of funds entering the housing market."
hss@heraldcorp.com