Samsung Electronics and SK hynix are withdrawing funds from deposits held at commercial banks. Whether banks failed to prepare adequately is an open question, but they are now rushing to issue bank bonds at elevated rates. The extra cost of those bond issuances will ultimately fall on borrowers as higher loan interest. The government made it easy for banks to profit from mortgage lending, and if liquidity management problems persist, ordinary citizens may end up cleaning up the banks' mess.
Samsung Electronics and SK hynix have become the talk of Korea's money markets. As profits surged this year, both chipmakers have been sitting on swelling cash piles — and that "semiconductor money" is now on the move. The shift could raise the interest burden on ordinary household borrowers, though the fault, if any, lies not with the two companies but with the structural and policy shortcomings of Korea's banking system.
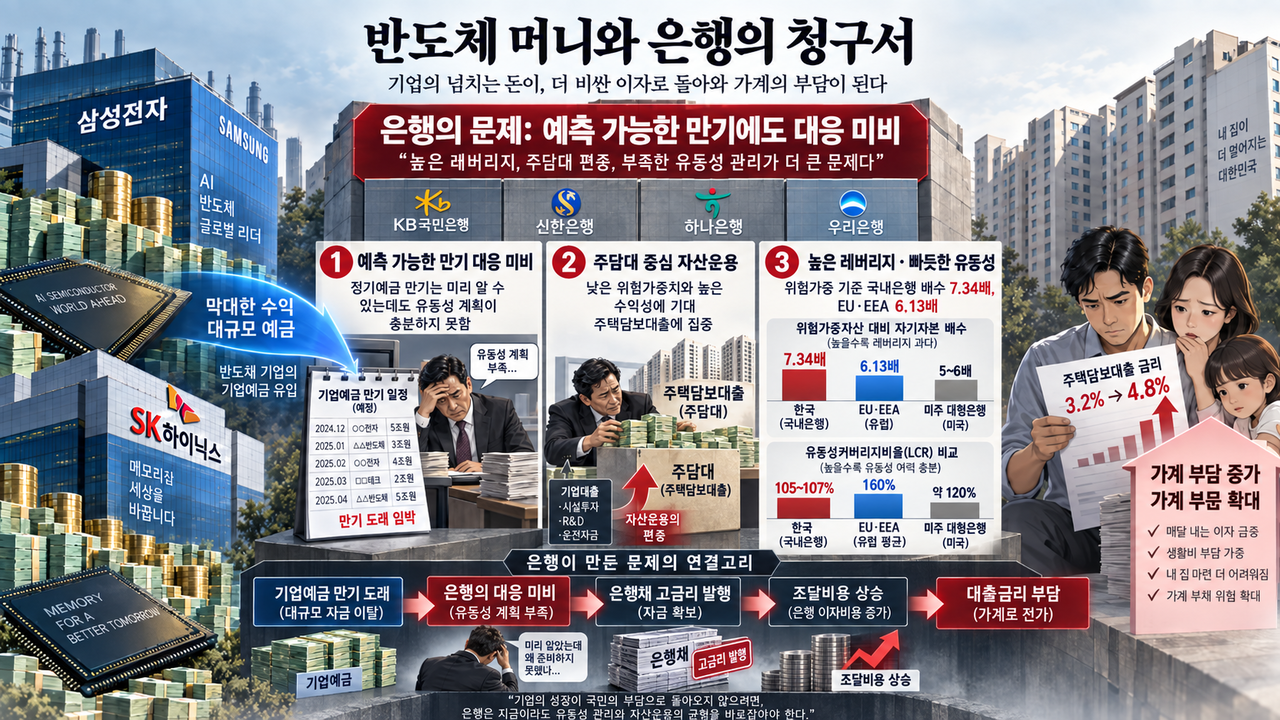
Why the four major banks rushed to borrow at a premium
According to investment banking industry sources, on Thursday Woori Bank issued 850 billion won ($614 million) in nine-month bonds, KB Kookmin Bank issued 360 billion won in 18-month bonds, and Shinhan Bank issued 410 billion won in two-year bonds — at rates 9, 9.4 and 9.3 basis points above their respective fair-value benchmarks.
On Wednesday, KB Kookmin Bank raised 1.1 trillion won, Hana Bank raised 950 billion won, and Woori Bank raised 80 billion won. Kookmin Bank rattled the market by offering a rate as much as 9.6 basis points above the fair-value benchmark for the same maturity. Hana Bank priced 6.4 basis points above benchmark, while Woori Bank issued floating-rate notes at 47 basis points above the one-month certificate of deposit rate.
The Bank of Korea has raised its benchmark interest rate in consecutive moves, and the US Federal Reserve has also tightened policy. Interest rates are heading higher. The yield on one-year government bonds climbed from 3.479 percent on Sept. 8 to 3.676 percent on Monday — a rise of roughly 0.2 percentage points in two weeks. The three-year yield rose from 3.901 percent to 4.056 percent, crossing the 4 percent threshold. On a monthly average basis, the last time three-year government bond yields exceeded 4 percent was October 2023.
Even so, it is unusual for commercial banks with AAA credit ratings to price bonds 9 basis points above benchmark — three to four times the normal margin of error. It signals an urgent need for cash. Market participants believe the banks' funding situation became strained as large corporate deposits, particularly from Samsung Electronics and SK hynix, were withdrawn. The situation itself is hard to understand.
Corporate deposits — especially large ones from major conglomerates — place a significant burden on a bank's liquidity. But fixed-term deposits are not the same as a sudden bank run. Banks know from the moment they accept the money exactly when it must be returned. Preparing for the possibility of withdrawal at maturity is a basic expectation; it is one of the core functions of asset-liability management.
Bank of Korea data make the picture even clearer. Corporate deposits as a share of total deposits at commercial banks reached 35.11 percent at the end of the second quarter this year — the highest since 35.93 percent at the end of 1980. The household share fell to 42.63 percent, the lowest since the end of 2021. Corporate deposits grew by 57 trillion won in the first half of this year alone. Samsung Electronics and SK hynix together increased their cash and short-term financial assets by 34 trillion won on a standalone basis over the same period. Not all of that money flowed into domestic bank deposits, but it is clear that the surge in corporate deposits and the cash accumulation by the two chipmakers proceeded largely in tandem.
Did banks assume these large companies would simply roll over their deposits at maturity rather than withdraw them? Both Samsung Electronics and SK hynix had already announced large-scale investment plans and shareholder return programs, including massive capital expenditure commitments. Yet several banks found themselves scrambling for funds around the same time, paying above-market rates — raising serious questions about whether they had drawn up adequate liquidity plans in advance.
Maximum leverage, mortgage concentration — and tightening liquidity
Most domestic commercial banks fund themselves with short-term deposits — typically maturing in three years or less — and deploy that money into long-term loans such as mortgages, which can run 5 to 30 years. This structural maturity mismatch is inherent to banking. To manage it, banks must maintain a liquidity coverage ratio of at least 100 percent, meaning they must be able to survive a 30-day liquidity stress scenario without external support. At the end of the first half, the LCR for the four major banks stood at 104.95 percent for Shinhan, 104.80 percent for Kookmin, 106.66 percent for Hana, and 107.31 percent for Woori — all within 10 percentage points of the regulatory minimum of 100 percent. By comparison, US banks typically run at 115 to 130 percent, and European banks at 150 to 170 percent.
The net stable funding ratio — which measures how much stable funding a bank has relative to what its assets require — stood at 117.1 percent for Kookmin, 106.7 percent for Shinhan, 105.9 percent for Hana, and 110.3 percent for Woori as of the first quarter. All are well below the EU and European Economic Area average of 126.9 percent.
Why are domestic banks running so tight on liquidity? The answer is straightforward: the more a bank lends relative to the funds it raises, the higher its profit. Pushing lending to the maximum has left liquidity stretched thin.
At the end of 2025, the simple tier-1 capital ratio of domestic banks stood at 6.76 percent, higher than the average leverage ratio of 5.9 percent for EU and EEA banks. Both ratios divide tier-1 capital by total exposure before risk-weighting, so a higher figure means lower leverage.
But the picture changes once risk weights are applied. As of the end of June, the common equity tier-1 ratio of domestic banks — measured against risk-weighted assets — was 13.62 percent. Inverted, that means risk-weighted assets were 7.34 times CET1. The equivalent figure for EU and EEA banks, derived from their CET1 ratio of 16.3 percent, is 6.13 times — roughly 20 percent lower.
Financial regulators did at least raise the risk weight on mortgage loans from 15 percent to 20 percent starting this year. Many European jurisdictions already apply weights above 20 percent. In effect, regulators had long been creating conditions that allowed domestic banks to concentrate heavily in mortgage lending at high leverage.
Corporate deposit maturities could push up the cost of household loans
The cheapest way for a bank to raise funds is through deposits. But with financial regulators capping total household loan volumes, banks have little immediate incentive to grow their mortgage books further. The next-best option is to raise rates on loans already outstanding — and indeed, the spread added to household loan rates has recently widened to a record high.
From a bank's perspective, there is no reason to raise deposit rates and attract more funds if it cannot lend them out anyway. Raising rates on deposits, which make up the bulk of funding, would sharply increase overall costs. In practice, even as market rates have risen steeply this year, bank fixed-deposit rates have remained below government bond yields. Kookmin Bank recently raised its rate on one-to-two-year fixed deposits to 3.5 percent — the highest among major commercial banks — but that still falls short of the 3.676 percent yield on one-year government bonds and the 4.012 percent yield on two-year monetary stabilization bonds as of Monday's close. Bank of Korea data show that fixed-deposit rates first fell below one-year government bond yields in March this year, the first time since August 2022, and the inversion has persisted since. Banks, in short, have no intention of competing for deposits.
For corporations, this means there is little reason to park large sums in bank deposits for extended periods when government bonds offer better returns. From the banks' side, maturing corporate deposits can simply be replaced with bank bond issuances — something that can be planned well in advance. The problem is that poor preparation drives up costs, and the question is who ends up bearing them.
Higher bank bond issuance rates feed directly into lending rates. They affect fixed and hybrid mortgage rates immediately, and can also flow through to variable-rate mortgages via the COFIX benchmark. Total issuance over the two days of Wednesday and Thursday came to 3.75 trillion won. On its own, a 9-basis-point premium on this batch may seem trivial. But if larger volumes of bank bonds continue to be issued at a premium, the cumulative effect becomes significant.
Both Samsung Electronics and SK hynix are expected to have substantial funding needs in the fourth quarter as well. Withdrawals driven by buybacks, dividends and capital investment are likely to continue. Some market observers expect the two companies to pull tens of trillions of won out of bank deposits this year alone.
Meanwhile, the incentive to convert dollar export proceeds into won has diminished sharply from the second quarter as the exchange rate has fallen. Companies may convert what they need immediately, but surplus funds are likely to stay offshore — which could push bank bond issuance rates even higher. On top of that, the five major banks face 27.125 trillion won in bank bond maturities in the fourth quarter, surpassing the 20.3 trillion won recorded in the fourth quarter of 2022 during the Legoland crisis and setting an all-time record. Refinancing demand adds further pressure. This is the channel through which large corporate deposit outflows could raise the interest burden on household borrowers.
Bank of Korea data show that bank bonds account for 12.6 percent of total deposit bank liabilities — just over one-eighth. Given that bank bonds represent roughly one-ninth of total funding, paying an extra 9 basis points on them could push overall lending rates up by about 1 basis point. For an individual borrower with a 100 million won loan, that translates to an extra 10,000 won a year — seemingly small. But applied across the 1,028 trillion won in outstanding household loans at deposit banks, a single basis point adds up to more than 100 billion won a year. This is a cost inherent to the banks' own operations, not one caused by borrowers. Why should ordinary customers be the ones to pay it?
kyhong@heraldcorp.com