① How large will August's current account surplus be?
② How high will September inflation run?
③ What does consumer sentiment show? Semiconductor warmth yet to spread
Burden on vulnerable households a concern, but not a deciding factor
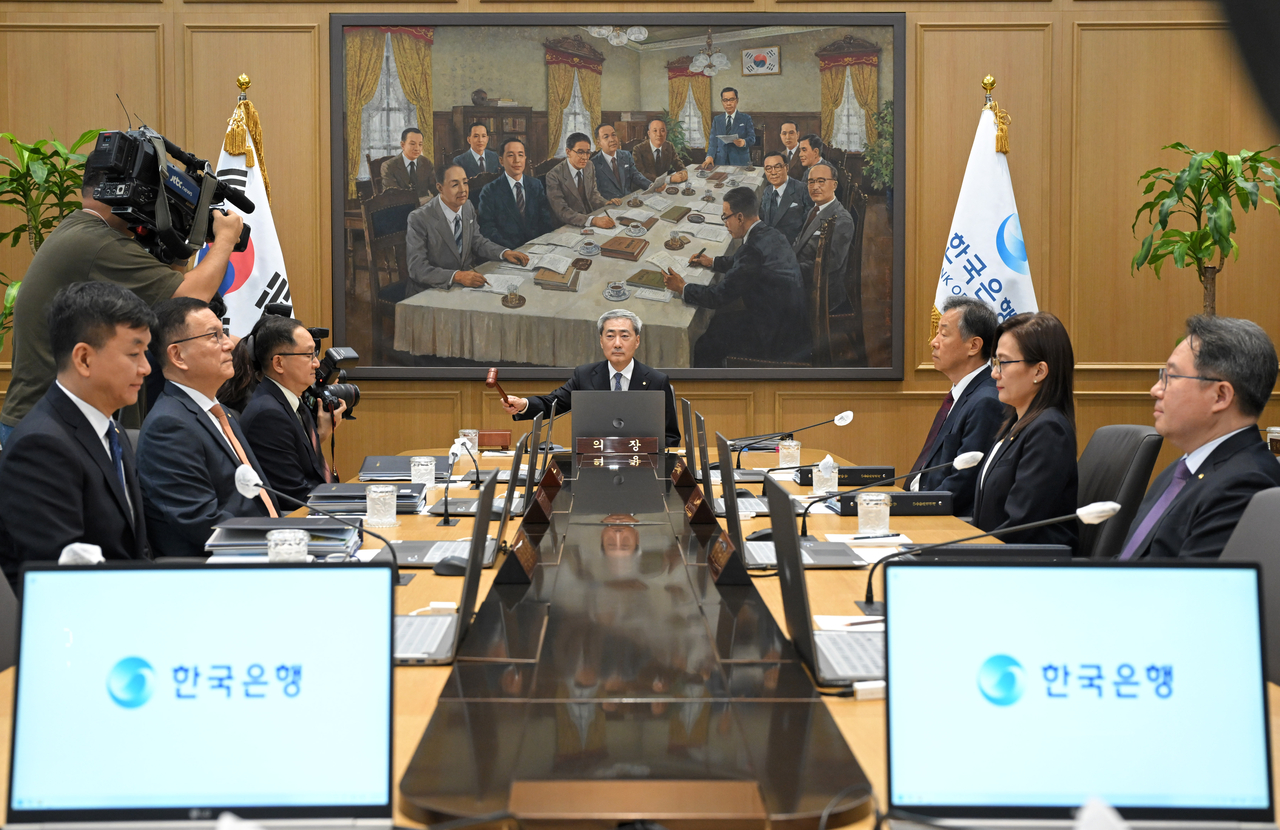
The Bank of Korea's rate-hiking stance is growing increasingly pronounced.
Explosive economic growth driven by the semiconductor sector has shown no sign of slowing, and major central banks — including the US Federal Reserve and the Bank of Japan — have raised rates in quick succession. The reignition of US-Iran tensions has pushed international crude prices back above $100 a barrel, and a renewed rise in the won-dollar exchange rate is amplifying supply-side inflationary pressure.
With an additional benchmark interest rate hike before year-end now widely treated as a foregone conclusion, market attention has shifted to the timing of the BOK's next move. The prevailing view is still that the central bank will pause at its October monetary policy meeting. Governor Shin Hyun-song signaled as much at his most recent press briefing, saying the BOK needed to "assess the effects of consecutive rate hikes" — a hint that the pace of tightening would be measured. But economic conditions have shifted sharply since then, leaving even an October hold far from certain.
Inside and outside the BOK, the key variables for next month's policy decision are seen as the current account balance and broader growth momentum, inflation and economic sentiment.
① Second-quarter growth confirmed — but what will August's current account show?
The strong second-quarter nominal GDP growth that Governor Shin had highlighted at his previous press briefing has now been confirmed. National income statistics released Sept. 8 showed that nominal GDP expanded 26.4 percent year-on-year in the second quarter, driven by improved terms of trade centered on semiconductors — the fastest pace since the third quarter of 1979 (27.7 percent), a stretch of 46 years and nine months, or 187 quarters.
Over the same period, real GDP — which strips out price changes from nominal GDP — grew just 3.7 percent, meaning nominal GDP growth was more than seven times that of real GDP. The widening gap between the two measures reflects how rapidly surging semiconductor prices have improved the terms of trade, with rising semiconductor export prices providing a strong lift to nominal GDP.
The GDP deflator, which tracks prices across all domestically produced goods and services, rose 21.9 percent year-on-year, with the export deflator surging 56.6 percent. The domestic demand deflator, by contrast, climbed only 3.6 percent — meaning the bulk of the price increase embedded in nominal GDP came from export prices.
Real gross national income in the second quarter reached 666.8 trillion won ($483 billion), up 3.1 percent from the previous quarter's 647 trillion won, setting a new all-time high for the second consecutive quarter. The 15.6 percent year-on-year increase was the largest since the fourth quarter of 1988 (15.7 percent), a gap of 37 years and six months, or 150 quarters. GNI measures the total income received by a country's residents, including earnings from abroad. At this pace, per-capita GDP of $40,000 looks well within reach this year.
Before the next monetary policy meeting, the current account balance will offer an additional read on the economy's growth momentum.
The BOK will release August balance-of-payments data on Oct. 8. The July current account surplus set an all-time record for the month at $42.08 billion, lifting South Korea to second place globally in current account surplus rankings for the first half of the year, behind only China. August exports came in at $98.25 billion — the third-highest monthly figure on record, following June and July — making a strong current account reading for August highly likely.
"Semiconductor-driven economic growth is exceeding expectations, and the figures that will be released going forward will be numbers we have never seen before," a BOK official said. "Because those numbers could reflect a statistical illusion — or they might not — this is a moment that calls for wiser judgment than ever."
② Consumer prices back above 3% in August — how far will they fall in September?
Inflation is the indicator the BOK watches most closely. The August consumer price index, released earlier this month, showed a 3.1 percent year-on-year increase, up from 2.8 percent in July — returning to the 3 percent range for the first time in two months and well above the central bank's 2 percent target. A significant part of the August spike, however, stemmed from a base effect: a telecom-fee discount program introduced in August of last year depressed that month's reading, making the year-on-year comparison look larger. Petroleum product prices and agricultural, livestock and fishery prices actually fell. Stripping out the telecom base effect, underlying inflation is estimated at around 2.5 percent.
Core inflation — which excludes food and energy — rose 3.4 percent year-on-year, up 0.8 percentage point from July's 2.6 percent and the highest since May 2023. The telecom base effect also played a role in the core reading, but sources inside the BOK say the increase was larger than expected even accounting for that distortion.
Both headline and core inflation are expected to ease in September from August levels, though core inflation may remain elevated for some time. BOK Deputy Governor Lee Ji-ho said at a price-monitoring meeting that September consumer price growth would come in below August's as the base effect fades, but that underlying prices would continue their upward trend, led by core items.
The BOK expects demand-side pressure from the semiconductor boom to keep core inflation elevated for an extended period. Strong semiconductor exports are boosting national income, and rising incomes are expected to sustain upward pressure on prices. Governor Shin said at last month's monetary policy press briefing that "the likelihood has grown that core inflation will remain high through next year, with price pressures broadening and persisting longer."
Supply-side price pressures are intensifying again as international oil prices rise and the won-dollar exchange rate climbs once more.
According to Korea National Oil Corp., Dubai crude prices surged 28.1 percent in just 15 days, jumping from $99.9 per barrel on Sept. 1 to $128 on Wednesday. Brent and West Texas Intermediate crude rose 11.7 percent and 13.5 percent, respectively, over the same period. The won-dollar rate, which had been falling through August, reversed course and climbed for seven consecutive trading days from Sept. 9 (1,336.1 won, weekly closing basis) through Friday (1,383.3 won), driven by rising oil prices and the impact of US rate hikes.
When oil prices and the exchange rate rise in tandem, import prices spike — and with a lag, that feeds through to consumer prices.
③ Will semiconductor gains spread to the broader economy? Sentiment data and industrial activity in focus
The BOK is also watching closely how quickly and broadly semiconductor-led growth is spreading through the wider economy. If the income gains concentrated at chipmakers such as Samsung Electronics and SK hynix fail to translate into stronger domestic demand, demand-side inflationary pressure could come in below the central bank's projections.
The BOK's decision to break with convention and raise rates in consecutive meetings was aimed at getting ahead of demand-driven price pressures. If those pressures turn out to be less intense than feared, the side effects of rate hikes could end up being the more prominent story.
Signs of this dynamic are already emerging. A recent BOK report estimated that in Icheon — a city in southern Gyeonggi Province with a high concentration of semiconductor workers — a significant share of performance bonuses has gone toward housing-related spending and real estate purchases in the southern part of the province. In South Korea, households with a higher ratio of housing assets to income tend to cut back on consumption, meaning that if rising incomes flow into assets rather than spending, the boost to domestic demand could be limited.
The recent divergence between corporate and household sentiment points in the same direction. Profitability at semiconductor companies has been improving, but those gains do not appear to be translating into broader household income growth.
Of the 9.2 percent nominal GDP growth recorded in the second quarter, gross operating surplus — a measure of corporate net profit — rose 18.5 percent, while compensation of employees grew just 1.9 percent. The operating surplus growth rate widened by 1.5 percentage points from the previous quarter's 17 percent, while employee compensation actually slowed, falling from 4 percent to 1.9 percent — a drop of 2.1 percentage points.
The divergence is also visible in sentiment indexes. The composite business sentiment index rose 1.1 points from the previous month to 99.6 in August, its highest since September 2022 — nearly four years ago. The consumer sentiment index, meanwhile, fell 2.3 points to 104.5, snapping a four-month uptrend.
July industrial activity data told a similar story. The retail sales index, which tracks goods consumption, fell 2.4 percent from the previous month. After declining in April (minus 3.7 percent) and May (minus 0.1 percent), retail sales had briefly rebounded in June (up 2.7 percent) before turning lower again within a month. Capital investment, by contrast, rose 7.5 percent, led by semiconductors, extending its gain for a second consecutive month.
How much consumer and business sentiment improves in the consumer survey due Wednesday and the business conditions survey due Sept. 29, and what the August industrial activity report due Sept. 30 shows for consumption, investment and production, will be among the other key factors shaping the BOK's next policy move.
Interest burden on vulnerable households: a factor, but not a deciding one
The interest burden that rate hikes place on vulnerable households is another concern. Minutes from last month's monetary policy meeting show that worries about financial stress among lower-income borrowers were raised on multiple occasions.
One board member said the BOK needed to "determine the timing of rate hikes while monitoring the impact on different economic actors, so as not to impose an unbearable burden on those who have yet to feel the benefits of the economic recovery." Another member stressed that while consecutive rate hikes were "judged to be within the tolerance of the majority of economic actors, the expanded burden on some vulnerable groups and the latent risks that entails must be carefully monitored."
Even so, the burden on vulnerable households is unlikely to become a decisive factor in the policy decision.
A senior BOK official said of the issue that while it would be "taken into account in monetary policy, fiscal policy needs to play a role because there are limits to what monetary policy can address." Because monetary policy applies uniformly to everyone rather than targeting specific groups, easing the burden on vulnerable households falls within the domain of fiscal policy, the official said.
Governor Shin made a similar point at the July monetary policy press briefing, saying that for the interest burden on vulnerable households stemming from rate hikes, "fiscal or financial policy, which can deliver more targeted effects than monetary policy, seems most appropriate."
kimstar@heraldcorp.com