Bank of Korea's won settlement network to support offshore won transactions
Overdraft borrowing for settlement purposes allowed without limit; reporting threshold raised
Won-denominated capital transactions between nonresidents exempt from reporting, except domestic real estate
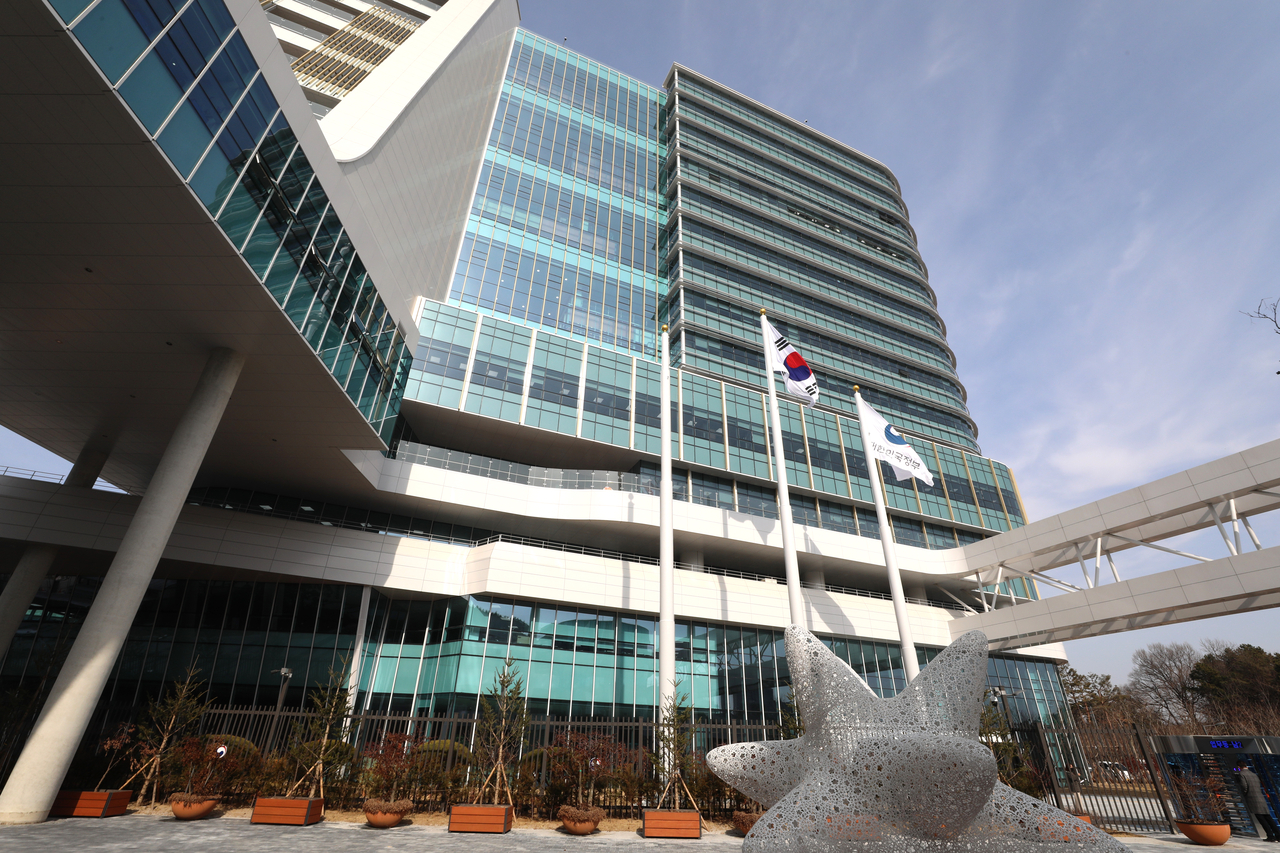
South Korea will introduce a regime allowing qualified foreign financial institutions to support won-denominated payments for nonresident customers from abroad. The reporting requirement for won-denominated capital transactions between nonresidents will also be waived.
The Ministry of Economy and Finance said Wednesday it had promulgated revised guidelines on foreign exchange operations by foreign financial institutions, along with amendments to the Foreign Exchange Transaction Regulations.
The revisions are part of measures to build an offshore won settlement system under the government's "won internationalization roadmap," announced in July.
The amendments formalize a new category of "overseas won business" — won-related foreign exchange operations conducted abroad for nonresidents — and establish a new license class, the Registered Foreign Institution for Korean Won (RFI-K). Foreign financial institutions already registered as Registered Foreign Institutions (RFI) that wish to handle won business must register separately. The RFI-K is a won-specialist license built on top of the existing RFI framework.
Foreign institutions registered as RFI-K will be able to settle won transactions by opening an integrated account at a domestic foreign exchange bank, which in turn connects to the Bank of Korea's won international settlement network. This will establish an offshore won settlement system allowing won transactions to be conducted without restrictions on time or location.
RFI-K institutions will be permitted to open won accounts for foreign nonresident customers abroad and handle remittances, investment and lending transactions. Their scope of business will also cover holding, procuring and managing won — including won payments, receipts and deposits. However, customers must be foreign nonresidents, and foreign financial institutions with deposit-taking functions, such as banks, are excluded.
The reporting requirement for won-denominated capital transactions between nonresidents will also be waived. Domestic real estate transactions, however, are excluded from the reporting exemption.
To help institutions secure the won liquidity needed for settlement, overdraft borrowing from domestic banks for settlement purposes will be permitted without limit. The reporting exemption threshold for won borrowing will be raised from 30 billion won ($22.2 million) to 100 billion won.
Oversight mechanisms for offshore won transactions have also been put in place. RFI-K institutions must verify that their customers are nonresidents and submit monthly transaction records to the Bank of Korea, including identifying information on senders and recipients, transaction amounts, currency types, and transaction and settlement dates. As with existing RFI institutions, they may delegate compliance obligations to an agent.
The government plans to conduct prudential oversight of RFI-K institutions and monitor transaction records and compliance together with the Bank of Korea and other relevant authorities. Provisions have also been established to allow restrictions, when necessary, on the methods RFI-K institutions use to raise and deploy won funds, as well as on the scope of their assets and liabilities.
y2k@heraldcorp.com