New 'Woori Ai Jarip Fund' to launch
Low-income children to receive 1.2 million won annually even without parental contributions
Projected maturity value of 42.94 million won after 19 years at 6% annual return
Income requirement scrapped for Youth Future Savings; regional SME youth contribution rate raised to 25%
The government will introduce a new child asset-building fund designed to accumulate wealth for children from birth through adulthood. For low-income children, the government will contribute 1.2 million won annually even without parental contributions, with the aim of building up to around 100 million won in seed money by the time the child reaches adulthood through additional parental deposits and long-term investment.
The Financial Services Commission unveiled the plan Friday at a "Youth Budget Unboxing 2027" event held at Cheong Wa Dae, attended by President Lee Jae-myung. The initiative links three programs — the Woori Ai Jarip Fund, a child asset-building fund; the Youth Future Savings account; and a Youth Opportunity Fund for job seekers — to support asset accumulation from birth through entry into the workforce.
Under the Woori Ai Jarip Fund, parents and the government jointly contribute to an account from the child's birth until age 18, with the funds invested long-term in capital markets such as stocks and funds. Government contributions vary by income level, and withdrawals are in principle not permitted before maturity. The FSC is designing the fund to yield a maturity value of roughly 60 million won to as much as 100 million won.
Support is more generous for lower-income households. For children in households earning below 50 percent of the median income, the government will deposit 1.2 million won per year even without any parental contribution. For households earning between 50 and 100 percent of the median income, the government will add 1 million won when parents contribute 500,000 won annually. For households between 100 and 150 percent of the median, the government will match parental contributions of 1 million won on a one-to-one basis. Households above 150 percent of the median income are excluded from government matching.
The plan also targets the compounding effect of long-term investment. Assuming an average annual return of 6 percent, the FSC estimates that investing 1.2 million won per year over 19 years would yield a maturity balance of about 42.94 million won. At an annual investment of 2 million won, the same period would produce roughly 71.57 million won. With additional parental contributions on top of government support, the maturity value could reach around 100 million won.
A key feature of the new system is that it extends asset-building support to childhood, whereas existing policy had only kicked in after young people entered the workforce. The government aims to reduce wealth gaps that open up from early childhood depending on parental assets and savings capacity, by creating a continuous asset-formation framework spanning childhood through young adulthood. According to related ministries, the asset gap between young and elderly Koreans widened from 2.4 times in 2012 to 3.9 times in 2024.
After reaching adulthood, the Youth Future Savings account takes over the asset-building role. The FSC will eliminate the income requirement for the standard-tier Youth Future Savings account, allowing any young person who meets the age requirement to enroll regardless of income level. Previously, applicants had to meet both income and household criteria.
Government contribution rates for young workers at small and medium-sized enterprises will also be expanded. The preferential contribution rate for youth employed at general SMEs will rise from 12 to 15 percent, and a separate preferential track will be created for youth working at SMEs in regional areas, raising their contribution rate to 25 percent.
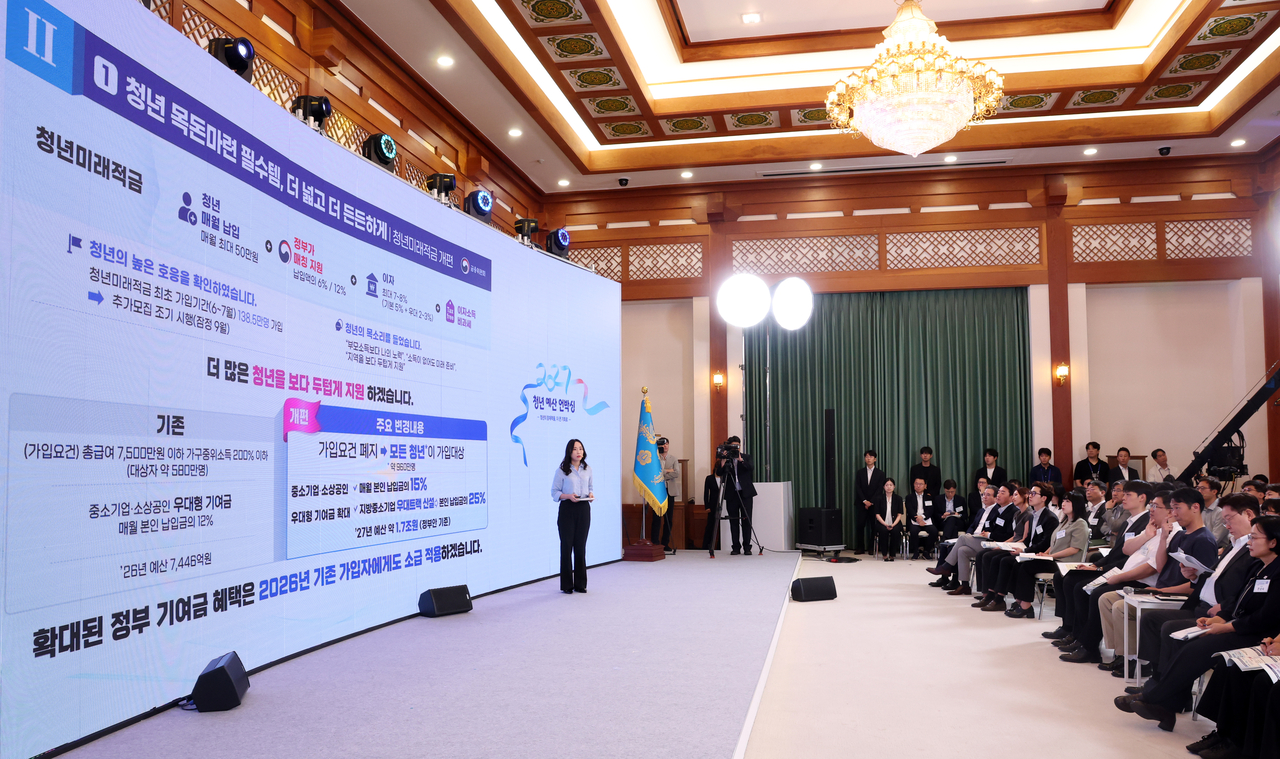
Assuming monthly contributions of 500,000 won over three years — a total of 18 million won — the standard-tier account would pay out a maximum of 21.38 million won including principal, government contributions and interest, while the preferential tier would yield up to 23.13 million won. The regional SME preferential tier would pay out a maximum of 25.07 million won at maturity, which the FSC said is equivalent to an annual simple-interest rate of about 30.1 percent on a standard savings account.
A new Youth Opportunity Fund will also be created for young people who lack income before finding employment. The fund will provide up to 20 million won over a lifetime to unemployed youth earning no more than 35 million won annually, with no interest charged during a grace period before employment or business launch. Repayment will follow at an annual interest rate of 2 to 5 percent. The single-loan limit is 5 million won, with an annual cap of 7.5 million won.
Including these asset-building measures, the government plans to increase fiscal investment in youth by stage of life by 53.5 percent, from 28.2 trillion won ($20.4 billion) this year to 43.3 trillion won next year.
Meanwhile, through its Aug. 13 real estate and financial measures, the government had already introduced a new "Youth Future Home Loan" available to young people aged 39 or under purchasing a non-apartment property valued at 400 million won or less for the first time in their lives.
rim@heraldcorp.com