US Treasury yields have climbed to their highest level in 19 years, yet gold prices have simultaneously hit a three-month high — upending the textbook relationship in which rising rates push gold lower. Retail money is pouring into gold ETFs, and analysts say the divergence reflects a fundamental shift in what is driving yields: the culprit is no longer inflation fears but growing distrust of America's fiscal position.
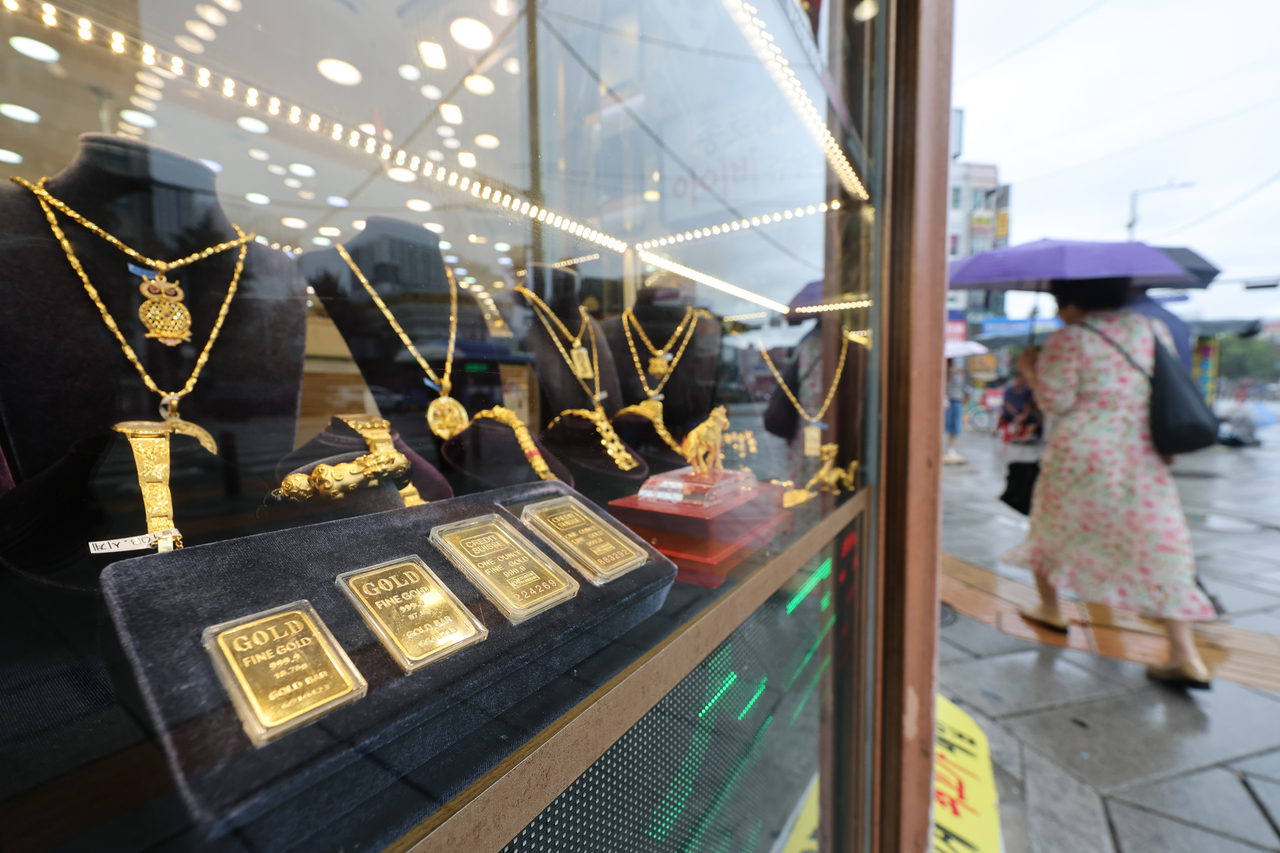
Spot gold traded around $4,660 per ounce Tuesday (local time) in New York, up roughly 0.3%, after touching its highest intraday level in more than three months before paring gains. Compared with a month ago, the price has risen nearly 15%.
On the same day, the yield on the 10-year US Treasury note fell 6.5 basis points to 4.638%, while the 30-year yield dropped 5.6 basis points to 5.174%. Both remain elevated despite the modest pullback. The 30-year yield hit a 19-year intraday high on Aug. 18 and has since hovered in the 5% range, while the 10-year yield touched a 19-month high of 4.75% that same day and has since settled around 4.6%.
In theory, gold and interest rates move in opposite directions. Because gold pays no interest or dividend, higher rates raise the opportunity cost of holding it, pushing capital toward yield-bearing assets such as government bonds.
That relationship held during the first half of this year. Gold futures hit a record closing high of $5,318 per ounce at the end of January before falling roughly 25% to around $3,990 in June. The slide came as escalating tensions between the United States and Iran drove up oil prices in late February, stoking inflation fears and prompting markets to price out Federal Reserve rate cuts — and even begin factoring in the possibility of hikes.
The current environment is different. Since August began, long-term yields have surged to 19-year highs while gold has simultaneously jumped nearly 15%. Analysts say the parallel rise reflects a change in the underlying driver of higher rates.
Long-term interest rates are shaped by two broad forces. The first is the market's expectation of the policy rate path: if inflation looks likely to rise, investors anticipate that the Fed will raise its benchmark rate, sell Treasuries and push yields up across the board. That environment is unfavorable for gold, which pays nothing. The sharp drop in gold prices during the first half of this year fell squarely into this category.
The second force is the term premium — the extra yield investors demand as compensation for the risk of holding long-term bonds to maturity. When fiscal deficits widen and Treasury issuance surges, investors begin to question whether they will be repaid in full decades from now, and they demand higher rates accordingly.
In that environment, rising yields carry a different message. They signal not that money has become more expensive, but that confidence in government bonds as an asset has eroded. When the need to offer ever-higher yields is itself read as a warning sign, capital seeking a long-term store of value may abandon Treasuries in favor of gold — another traditional store of value. Fiscal anxiety, in other words, can push both bond yields and gold prices higher at the same time.
"If you consider that long-term yields are reflecting doubts about fiscal credibility, the relationship is not hard to understand," said Lee Eun-taek, a director at KB Securities. "Investors who believe upward pressure on long-term yields will be difficult to contain should consider gradually accumulating gold from a long-term perspective." He added that if long-term yields stabilize in the near term, gold's rally could pause temporarily.
Domestic retail investors are already moving quickly into gold ETFs. Net purchases by retail investors in the ACE KRX Gold Spot ETF, managed by Korea Investment Management, have exceeded 200 billion won ($145 million) since the start of the year.
According to Korea Exchange, retail net purchases of the product from the start of the year through Monday totaled 211.6 billion won. More than 65.5 billion won flowed in during August alone, with retail net buying recorded on every single trading day this month. Over the past year, retail net purchases have reached 1.04 trillion won.
Total net inflows from the start of the year through Monday came to 693.5 billion won — the largest among the 28 commodity ETFs listed in South Korea. As of Monday, the fund's net assets stood at 4.27 trillion won, making it the largest commodity ETF in the domestic market.
Returns have also recovered. The KRX gold price rose 11.3 percent per gram from the first trading day of August through Monday, while the ACE KRX Gold Spot ETF gained 12.76 percent over the same period. Returns over the past one year, three years, and since listing stand at 38.07 percent, 147.72 percent and 191.45 percent, respectively.
The accessibility of ETFs compared with physical gold is another factor drawing in capital. Physical gold such as bullion bars carries a 10 percent value-added tax and fabrication fees at the point of purchase, along with storage costs, whereas ETFs can be bought and sold in small amounts through a brokerage account just like stocks and can also be held in pension accounts. Products that track a spot index rather than a futures index also avoid the rollover costs that arise from periodic contract switches.
"As volatility in equity assets has increased recently, demand from retail investors looking to add physical gold ETFs to their portfolios has grown," said Nam Yong-su, head of the ETF division at Korea Investment Management. "Unlike exchange-traded futures products, physical gold ETFs do not incur rollover costs from monthly contract switches, making them more cost-efficient for long-term holders."
th5@heraldcorp.com