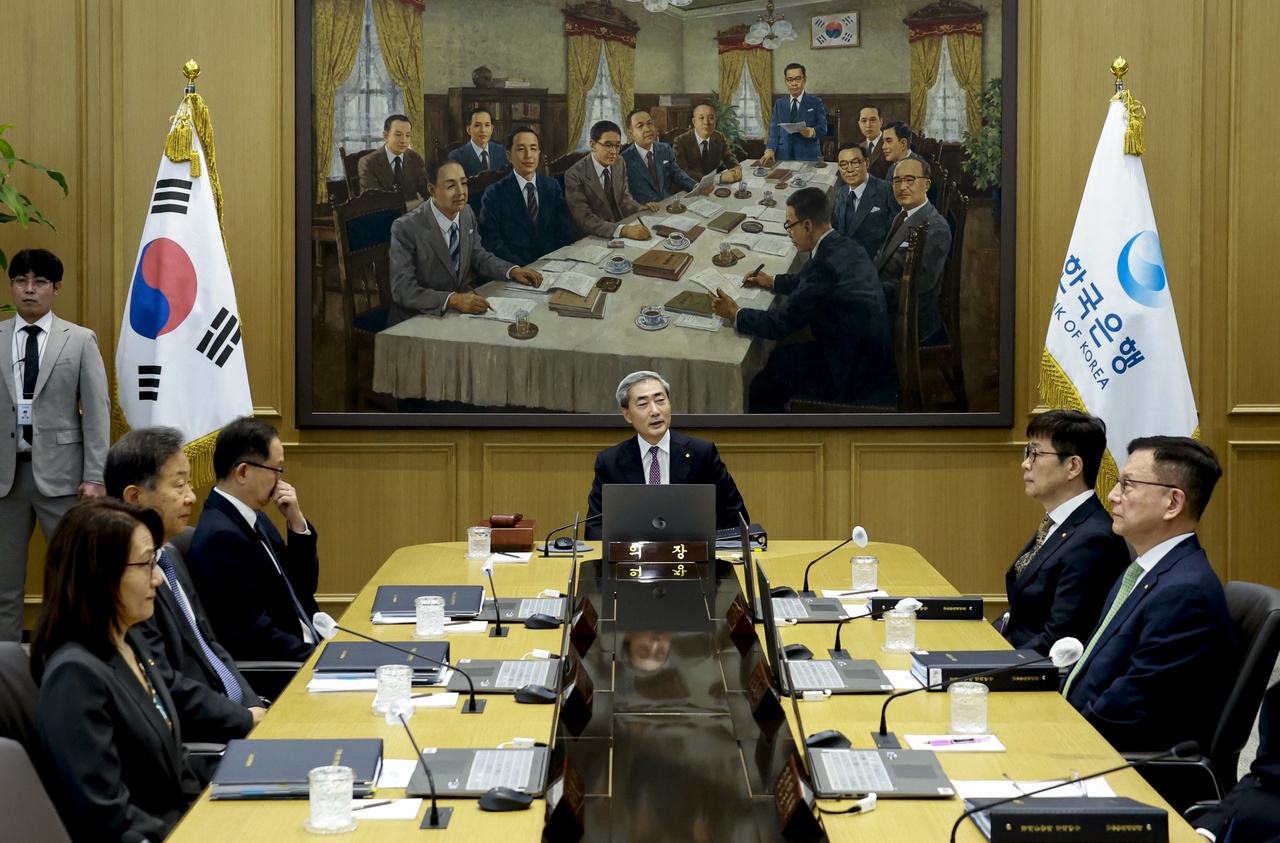
The Bank of Korea's Monetary Policy Board raised the benchmark interest rate from 2.5 percent to 2.75 percent on July 16, and minutes from that meeting show members signaled the need for further hikes, citing concerns that a semiconductor-driven economic boom could translate into demand-side inflation pressure.
The minutes of the 13th Monetary Policy Board meeting on monetary policy direction, released Tuesday, show all seven board members voted unanimously to raise the benchmark interest rate to 2.75 percent at the July 16 meeting. The decision marked a reversal within a month after the board had voted 5-2 to hold rates at its June meeting.
The unanimous decision to raise rates was driven largely by a sharp surge in nominal growth fueled by the semiconductor sector's strong performance. One board member said the economy was benefiting from structurally strong global demand for semiconductors and improved terms of trade, which were sustaining export momentum and were expected to lift domestic demand conditions. "As the semiconductor boom continues, the resulting improvement in corporate and household income is expected to gradually feed through to domestic demand via investment and consumption, further expanding upside pressure on growth," the member said.
Rising inflation reinforced the case for tightening. Consumer prices climbed more than 3 percent for two consecutive months in June, while core inflation held at 2.5 percent. One member warned that inflation could remain elevated well above the Bank of Korea's 2 percent target for an extended period, not just in the near term. "With core inflation next year forecast to remain quite high due to indirect and second-round effects of supply shocks, we should also be mindful that the downward base effect from oil prices — a disinflationary factor in 2027 — could disappear by 2028," the member said.
Most members did not view the July hike as a one-off move. One member said the increase alone was unlikely to be sufficient to achieve the inflation target and that rates would need to continue rising in line with the growth and inflation outlook. "Given significant uncertainty surrounding the breadth of the semiconductor cycle, inflation trends, and financial stability, we will need to reassess the outlook and the degree of risk in light of incoming data, and weigh the merits of preemptive versus gradual responses in determining the pace of further hikes," the member said.
Another member said monetary policy should determine the timing and pace of additional rate increases by closely monitoring inflation as well as growth trends, financial stability conditions, major central banks' policy shifts, and the effects of government economic policy. "As underlying inflation pressure is expected to rise, we need to further strengthen efforts to anchor inflation expectations and entrench price stability through preemptive monetary policy responses and careful policy communication," the member said.
A third member said the cumulative impact of oil price shocks was gradually spreading and that demand-side inflation pressure was building as the economic recovery broadened, which would push up underlying inflation. "Inflation expectations rose immediately after the Middle East war broke out and have since moved sideways, but the possibility that they could rise further as the domestic economy expands cannot be ruled out," the member said.
Members also raised concerns that further tightening could weigh on vulnerable households. One member said fiscal and other support measures should be discussed to ease the burden on some lower-income groups during the monetary tightening process. "Given the significant uncertainty surrounding the growth and inflation outlook, the timing of any additional benchmark interest rate increase should be determined by closely monitoring the pace of energy supply chain recovery, the domestic spillover effects of the semiconductor cycle, and the impact of rising income and asset values on liquidity flows into asset markets," the member said.
kimstar@heraldcorp.com